
By Gareth Vaughan
Bad loans are almost as rare as hen's teeth and banks aren't expecting the picture to worsen anytime soon, KPMG says in its June quarter Financial Institutions Performance Survey (FIPS).
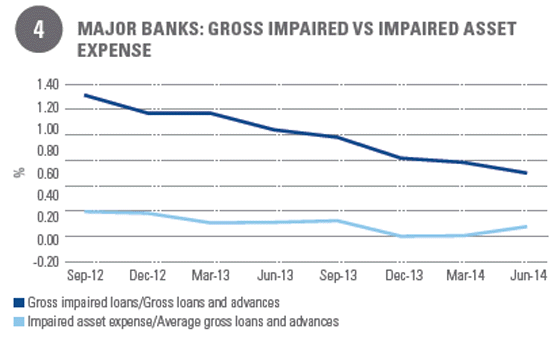
The auditing and financial advisory firm says at the equivalent of just eight basis points of gross loans and advances, banks' loan impairments are well down on the long-term average of 19 basis points.
"Bad loans are harder to find than a cheap house in Auckland," KPMG says.
And even though asset quality deteriorated in the June quarter, this merely moved the level of impaired loans from minuscule to tiny, adds KPMG.
"In the previous two quarters ended December 31, 2013 and March 2014, the total impairment expense for all sector participants were $7.9 million and $10.7 million respectively, resulting in an almost nil (0.01%) impaired asset expense to gross loans and advances ratio. For the June quarter, this ratio has returned to a more normal level at 0.08%, slightly below the ratios seen pre the (Reserve Bank's ) LVR (restrictions) implementation."
Impaired asset expense did, however, rise $55.5 million, or 522%, in the June quarter to $66.2 million at June 30 from $10.7 million at March 31. This was driven by a $39 million increase at ANZ, $12 million at Westpac, and $11 million at CBA.
"Despite impaired asset expense increasing during the quarter, both the collective provisioning and individual provisioning decreased when compared to the size of their loan books, indicating that overall, banks are confident in the strength of the economy and are expecting less impairment in the future," KPMG says.
"This is further shown by the total provision for doubtful debts over gross loans and advances ratio having reduced every quarter since 31 March 2011, and is now at 0.60% at 30 June 2014. This was mainly driven by reductions of the collective provisioning rather than individual provisioning."
Banks 'riding Reserve Bank OCR rate changes well on the way up'
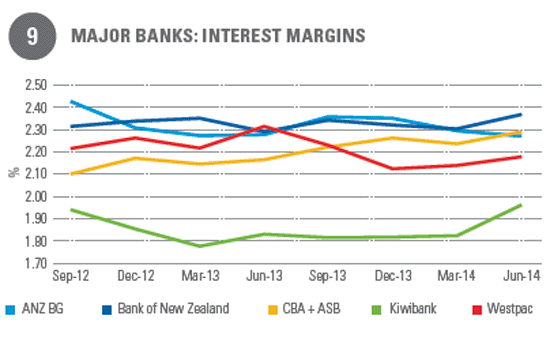
Meanwhile, of the nine banks surveyed only ANZ recorded a net interest margin fall, down to 2.27% from 2.29% in the March quarter. KPMG attributed the ANZ drop to increased interest expense, and asset pricing pressure. The participants' overall net interest margin rose seven basis points to 2.29%.
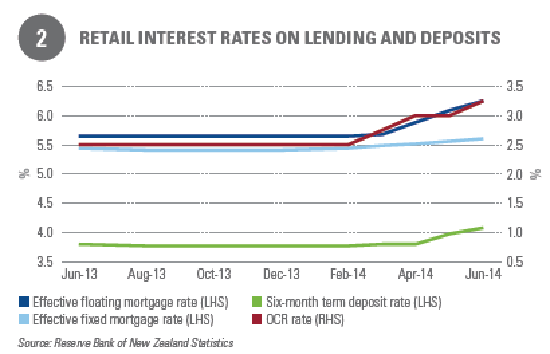
"This indicates that overall the sector is riding the Reserve Bank OCR rate changes well on the way up and the growing competitiveness in retail mortgages is still allowing some margin growth," KPMG says.
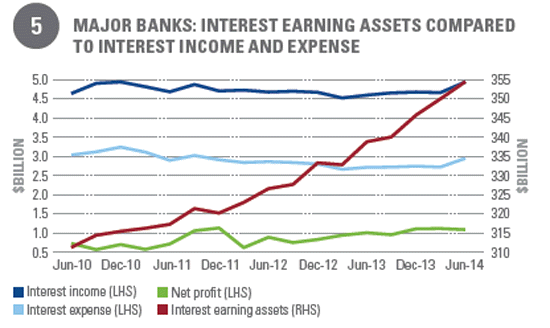
Interest earning assets for the sector grew 1.22% in the June quarter, versus 1.18% in the March quarter. Most of the growth was driven by ANZ and Westpac, who increased interest earning assets by 3.2% and 1.9%, respectively. Total assets rose to a record high, up 0.83% in the June quarter, and 2.38% year-on-year, to $390 billion.
Removing ANZ's March quarter one-off $91 million insurance settlement, June quarter "normalised" profit across the banks rose 6.2%, KPMG says. When the ANZ one-off is included, June quarter net profit after tax across the banks dropped about $25 million to $1.125 billion.
The FIPS survey covers ANZ, BNZ, Commonwealth Bank of Australia's New Zealand operations including ASB, Heartland Bank, Kiwibank, SBS, the Co-operative Bank, TSB and Westpac.
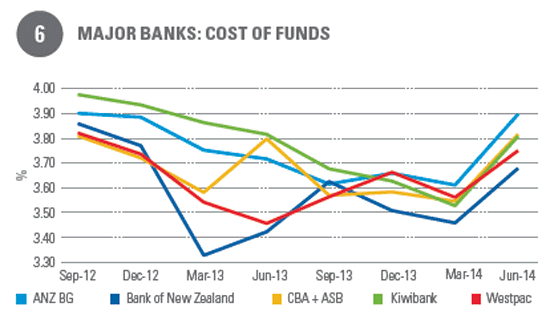
*The charts below are taken from the FIPS report.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.