By Barry Eichengreen*
On November 4, the US Treasury issued its quarterly policy statement of guidance to dealers in federal government securities. This dry and technical document is in fact critical for financial stability. It enables the broker-dealers who are the big dogs in US debt markets to plan for what comes next. Specifically, it provides them with guidance on the inventories of securities they should acquire in order to meet the needs of other market participants.
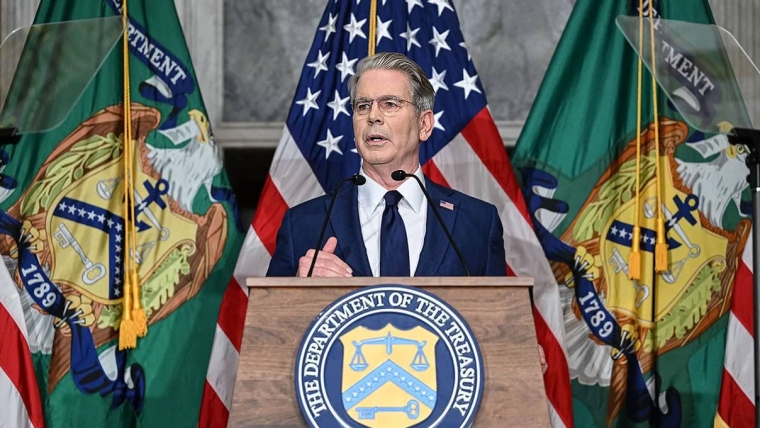
The latest statement reiterated Treasury Secretary Scott Bessent’s commitment to accelerate buybacks of longer-term debt and issue more Treasury bills and short-term notes in their place. Bessent’s strategy promises budgetary savings. But it comes with risks.
The budgetary savings derive from the fact that yields on ten- and 30-year bonds are higher than on one- and three-month bills. The difference currently is 1–1.5 percentage points (100–150 basis points in market-speak). With the Treasury on course to issue upwards of $2 trillion in net marketable debt over the next four quarters to finance ongoing federal budget deficits, and with a comparable amount of long-term debt maturing, the Treasury stands to save maybe $40 billion in debt servicing costs by issuing bills. That’s not chump change.
But no lunch is free, as economists like to say. When issuing long-term debt, the Treasury is insulated from short-term fluctuations in borrowing costs. But if it issues bills and inflation accelerates, due perhaps to the resumption of war in the Middle East or because the Federal Reserve was too sanguine when it failed to raise its policy rate last month, the additional inflation will quickly translate into higher borrowing costs.
The jump in borrowing costs will then add to the budget deficit, triggering a vicious cycle. To absorb more debt, investors will demand even more compensation, in the form of higher interest rates, leading to even more debt service and an even larger budget deficit.
At some point, investors could grow sufficiently worried about the fiscal outlook that they refuse to buy the government’s debt at any price. The Treasury could still lean on the Fed to buy it, but this would be an unhappily inflationary outcome for all concerned.
No one expects this “rollover crisis” to materialize overnight. But the shorter the maturity structure of the debt, the more this distant prospect is brought forward toward the present.
Excessive issuance of short-term Treasury bills can also damage the economy’s financial plumbing and the Fed’s ability to guide the economy. The more T-bills the government issues, the higher their yield, and the more commercial banks will be tempted to hold those bills instead of cash. But banks also face regulations dictating how much cash they must have on hand. So when their cash falls to low levels, they stop lending to other banks. The interest rate on their overnight loans (the Secured Overnight Financing Rate, or SOFR) then begins to diverge from the Fed’s preferred interest-rate level (federal funds rate). To reassert what central bankers call “monetary control,” the Fed is forced to buy T-bills itself, injecting cash into the economy and driving the SOFR back down toward the Fed target.
In recent years, the Fed has felt compelled to engage in such interventions from time to time. But more T-bill issuance will imply the need for more frequent interventions, running up against Fed Chair Kevin Warsh’s stated preference for a smaller balance sheet—that is, for less intervention.
This will not be an easy circle to square. A smaller Fed balance sheet leading to less intervention in the T-bill market will mean less interbank lending. This will limit the ability of banks, short of cash, to provide liquidity to customers such as hedge funds with their own considerable cash needs. Thus, what happens in the T-bill market won’t stay in the T-bill market. It will spill over to other financial markets when leveraged hedge funds, bereft of bank loans and unable to finance their positions, are forced to liquidate other investments.
Warsh could scale back his aspiration to shrink the Fed’s balance sheet. Or Bessent could scale back his strategy of issuing additional short-term debt. The two officials reportedly meet weekly for breakfast or lunch. This would be a good topic of conversation.
Bessent is the federal government’s “chief financial officer.” An organization’s CFO is responsible for more than its current financial health. The CFO is also its lead risk manager. Bessent and his Treasury colleagues would do well to attend not just to the immediate fiscal benefits of their debt management strategy but also to how it could go wrong.
*Barry Eichengreen, Professor of Economics at the University of California, Berkeley, is the author, most recently, of In Defense of Public Debt (Oxford University Press, 2021). Project Syndicate, (c) 2026, published here with permission.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.