sign up log in
Want to go ad-free? Find out how, here.

A review of things you need to know before you sign off on Wednesday; more mortgage rate changes, business sentiment not rattled, households seek TD interest earnings, oil prices fall, swaps fall, NZD firms, & more

Economy / news
A review of things you need to know before you sign off on Wednesday; more mortgage rate changes, business sentiment not rattled, households seek TD interest earnings, oil prices fall, swaps fall, NZD firms, & more

Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).

MORTGAGE RATE CHANGES
ANZ has trimmed two key rates to match some of its more competitive rivals. Details here. TSB also changed rates, some up one down. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.

TERM DEPOSIT/SAVINGS RATE CHANGES
TSB raised many TD rates today. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.

MILK POWDER PRICES RISE
The overnight Pulse dairy auction delivered mixed results although both the SMP and WMP prices rose from the prior event, up by about +1.6% in USD terms. But as the NZD took a bit of a thrashing overnight, these prices were up more than +3% in local currency terms.

MORE CAUTIOUS AFTER OIL PRICES JUMPED AGAIN
The September ANZ business confidence survey shows it little-changed but still at a high level. Overall business confidence eased 2 points although it remains positive. Expected own activity was steady at its equally positive level. Reported past activity fell however and is only at a modest level. Inflation indicators were little changed. Inflation expectations were steady at 3.25%, cost expectations were up with more than 4 in 5 expecting higher costs Pricing intentions eased with now less than half expecting to raise prices. Responses received later in the month after oil prices rose sharply again had lower activity indicators, while cost and price measures were similar or lower. More here.

EMBRACING THE OPTION
More than one million train rides have been recorded on Auckland’s rail network in the first two weeks since the City Rail Link (CRL) opened, with early data showing Aucklanders are embracing new routes and changing the way they travel across the city. The second week recorded more than 506,000 train boardings. In the two weeks prior it its opening, 645,000 train trips were recorded, so the upgrade has brought a +60% uplift. For reference, the Auckland bus network records about 3 mln trips in te same two-week timeframe. There is no data yet on shifts of patronage from the bus to the train, nor shifts from cars to the train.

SHIFTING FUNDS TO INTEREST-EARNING
Household bank balances 'normally' reduce in August from July, but this year the reduction was an outsized -$1.4 bln and about twice what it has been over the prior two August months. But household TD balances rose +$900 mln from July, with the rundown coming mainly in savings account balances (-$1 bln) and transaction account balances (-$1.3 bln).

MORTGAGE GROWTH UNREMARKABLE
The RBNZ's August loan book data delivered little surprise with the same level of year-on-year expansion we have seen over the past 15 months. However it is probably worth noting that the total mortgage book for all banks will likely exceed $400 bln when the September data is revealed next month. It rose to $398.2 bln in August, a +$1.4 bln rise from July.

OUR NET IIP LIABILITY SHRINKS NOTABLY
In March 2026 data released today, Stats NZ said New Zealand had $482.7 bln investment abroad up +14.6%: And of that about $307 bln is in portfolio investments (KiwiSaver and the like) and most of that was in the US and Australia. Our total investment in the US was up +12.6% from a year earlier, up +18.5% into Australia. But direct investment is relatively minor, only about $33 bln. In contrast, foreign investment into New Zealand was $674.4 bln, up +6.1% from a year earlier, with Australia raising their by +7.4% from a year earlier, the US raising theirs by +18.1%, but the British selling down by -3.8%. Most inbound investment is also portfolio investment (55.5%_, but direct investment is a more substantial $172 bln. The net of all this is a investment liability of -$191.7 bln which is a -10.7% lower liability than the year-ago level and the biggest fall since 2011. (IIP is the "International Investment Position".)

NZX50 FLAT
As at 3pm, the overall NZX50 index is up +0.2% so far but down -0.8% for the past 5 trading sessions. It is up +6.2% from six months ago. From a year ago it is now up +3.2%. Market heavyweight F&P Healthcare is also up +0.2% so far today. SkyCity casino, AirNZ, Precinct and Vista Group rise while the NZX, a2 Milk, Investore Property and Gentrack fall.

AUDITED IMPROVEMENT
We have previously noted Pamu/Landcorp's better operational and financial results. Today they released their formal Annual Report which you can find here. After years of losses or small surpluses, they have now recorded two consecutive years of NPATx above $100 mln; $160 mln in the latest year after $120 mln in the prior year.

UP SHARPLY AS EXPECTED
Australian inflation rose from 3.5% in July to 4.0% in August in a rise at was basically expected (4.1%) by economists, the financial markets - and presumably the RBA. Their core (trimmed mean) inflation rates was unchanged at 3.6%. Fuel costs were obviously the big mover (+5.6%), but housing costs were up 5.7%, education up 4.7% and education costs up 3.9%. So the rising cost pressures are broadening out. Food was up 3.0%.

A BIG MISS FOR A FACTORY POWERHOUSE
In something of a surprise, Korean industrial production came in sharply lower in August than anyone expected. It was expected to rise +4% as it did in July, but it actually fell -2.2%, so a notable miss.

THINGS PICK UP IN CHINA
China said both its official factory and services PMI's shifted into a small expansion in September from a modest contraction in both in August. This was a better result than was expected. In addition, the S&P Global factory PMI for China was released. It recorded a modest expansion in August, and that improved in September. The unofficial version for their services sector remained very modest however - but at least it improved as well.

SWAP RATES FALL
Wholesale swap rates will likely be much lower today on the Aussie CPI that didn't surprise and the Bullock commentary yesterday that was on the dovish side. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged at 3.24% on Tuesday. Today, the Australian 10 year bond yield is down -8 bps at 5.33% and away from the cliff-edge. The China 10 year bond rate is still at 1.67%. The Japanese 10 year bond is now at 3.09% and up +1 bp. The NZ Government 10 year bond rate is now at 5.06% and down -9 bps from this time yesterday. (The RBNZ 10 year rate is 'prior day' and was down -1 bp at 5.12% on Tuesday.) And the UST 10yr yield is now at 5.23% and down a minor -1 bp from this time yesterday.

EQUITIES MIXED & UNCERTAIN
The NZX50 is now up +0.3% from Tuesday's close. The ASX200 has opened up +0.8%. Tokyo is down -0.9%. The KOSPI is up +0.5 at its open today. Hong Kong has opened down -0.4% while Shanghai is up +0.4%. Singapore is down -0.1% in early Wednesday trade today. Wall Street ended its Tuesday trade down -0.2% with the Nasdaq down -0.1%.

OIL PRICES FALL
American oil prices have fallen -US$4 from this time yesterday with the WTI benchmark now at just over US$89.50/bbl, while the international Brent price is just over US$96.50/bbl and jerking down -US$10. The re-opening of the Saudi oil pipeline, plus the big release of US strategic reserves are behind these shifts

CARBON PRICE MARKET QUIET
There have been few significant late trades again today so far. The price is little-changed at $52/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.

GOLD FIRMS
In early Asian trade, gold  has firmed +US$44/oz from this time yesterday, now at US$4174. Silver is up +50 USc at just on US$61/oz.

NZD EASES 
The Kiwi dollar is now just over 56.4 USc and down -20 bps from this time yesterday. Against the Aussie we are up +30 bps at 81 AUc. Against the euro we are unchanged at 49.8 euro cents. This all means the TWI-5 is remains just under 60.2 and down -10 bps.

BITCOIN HOLDS
The bitcoin price is now at US$83,414 and up +0.5% from this time yesterday. Volatility has been low at just under +/- 1.0% again.

HOW THE GLOBAL ECONOMIC FORCES AFFECT US
If you want to catch up on what happened last night, try our Economy Watch podcast, here.

Daily exchange rates

Select chart tabs

Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: CoinDesk

Daily swap rates

Select chart tabs

Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA

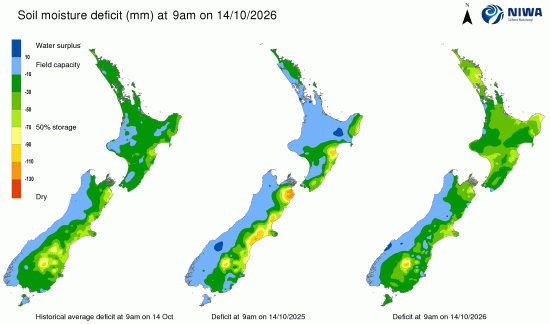
This soil moisture chart is animated here.

Keep abreast of upcoming events by following our Economic Calendar here ».

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

33 Comments

We have previously noted Pamu/Landcorp's better operational and financial results. Today they released their formal Annual Report 

Never been able to determine if Spring Sheep (the sheep milk business) has ever been profitable. 

Up
2

The AI build-out is on track to become the biggest economic bet in US history... 3.6% of GDP pa on average. 

Never before has the US economy been so dependent on the build-out of a single industry.

In terms of all the historical investments - canals, railroads, electrification, highways, telco and fiber - Japan and China have achieved better outcomes.  

https://www.wsj.com/economy/the-ai-build-out-is-becoming-the-biggest-ec…

Up
3

I wonder if US will do quite well with AI through with their hands off approach to regulation. 

I know of companies with an AI bill over 10 million a year in little old NZ, multiply that out the world over and there is some serious money to be made by someone. 

Up
0

Imagine the horror if that was a wage bill. The only way that spend works is if you are a public body wasting other people's money, or you have laid off several truck loads of staff.

Up
1

Eye watering eh. I suspect there will be cut backs. 

To be fair that's only 100 staff on 100k. But hard to see it saving that much labour. 

Up
0

Jimbo — perhaps you're both right about different parts of the equation.

There is unquestionably serious money to be made from AI, and America's relatively hands-off regulatory environment, frontier models, chips, capital markets and software ecosystem remain formidable advantages.

But Phoenix is raising a rather different question.

The WSJ estimate he cites is extraordinary - around $10.3 trillion of US AI-related infrastructure investment through 2032 - averaging 3.6% of GDP every year.

Your NZ company spending $10m annually on AI certainly demonstrates demand. But somebody receiving $10m of revenue tells us remarkably little about whether the trillions of dollars of GPUs, data centers, transmission, generation and increasingly debt-financed infrastructure sitting underneath that revenue will ultimately earn an adequate return.

One estimate now suggests the US build-out may require something approaching $3.7 trillion of annual AI revenue by 2032 to justify the capital being deployed.

Perhaps this is where Phoenix's historical comparison becomes fascinating.

America may have the more permissive regulatory environment, but China has an enormous advantage in something that cannot be solved by deregulating an algorithm - physical infrastructure and energy.

Ultimately the AI race may therefore become less about who produces the cleverest model and more about who can produce the greatest quantity of useful intelligence at the lowest all-in cost per token.

Cheap abundant electricity, grids, data centers, chips, cooling and the cost of capital all suddenly matter - that's why I think the American AI story contains an extraordinary paradox.

AI itself could be every bit as revolutionary as its advocates claim - while the $10 trillion American infrastructure bet made to deliver it could still prove to be a lousy investment.

Railways transformed civilisation too - that didn't mean everyone who financed a railway made money.

Up
1

Thanks Colin. I do get it that one NZ company is a rounding error, however there are a lot of companies in the world. 

The way I see it, 10 trillion is only about 8x the value if Tesla. And Tesla is just a company that makes average electric cars with loads of competitors. I prefer AI to that. 

Up
1

They don't 'make money'. 

Proxy is merely transferred. Meaning the people you mention locally, lost it. 

Do they get more physically productive? 

No, they won't. But they'll be forsed to join the only game in town and join the ranks of the 'being fleeced'. Because the bottom end and the middle, have already been sucked dry. 

Up
0

PDK — we've been around this particular paddock often enough, so I'll keep it brief.

“Do they get more physically productive? No.”

Of course they potentially do - that's rather the point of productivity.

A farmer using GPS-guided machinery can produce more output per labour-hour. A railway can move vastly more people and freight using the same human labour. Automation can manufacture more widgets per worker. Better logistics can move the same physical goods with less fuel, inventory and wasted time. 

And AI potentially allows a lawyer, engineer, programmer, radiologist or manufacturer to produce considerably more useful output from the same human input.

None of that abolishes thermodynamics, creates infinite resources or means AI necessarily justifies $10 trillion of investment. It simply means knowledge and technology can improve the efficiency with which finite physical resources are converted into useful output.

And that is precisely the question Jimbo, Phoenix, and I are discussing - will the productivity gain ultimately justify the capital committed to achieving it?

Repeating that money is a proxy doesn't answer that question.

Up
5

"A farmer using GPS-guided machinery can produce more output per labour-hour"....if he can access the requirements that support that system...and they all increasingly rely upon energy (mainly oil)....you continue to miss the point.

Energy blind.

Individually you can make cases for 'efficiency' however increasingly those efficiencies rely upon ever increasing energy inputs (not to mention complexity)...what is 'true' in the micro fails in the macro.


Up
2

Frank — “energy blind” seems a rather curious description of an argument that literally begins with America's AI build-out running headlong into the problem of securing enough energy to power it. :-)

Of course GPS, automation, AI and virtually every other modern productivity enhancement require energy and increasingly complex supporting systems. I haven't disputed that for a moment.

But acknowledging an energy input doesn't establish that the resulting productivity gain is illusory. The relevant question is useful output relative to the total inputs required to produce it - labour, energy, materials and capital included.

If improved technology allows a farmer to produce the same food using fewer labour-hours but twice the diesel, that's one result. If it allows the same farmer to produce more food using fewer labour-hours and less fuel per tonne of output, that's quite another.

So yes, energy absolutely belongs in the equation, but recognising the denominator isn't the same thing as knowing the answer.

Up
2

Systems thinking Colin....the system we have evolved demands growth and that growth is facilitated by energy, everything not just tech. Remove growth and the system fails. Growth requires more energy and the EROEI of energy is declining.

And the dilemma is that if we somehow acquire/convert more energy in a timely manner the waste stream (entropy) will make the environment unusable for our system (and ourselves)..a feedback loop.

Bacteria in a jar.

Up
1

NOT per labour hour - it's per diesel litre. 

Labour hasn't counted as more than noise, for years. 

Which is why 'productivity' has plateaued; it was really energy efficiencies, and they run into the 2nd Law of Thermodynamics. 

Same with AI - the energy input will likely outweigh the energy efficiencies thus gained. Plus which it will displace other energy/material demand. 

Read Taunter's Collapse of Complex Societies, then Ronald Wright's Short History of Progress. 

You have some useful things to contribute - but a ways to go... 


Up
0

PDK — I don't dispute the physical constraint for a moment. But changing the denominator from labour-hours to diesel litres doesn't abolish productivity; it merely changes what we're measuring productivity against.

You said... “the energy input will likely outweigh the energy efficiencies thus gained.”

Perhaps, but that's precisely the question under discussion. You've simply assumed the answer.

If AI consumes 100 additional units of energy but enables the wider economy to eliminate 200 units of energy and resource consumption elsewhere, that's an efficiency gain. If it consumes 200 to save 100, it's a loss. Thermodynamics establishes the physical boundaries - it doesn't supply those numbers for us.

And that was my original point. AI may be transformative, but we still have to determine whether the enormous energy, material and financial inputs justify the productive output.

Invoking the Second Law doesn't relieve us of doing the arithmetic.

Up
4

Railways transformed civilisation too - that didn't mean everyone who financed a railway made money.

Was thinking about this recently. For decades, the rule of high-speed rail seemed unbreakable. It belonged to small, rich, densely-packed nations with patient engineering cultures (Japan). Continental giants were too big, too spread out, too expensive. Geography always won. Then China built the largest, fastest, most advanced network the world has ever seen - and built most of it knowing it would never turn a profit.

On paper, it looks like a catastrophe. Hundreds of billions in debt, stations stranded in empty fields, four-fifths of the network losing money, and some of China's own experts now whispering an alarming word about what they've built. What looks like the most expensive mistake in modern infrastructure may actually be one of the most deliberate bets any country has ever made.

You can I rode it for six hours, from Hong Kong deep into the mountains of Hunan, in a lie-flat suite that will shame every train you will ever ride. Every transport ministry on Earth should be watching with a mix of envy and genuine fear. 

Up
0

Phoenix - precisely, and I think this illustrates an important distinction in what we are discussing.

China's railway investment doesn't necessarily have to produce a conventional commercial return at the railway-company level to produce an enormous return to China.

It is essentially productive national infrastructure - moving hundreds of millions of people faster, connecting labour and businesses, shrinking effective distances between cities, reducing logistics and opportunity costs, relieving other transport systems and increasing the efficiency of the productive economy. The World Bank has actually found substantial wider economic returns from China's HSR network, including productivity and agglomeration effects.

In other words, the railway can theoretically lose a dollar while enabling the wider economy to make several. That is what a public utility is supposed to do.
And IMO that brings us straight back to the AI comparison. If America spends $10 trillion on AI infrastructure, the technology may indeed generate enormous benefits for the wider economy. But if that infrastructure has been financed through private capital structures requiring commercial returns, debt servicing and investor liquidity, those benefits don't necessarily accrue to the people who financed it.

China can afford to ask whether the railway makes China more productive. Wall Street ultimately has to ask whether the investment makes money - two very different questions.

SUB-EDIT: Actually Phoenix, thinking further about your railway example, I think you've actually illustrated the point beautifully. The fact that China's railway can transform the productive economy without requiring every line to satisfy Wall Street's definition of profitability isn't the paradox - it's the whole point. The public utility itself can be the return when it raises the productive efficiency of the entire economy.

Up
1

It is essentially productive national infrastructure - moving hundreds of millions of people faster, connecting labour and businesses, shrinking effective distances between cities, reducing logistics and opportunity costs, relieving other transport systems and increasing the efficiency of the productive economy.

Bingo. 

BTW, interesting fact: rail accounts for a very small share of Japan’s domestic freight - roughly 5% by tonne-kilometres (the standard measure of freight movement: tonnes carried × distance travelled).

https://www.stat.go.jp/english/data/handbook/pdf/2026half_2.pdf

Up
0

“Perhaps this is where Phoenix’s historical comparison becomes fascinating.” Didn’t need to say perhaps. Explanation and analysis much appreciated. 

Up
0

He absolutely gets that it is the whole, regardless of the parts. 

But when the whole is asked to maintain more and more built infrastructure, using resources and energy of less and less quality, it's a less than zero sum game. 

In the full picture, AI can't claw back 40 trillion. And in the real world, every resource is being depleted, every day. AI can't reverse that, either. In my physics/engineer circles, there's a corny old joke about putting 100 economists in a room but they won't be able to construct a ham sandwich. 


Up
0

Well once upon a time there was a world where energy was courtesy of wind and gravity and the strength of mammals, human and otherwise. . Wasn’t much else except for gun powder and emissions from neither that nor the steam from a cooking vessel were harnessed. People undoubtedly could out of necessity adapt to surviving again as such but the destruction and devastation causing it to revert to that situation globally would just as undoubtedly, overwhelm that likelihood. No wonder that small tribe, still more or less Stone Age so to speak,  on North Sentinel Island off the coast of Malaysia don’t ever let anyone come ashore and live.

Up
1

If you have used Claude Opus 5.5, compelling performance for the price.   If only we could get this into the right, and capable hands in public service to resolve real issues.

Up
1

Would need a decent NZ data centre for that, unless we trust Trumpleton 

Up
0

I wrote a missive about the steps on the housing ladder being to far apart in Auckland a few weeks back.... now I start to see the same opinion in print.

https://www.stuff.co.nz/home-property/361039978/16m-homes-nobody-wants-awkward-property-mismatch-keeping-boomer-home-sellers-stuck

The upsizers have backed off (ITGuy edit... because they cannot afford the step)

Adding to the picture are existing home owners who might have moved up the ladder but are increasingly not doing so.

“Yes, those movers have backed off more than any other group,” says Cotality Head of Research Nick Goodall. “More people are holding tight with the job market being a bit weak, cost of living concerns, just more people don’t have the confidence to make the move right now.”

Movers made up around 25% of sales across the past year, just over 23,000 sales.

But that category includes both upsizers and downsizers, so those shifting up to bigger home is likely a much smaller group than that.

People who bought at the peak of the market and are now in negative equity are part of the picture too: some would-be movers now can’t afford to, because their home is worth less than they paid for it.

‘A chain reaction downwards’

East Auckland developer Barry Walker, director of Walker Homes, is seeing the difficulty selling among his older buyers.

He sells around 60% of the company’s new homes to downsizers.

"We're certainly getting downsizers coming to us and they're selling up what should be a $1.5 million dollar home, then they end up having to take $1.25 - $1.35 million, so then they want to buy our home for $1.1 million. So it's a chain reaction downwards. But we can't quite build it for that, so it's not sustainable at the moment."

Up
3

Comments section was golden on that one

Up
2

must read

two legs bad , two ticks worse.... sorry to bastardise a good animal farm quote..

Elections NZ describes the phenomenon explicitly on its website. It is totally legal and fair game for Te Pāti Māori to ask for electorate votes while encouraging party votes to go to Greens or Labour. And it is totally fine for the centre-right to use the mechanism too.

https://substack.com/home/post/p-217938952

Should the centre-right split their vote?

Is the overhang a lifeline for the centre-right?

In any case, those details are distraction. National are in all likelihood going to lose Willis, Bishop, Goldsmith, and Brownlee. A massive loss of experience and institutional knowledge, no doubt. But it is reprehensible to send centre-right voters on a fool’s errand to save them and so all but guarantee that the coalition ends up in Opposition.

New Zealanders who want the centre-right coalition back in, or at least want to keep Labour/Greens/Te Pāti Māori/Opportunity out, deserve better than to be gaslit into thinking that it is realistic that National will achieve such a massive turn around against the trends.

There is a lifeline to reach for and the opportunity to potentially save National from themselves. The centre-right can split our vote.

Up
2

"Winning isn't everything; it's the only thing" Red Sanders 1950

"If one National party vote in nine moved to a coalition partner, the Government would gain a parliamentary majority even if the opposition wins more votes in total."

https://www.interest.co.nz/public-policy/140133/those-planning-rort-mmp-should-bear-mind-two-can-play-game#comments

https://www.nzinitiative.org.nz/reports-and-media/reports/unravelling-mmp-how-the-2026-election-could-break-the-voting-system-from-two-sides


Up
2

In my house we are going to split the party vote between NZF and Act to lesson the power of either over the base Nat block.   Locally our National candidate will easily win.     Luxon you are an idiot, and I cannot wait for Willis to be canned.


Up
4

Likewise I find it impossible to vote for a party that could rush an entirely unversed and unsuitable candidate into a prime ministership and what’s more, when that ineptitude has become so glaringly obvious, cling on to him like blind mice. As for the MoF somehow I can’t stop visualising poor old Charlie Brown’s nemesis, she who snatches away the football, leaving him to kick nothing but air.


Up
2

She'll go from Nicky-no-boats to Nicky-no-votes in no time. 

Up
0

Gold Is Being Sold - And That May Be the Most Bullish Signal of All

I was doing some work on this subject today, when I stumbled across something Rob Kientz said - he is an analyst I respect, and he put his finger firmly on another piece of the puzzle.

This relates to the huge Japanese carry trade, and the much larger web of leveraged cross-border trades built around artificially cheap money, that are beginning to reverse. And, of course, when leverage reverses, investors don't necessarily sell what they want to sell - they sell what they can sell - that distinction is huge,

For decades Japan supplied extraordinarily cheap funding to the global financial casino. Borrow yen cheaply, convert it into dollars, and buy Treasuries, corporate bonds, equities, derivatives, or whatever other asset offered a sufficiently attractive spread to float your boat. 

Multiply that across hedge funds, banks, institutions and increasingly complex derivatives and you create an enormous cross-border financial structure dependent upon one rather important assumption - the cheap money staying cheap... but it isn't anymore.

Japanese yields have risen dramatically and the Bank of Japan is flat-out normalising policy. The result is precisely the sort of reversal Kientz describes - positions being unwound, capital being repatriated and liquid assets being sold as leveraged players scramble for cash.

And that helps explain what I believe is becoming a genuine earthquake beneath the global fixed-income market - which is where gold becomes particularly interesting.

During a genuine liquidity event, gold can initially fall for exactly the same reason it fell during previous financial crises. Not because gold has suddenly become less desirable, but because it is one of the deepest and most liquid assets on the planet - gold becomes the ATM.

Margin calls don't care about your long-term monetary thesis. If somebody needs cash immediately, they sell whatever has a bid - which to my way of thinking, makes gold's present resilience extraordinary.

Gold has recently been absorbing a stronger dollar, rapidly rising sovereign yields, tighter liquidity, deleveraging and the potential liquidation of carry-trade positions - precisely the cocktail that conventional financial theory says should be hammering it. Yet it remains around the US$4,000-plus level and has repeatedly absorbed substantial selling pressure.

That suggests to me something hugely important may be happening beneath the surface.

The leveraged financial system may be selling gold for liquidity while another class of buyer - central banks, sovereign institutions and investors increasingly distrustful of sovereign debt - are buying gold precisely because of the instability causing that liquidation.

One side needs cash. The other side wants out of somebody else's liability - and therein lies the delicious irony - the very same unwinding of the global debt-and-leverage machine, that can temporarily create huge selling pressure in gold, may ultimately strengthen the monetary case for owning it.

Treasuries contain counterparty and sovereign risk. Corporate bonds contain credit risk. Bank deposits contain banking-system risk. Derivatives contain counterparty risk - physical gold contains none of them.

So I would be very carefulabout interpreting a gold sell-off during this process as evidence that the gold thesis is failing - it may be evidence that the financial architecture around it is failing.

And if gold can absorb this sort of forced liquidation while the world's supposedly safest sovereign bonds are experiencing what Kientz aptly describes as an earthquake, perhaps the really interesting question is why the hell hasn't it fallen much harder?

Up
2

I 100% agree, and as the full impact of the crisis occurs XAUNZD should rise due to both side of the cross

https://youtu.be/QXEUKKw2zGk

TLDW

The global debt crisis is currently accelerating as Treasury yields reach their highest levels since 2004 (0:59), signaling deeper concerns about the sustainability of the current monetary system. Despite mainstream narratives suggesting that rising yields reflect economic strength, the speaker argues they actually indicate a loss of confidence in the government's ability to repay debt (3:03-4:40).

Key takeaways from the discussion:

  • Rising Interest Burden: The U.S. is now spending over $1.25 trillion annually on net interest (1:50-2:45), making it one of the largest items in the federal budget, rivaling Social Security.
  • Global Debt Rollover: With $365 trillion in global debt (6:28), countries face a critical rollover problem where new debt must be issued at higher interest rates, putting systemic pressure on the entire financial landscape (6:38-7:45).
  • The Path to Default: Governments have three primary ways to handle unsustainable debt: growth (which is not happening), formal default, or the most likely path—inflation (10:31-11:26). Inflation acts as a "stealth default," devaluing the currency and effectively paying back lenders with money of lesser worth (12:00-12:58).
  • The Case for Precious Metals: While gold prices may experience short-term volatility, the long-term thesis for physical gold and silver remains strong (14:20-16:44). The speaker emphasizes that unlike bank deposits or paper assets, physical metals have no counterparty risk and provide a necessary hedge against systemic collapses in trust (16:44-17:20).
Up
2

Juice media crosses the Tassie

https://www.youtube.com/shorts/bRP1kw3EG7U

Up
0

Putting the N back in cuts. 

Up
0