Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to note today. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
We have added Welcome's term PIE rates to our Term PIE table page. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
LESS IN COMMISSION
Real estate agency commission levels are sliding as the housing market flounders. Total estimated real estate sales commissions fell -9% year-on-year in the September quarter, and are well down from the peaks of a few years ago.
TRANSPARENCY HAS AGENTS & SELLERS SQUIRMING
Many real estate professional agents are watching the new Victoria state law introduced this month to battle rampant underquoting there that had many potential buyers wasting time and energy chasing properties they could never afford - just so an auction buzz could be generated. Their new law requires property vendors to publicly disclose their auction reserve price at least seven days before an auction or the end of a fixed-date sale campaign. The local real estate industry claims the intention is good, but they don't like the details.
SOME MODEST INCREASES, SOME BIG INCREASES, NO DECREASES
Fuel, electricity & gas prices jumped in the September year, but not as much as onion prices. Petrol and diesel prices continue to rise month-on-month while onions record largest annual increase since 2008, Statistics New Zealand says. Overall food prices were up +2.4% from a year ago but were unchanged from August. Diesel is up +7.8% from August, up +55% from a year ago. Rents are virtually unchanged from both the prior month and a year ago. We should note that the Q3-2026 CPI data will be released on Thursday, October 22, and analysts expect it to come in at 3.7%, down from Q2-2026's 4.1%. However, BNZ says this will be just a "head fake" before a higher level in Q4-2026.
RETAILING & HOSPO IN A VISE
Retail sales as tracked by electronic card transactions fell in September from August with total retail sales up just +0.9% from a year ago - before adjusting for inflation. That is a real decline in the volume of retail trade. And that is after fuel sales were up +11.1%. It is both the apparel and hospitality sectors who are bearing the brunt of the pullback, with higher fuel costs sucking the life out of their sectors.
AVAILABILITY SITUATION
MBIE's fuel monitoring shows no signs the availability of petrol, diesel or aviation fuel is constrained. But clearly to keep supplies flowing, we are paying a high price.
TIGHT, BUT NOT TIPPED OVER
Personal bankruptcies and No Asset Procedure filings at the Insolvency agency are not really rising. If there are stress signs in such data, it is in the rise of company failures.
SOLAR IN SPOTLIGHT FOR THE WRONG REASONS
The Utilities Disputes tribunal is pointing out that Solar complaints to them have increased fourteenfold in just four years, from 58 in 2022-23 to a projected 829 this year. Solar, while still a minor electricity provider here, now makes up more than 5% of all electricity complaints and half of all complaints accepted for formal investigation.
WEAK CONFIDENCE & RISING COSTS STUNTS LOAN GROWTH
The RBNZ's survey of bankers for their Credit Conditions survey shows residential mortgage and consumer demand decreased over the past six months. Subdued housing conditions, weak confidence and rising borrowing costs weighed on demand, although refinancing remained an important source of mortgage activity. Demand increased for large corporates and agriculture, supported by infrastructure and energy investment and stronger farm activity. Commercial property demand was broadly unchanged, while SME demand decreased. Property investment demand increased, but development demand decreased.
NZX50 RETREATS
As at 3pm, the overall NZX50 index is down -0.6% today. From a week ago it is little-changed; from six months ago it is up +5.2%. From a year ago it is up +3.4% now. Market heavyweight F&P Healthcare is down -0.8% so far today. SkyCity casino, Gentrack, Oceania and Mainfreight gain while Genesis, Contact, Chorus and Kiwi Property decline.
ANOTHER BIG KAURI
The Inter-American Development Bank (IDB) has raised $300 mln in a NZD kauri bond, yielding 4.786% pa.
PROFITING FROM GEOPOLITICAL TRADE RESTRICTIONS
Singaporean (non-oil) exports surged a massive +25% in September from August to be +68% higher than year-ago levels which themselves were already elevated and up +21% at that time. They rose from S$61.5 bln in September 2025 to S$93.2 bln in September 2026 on the back of electronics and machinery. A big destination was "Hong Kong", so a back-door for AI gear into China. Meanwhile their imports rose +48% from a year ago.
AUSSIE HOME BUILDING SLOWS SHARPLY
In Australia, their home building industry is reporting that new home sales fell by -17.5% in the September quarter 2026, reversing the recovery that commenced in 2025. New home sales are now at their lowest quarterly level in 18 months. All states recorded a decline in the latest September quarter. The largest decline was in Queensland (-26%), followed by Victoria (-23%), New South Wales (-17%), South Australia (-7.6%) and Western Australia (-1.7%). They blame rising interest rates, tax changes, and general economic uncertainty.
SWAP RATES HOLD
Wholesale swap rates will likely be little-changed again today. (We misread the signals yesterday which were negative in the bond market and which have reverted today. But yesterday there was actually little-change to swap rates.). Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged again at 3.23% on Thursday. Today, the Australian 10 year bond yield is up +2 bps at 5.25%. The China 10 year bond rate is now at 1.65% and up +1 bp. The Japanese 10 year bond is now at 2.95% and up +2 bps. The NZ Government 10 year bond rate is now at 5.01% and up +4 bps from yesterday. (The RBNZ 10 year rate is 'prior day' and was down -3 bps at 4.94% on Thursday.) And the UST 10yr yield is now at 5.09% and down -1 bp from yesterday at this time.
EQUITIES RECOVER SOME, EXCEPT THE NZX
The NZX50 has softened another -0.6% so far today, the only market we follow that is not rebounding. But the ASX200 has opened up +0.8%. And Tokyo is rebounding +1.5%. The KOSPI has recovered +2.5% at its open. Hong Kong is up +0.8% in early Friday trade while Shanghai up +0.6%. Singapore is up +0.4% in early Friday trade. Wall Street closed slightly firmer, up +0.3% on the S&P500, up only +0.1% on the Nasdaq.
OIL RISING AGAIN
American oil prices have risen sharply again, up +US$3.50 from yesterday with the WTI benchmark now at just over US$97.50/bbl, while the international Brent price is just over US$105.50/bbl and up +US$1.
CARBON PRICE HOLDS
There have been some small trades but the price is little-changed, now at $50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD HOLDS
In early Asian trade, gold has held firm, up +US$10/oz from yesterday, now at US$4156/oz. Silver is up +US$1 at US$57/oz.
NZD FIRMER
The Kiwi dollar is up +20 bps at just on 56.3 USc from where we were yesterday. Against the Aussie we are up +60 bps at just over 81.3 AUc. Against the euro we are up +10 bps at 50.2 euro cents. This all means the TWI-5 is is now just under 60.2 and up +30 bps.
BITCOIN FIRMS
The bitcoin price is now at US$82,022 and up +0.7% from yesterday at this time. Volatility has been modest at just over +/- 1.7%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
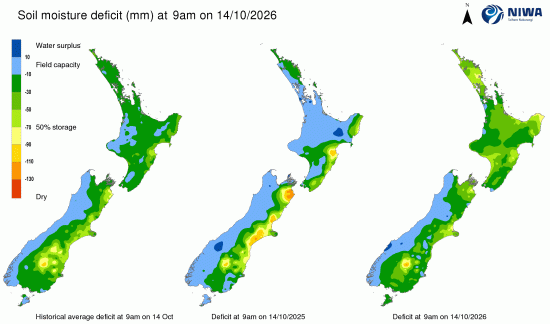
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.