
Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to note so far today yet. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
None here either. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
BETTER TIMES AHEAD
The volume of new homes being built in Auckland should steadily increase over the next two years aa a down-trend ends and the rising building consents get started and built. This conclusion is drawn from analysis of the Auckland residential consent data, and the Auckland Council's Code Compliance Certificates from completed builds.
UNUSUAL NET INTEREST INCOME FALL
Westpac NZ annual profit fell with income down, expenses and loan impairments up as the bank faces 'intense competition' for home loans.
GOING LONG
The LGFA has issued a €41 mln ($82 mln), 20-year bond through a private placement, their longest-dated bond so far and their first foreign-currency private placement. These proceeds are fully hedged back into New Zealand dollars. It yields 4.143% pa. Establishing a longer dated funding point creates the opportunity to offer longer term loans to their council, CCO and water CCO members, beyond the current longest loan maturity of April 2037.
NZX50 DROPS HARD
As at 3pm, the overall NZX50 index was down -1.2% today in a rather significant drop in investor sentiment. From a week ago it is now down -0.3%. From six months ago it is up +7.4%. From a year ago it is up +2.3% now. Market heavyweight F&P Healthcare is down a very sharp -4.5% so far today and leading the retreat. There are 50 decliners, followed by Briscoes, Gentrack, Meridian and Stride. There are 31 gainers today, led by Kathmandu surging, then EBOS, Oceania, the Warehouse, and Vista.
BETTER & BIGGEST
Bolstered by a significant improvement in milk composition, the latest Dairy Statistics 2025/26 report, shows the sector produced 2.02 billion kilograms of milksolids, up +4.5% on the previous season, from 21.8 billion litres of milk, up +3.5%.
UP +50%, MORE RECENTLY
From March to October, weekly turnover in secondary markets for NZ Government bonds averaged just less than $80 bln (per week), up from an average of $65 bln in the prior 7 months. In the same March to October period in 2025 the average was $54 bln/week. In the last week of October $81.5 bln was traded.
RISING INFLATION ACROSS THE DITCH
In Australia, the respected Melbourne Institute inflation gauge for September pegged it at 4.8% and a third consecutive monthly rise. This will lock in the +25 bps RBA rate rise tomorrow, taking it to 4.85%.
SAVED BY MULTI-UNIT DEVELOPERS
In Australia there has been a surge in multi-unit residential building consents in September, more than making up for a sharpish fall in consents to build new houses, and allowing the overall level to rise +5.3% from August. That means, September building consents were -0.8% below year-ago levels.
BETTER THAN THE NEGATIVE OFFICIAL VERSION
Unlike the official versions of their factory PMI which recorded a contraction, the private S&P Global (RD) factory PMI in China for October held a modest expansion. They reported a rise in new orders and a rise in output. Some went into stock-building however. Encouragingly, these was an easing in cost and price pressures.
ASEAN EXPANSION ROLLS ON
And there were a number of other factory PMIs out in Asia today. After the weekend one from Japan which revealed a good expansion even if less than in September, South Korea posted much softer but still positive expansion, Taiwan maintained it very good expansion (the best of the region), as did Malaysia. Vietnam's expansion was a bit more modest, but Indonesia found some wind for its sails delivering an expansion that matched Malaysia and Taiwan.
SWAP RATES HOLD
Wholesale swap rates will likely be little-changed today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged at 3.16% on Friday. Today, the Australian 10 year bond yield is up +2 bps at 5.15%. The China 10 year bond rate is now at 1.61% and up +1 bp. The Japanese 10 year bond is little-changed at 2.77%. The NZ Government 10 year bond rate is now at 4.94% and up +10 bps from this morning and recovering more of the post-OCR drop[. (The RBNZ 10 year rate is 'prior day' and was up +3 bps at 4.90% on Friday.) And the UST 10yr yield is now at 4.93% and little-changed from this morning's open.
EQUITIES MIXED
The NZX50 has fallen -1.0% so far today. The ASX200 has opened down -0.6%. Tokyo is down -0.6% from Friday. The KOSPI has risen +1.7% at its open. Hong Kong is up +0.4% in early Monday trade while Shanghai is up +0.5%. Singapore is down a sharp -1.3% in early Monday trade. Wall Street futures suggest the S&P500 will open tomorrow up +0.9% and the Nasdaq futures point to an opening rise of +1.3%.
OIL PULLS BACK
American oil prices have eased from this morning with the WTI benchmark now at just over US$101/bbl and down -US$3, while the international Brent price is also lower by -US$3 just under US$110.50/bbl.
CARBON PRICE LOW & STABLE
There has been very little trading reported today and the price is still at $48/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD STOPS FALLING
In early Asian trade, gold has risen +US$35 from this morning, now at US$3911/oz and back to Thursday's level. Silver is up +US$1 at just under US$50/oz.
NZD SOFT
The Kiwi dollar is down -10 bps from this morning at just under 56.2 USc. Against the Aussie we down -10 bps at just under 80 AUc. Against the euro we are down -10 bps at 50.3 euro cents. This all means the TWI-5 is now just under 59.9 and down -10 bps.
BITCOIN RECOVERS SLIGHTLY
The bitcoin price is now at US$78,386 and up +2.4% from Saturday when the Binance hack story was developing. Volatility has remained low at just under +/- 0.6%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
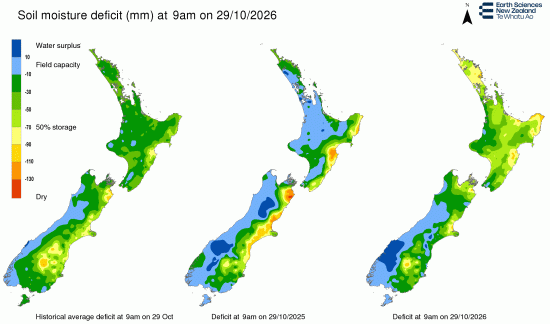
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.