Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to record today. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
No changes to here either. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
SELLERS TO FACE A GRIM REALITY
The housing market stumbled in October as sales slumped and prices stagnated The REINZ October housing market data shows -24% drop in annual nationwide sales volumes with Auckland down -30%. Fewer and fewer buyers are willing to pay current asking prices. If this reluctance keeps up, sellers are in for a very rugged realisation.
FACTORIES EXPANDING POSITIVELY
Improved activity in the manufacturing sector is becoming increasingly well established, as indicated by the October Performance of Manufacturing Index (PMI). Although it eased very slightly from September its remained comfortably in a sustained sustained expansion. Momentum in manufacturing is firmly positive.
EASING
The latest MBIE update of the 'fuel supply situation' shows all current levels better-than-average since when we started tracking these risks at the start of the 'crisis in March. This is true for petrol, diesel and aviation fuels. Even tanker freight rates are declining now.
NZX50 ENDS WEEK WEAK
As at 3pm, the overall NZX50 index was down -0.9% today. From a week ago it is now up +0.9%. From six months ago it is up +8.2%. From a year ago it is up +3.9% now. Market heavyweight F&P Healthcare little-changed so far today. There have been 22 gainers led by Lodestone Energy, Vista Group, The Warehouse, and Oceania. There have been 47 decliners led by Gentraxk, Fletcher, EBOS and Spark.
FLUSH
If banks have troubles lending the funding they have, they can always park these excess funds in their RBNZ Settlement Account. You will remember these during the pandemic when the total of bank settlement accounts reached a peak of $56 bln. The great thing for banks is that these pay the OCR interest rate - which got as high as 5.75% at one point. But since December 2022 these settlement account balances have fallen steadily, down to 'only' $23 bln in August 2026 (earning 2.25% pa). But since then, the funds in these accounts at the RBNZ have risen to $28.8 bln a notable and unseasonable rise. Does this indicate banks are not finding borrowers for some of their liquidity?
NEW OWNERS BEING LINED UP
Australian media is speculating that Northleaf Partners, a Canadian infrastructure investor that now owns the ex-One.NZ cell-phone tower infrastructure here, has bid to buy the Aussie-owned StraitNZ inter island shipping company.
ANOTHER RAISES HIS CONCERN
In New York in a panel discussion, the New York Fed's boss John Williams added heft to the growing comments by Fed speakers that rate hike action is on the way. He said “inflation is far too high and it continues to be high even in the latest data.” Fed speaker comments are more important now that Fed boss Warsh has withdrawn from most commenting.
SWAP RATES FIRMER
Wholesale swap rates have probably turned back up today on global shifts, maybe by as much at +6 bps. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was up +1 bps at 3.19% on Thursday. Today, the Australian 10 year bond yield is up +8 bps at 5.12% from this this time yesterday. The China 10 year bond rate is now at just over 1.58% and down -1 bp. The Japanese 10 year bond is up +11 bps at 2.87%. The NZ Government 10 year bond rate is now at 4.84% and up +8 bps from yesterday at this time. (The RBNZ 10 year rate is 'prior day' and was down -4 bps at 4.73% on Thursday.) And the UST 10yr yield is now at just on 5.13% and up +14 bps from this time yesterday in a notable move higher.
EQUITIES MIXED
The NZX50 has fallen -0.7% so far today. And the ASX200 has opened down -0.6%. Tokyo is up +1.7%. The KOSPI is up +2.1% at its open. Hong Kong is down -0.6% in early Friday trade while Shanghai is up +0.3%. Singapore is down -1.0% in early Friday trade. Wall Street was lower in Thursday trade with the S&P50 ending down -0.4% and the Nasdaq also fell -0.4%.
OIL PRICE TURNS HIGHER
American oil prices have risen, up +US$2 from yesterday at this time with the WTI benchmark now at just on US$88/bbl, while the international Brent price is up +US$3 at just on US$95/bbl.
CARBON PRICE DIPS
There have been few trades reported today so far, and the price is down -50c at $49.50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD SOFT
In early Asian trade, gold has retreated another -US$73 from this time yesterday, now at US$3911/oz. Silver is down -US$1 at just under US$50.50/oz.
NZD DIPS
The Kiwi dollar is down -20 bps from yesterday at just on 55.5 USc. Against the Aussie we up +10 bps at just on 81.4 AUc. Against the euro we are down -10 bps at 50.1 euro cents. This all means the TWI-5 is now just over 59.6 and down -10 bps from this morning.
BITCOIN DROPS
The bitcoin price is now at US$70,845 and down -3.8% from this time yesterday. Volatility has been moderate at just on +/- 2.2%.
COMISERATIONS
If you use Microsoft products via subscription you are probably quite frustrated today and it may drag on a while yet as the company grapples with serious infrastructure problems. The interconnected world we live in now is risky, the more so the more concentrated the tech industry becomes. What we thought was a decentralised world is in fact worryingly centralised, and by companies structured beyond our regulators and beyond accountability.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
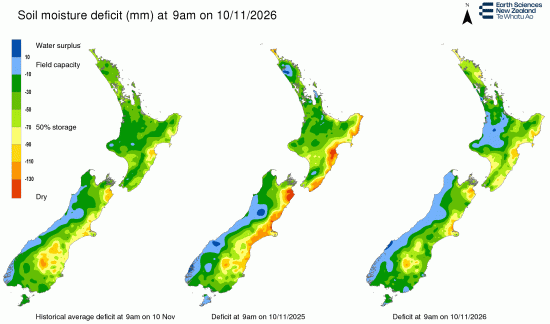
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.