
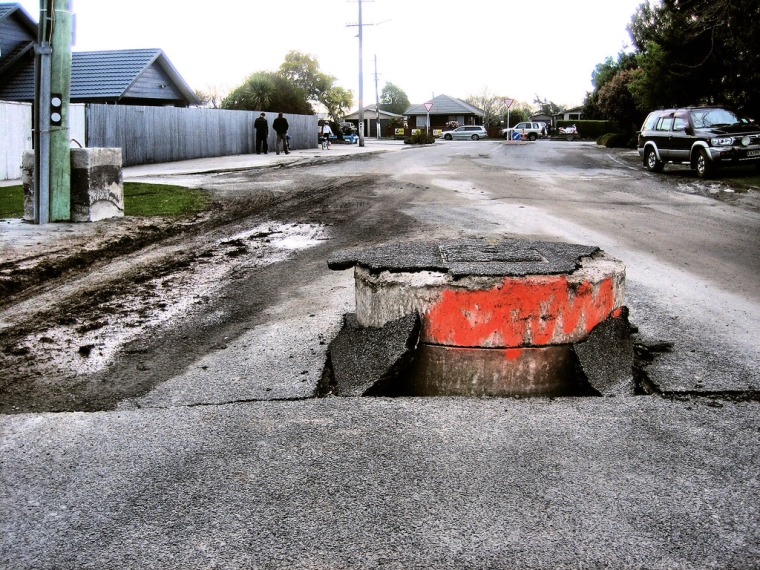
A seismic amount of risk is being transferred from private insurers to the public purse, as the Government decides to double the amount of cover the Earthquake Commission (EQC) will provide homeowners in the event of a natural disaster.
It is doubling the EQC building cap to $300,000 (plus GST), meaning the state insurer will cover the first $300,000 of building damage, leaving residential property owners’ private insurers to cover the remainder.
The cap was only increased in 2019 to $150,000 (from $100,000).
The cover is provided for earthquakes, tsunamis, volcanic eruptions, hydrothermal activity and natural slips.
Because EQC is taking on more risk, it will hike premiums from the current maximum of $345 to $552 per dwelling per year. Private insurers collect these premiums on behalf of EQC by tacking them onto the premiums they charge for fire cover.
The change will see private insurers reduce their exposure to risk, so they should reduce their premiums. Although the Government isn’t forcing them to do so.
Minister Responsible for the Earthquake Commission David Clark said, “Insurance premiums charged in different regions will be monitored. If insurer pricing doesn’t behave as expected, the Government is open to considering options such as a competition study to give consumers assurance the market is competitive.”
Clark believed the change would make insurance more affordable.
“We are providing more natural disaster cover for homeowners, ensuring their private insurance cover remains available and affordable,” he said.
“In recent years insurers have moved to a risk-based pricing for earthquakes, making the cost of insurance more expensive for homeowners in areas like Wellington, Hawke’s Bay and Canterbury. Increasing the EQC cap should lead to reduced premiums for many New Zealanders as the Crown absorbs some liability and risk from private insurers.”
From October 1, 2022 all new insurance contracts/policies for fire insurance will include the higher building cap as they come up for renewal. It will take 12 months for all policies to be renewed and the new level of cap to apply for all households.
Here’s a Q+A from Clark’s office:
What is the EQC cap?
The EQC building cap is the maximum amount of residential building insurance available from EQC in the event of a natural disaster covered by the EQC Scheme. This includes an earthquake, tsunami or volcano. The cap applies per dwelling, so multi-dwelling buildings have multiple caps. Any building cover above the EQC cap is provided by the home owner’s private insurer.
Why increase the cap to $300,000?
A building cap of $300,000 (plus GST) should keep insurance premiums at an affordable level for homeowners, especially people in regions assessed as having a higher risk of a natural disaster event occurring. The Government, through EQC, is providing more natural disaster cover for homeowners, which should ensure homeowners’ private insurance cover remains available and affordable.
What is the Government trying to achieve?
The EQC cap is set by the Government, through regulations, or legislation. When considering the level of the cap, Minister Clark had the following objectives:
- New Zealanders can access affordable residential property insurance, to ensure as many people as possible can repair their homes if they are damaged by a natural disaster.
- Sufficient funds are available to repair/rebuild residential property following a natural disaster, which minimises fiscal risks to the Crown.
- There is a robust and competitive private insurance market.
- Insurance price is used to signal risk.
- New Zealand continues to be able to purchase cost-effective reinsurance.
A cap of $300,000 for natural hazard insurance still leaves room for the private insurance market to provide cover, including retaining risk-based pricing signals.
How will this affect insurance premiums?
EQC provides the first level of cover for residential homes in the event of a natural disaster, with private insurers providing “top up” cover up to the value of a property’s sum insured.
Increasing the level of cover provided by EQC reduces the amount of top up cover required from private insurers.
An increase in EQC cover reduces the cover (and therefore cost) insurers need to provide and their cost of providing this insurance. It’s expected these changes will flow through to the premium homeowners need to pay.
An increase to the EQC cap will require an increase to the EQC premium, from the current maximum of $345 to $552 (an increase of $207 a year per dwelling). The actual EQC levy amount paid by a homeowner will depend on their sum insured.
By increasing the cap, the Government through EQC, is taking on a greater proportion of the financial cost of helping New Zealanders when their homes are damaged by covered natural disasters. The Government expects insurers to reflect this in their pricing for insurance cover purchased by New Zealanders after October 2022.
As the value of sum-insured policies have increased in response to reflect residential repair and construction costs, the portion of insurance provided by risk based private insurance policies has also increased, compared to the community-rated EQC premium.
What if insurers do not pass on cost savings?
The final total insurance premium paid by households depends on the extent insurers reflect the reduced amount of risk private insurers will now cover.
Insurance premiums charged in different regions will be monitored. If insurer pricing doesn’t behave as expected, the Government is open to considering options such as a competition study to give consumers assurance the market is competitive.
Why make this change now?
Since receiving the report from the Public Inquiry into EQC, the Government has been working on modernising the EQC Act. A Bill is expected to be introduced into Parliament early in 2022.
This work has included a review of the EQC cap.
Insurers have asked for a reasonable lead in time to prepare for the new cap. I am announcing the cap separately from other changes to the EQC Act to give insurers time to prepare.
I expect to announce the other changes to the EQC Act in the next few months.
What does the new cap mean for the insurance response model EQC has agreed with insurers?
EQC has partnered with a range of New Zealand’s private insurers to manage claims for natural disaster insurance cover on behalf of EQC.
Insurers will continue to manage the EQC portion of claims on EQC’s behalf.
Homeowners should contact their insurer directly if their property is damaged as a result of a natural hazard event.
For further information on the Natural Disaster Response Model see here: https://www.eqc.govt.nz/get-help-now-claims/ndrm2021
How will this change impact EQC’s reinsurance and the Government guarantee of EQC?
Both EQC and private insurers will need to factor in the change to the EQC cap as part of their decisions on the amount of reinsurance cover they purchase. Making this announcement now gives all affected insurers, including EQC, time to make any necessary adjustments to ensure a smooth transition.
There is no change to the underlying government guarantee of EQC. This is a statutory obligation on the government and remains unaffected by the change to the EQC cap.
Background to the cap
New Zealanders know a number of natural disaster perils, such as earthquakes, might impact their lives. Homeowners purchase residential property insurance so if a natural disaster event happens, they are able to repair or rebuild their homes and move on with their lives. Affordable disaster insurance means more people will buy insurance, speeding recovery for the whole community.
Everyone in New Zealand pays the same EQC premium rate, regardless of underlying risks, or region they are located. This is called community rating. Increasing the EQC cap can smooth regional differences in insurance prices resulting from natural hazard risk.
In recent years, insurers have priced disaster risk more granularly as the availability of detailed risk modelling allows insurers to introduce more granular risk-based pricing. This means homeowners in high-risk locations such as Wellington, Christchurch and Hawke’s Bay, have had significant premium increases per year, particularly for some high-risk, high-value properties and apartments.
Significant and unpredictable price increases can have a material impact on homeowners’ wellbeing and financial resilience, affecting their willingness and ability to purchase insurance.
The Government wants to encourage people to continue buying insurance cover and is stepping in before increased prices result in declining rates of insurance uptake by homeowners. By increasing the level of risk the government covers through EQC, we expect private insurance premiums for high-risk areas to be lower than they otherwise would have.
The government is committed to everyone in New Zealand paying the same EQC premium rate, regardless of underlying risks, or region they are located. This is called community rating. Increasing the EQC cap can smooth regional differences in insurance prices resulting from natural hazard risk.
The EQC Cap - History
The EQC residential building cap was originally set at $100,000 plus GST effective at the beginning of 1994. This was roughly the cost of building a basic house at that time.
The cap was increased to $150,000 (plus GST) from 1 July 2019.
The Public Inquiry into EQC suggested the cap could be increased to recognise the average cost of building a residential property in New Zealand (excluding the cost of the land on which it is built) has increased since then. In 2020 the Public Inquiry estimated the average cost of building, to be closer to $400,000.
What perils are covered by EQCover?
EQC building cover insures you against loss or damage from:
- an earthquake
- a natural landslip
- a volcanic eruption
- hydrothermal activity
- a tsunami
- and, fire following all of the perils listed above.
EQCover also provides insurance cover for land damage from each of the list perils including land damage from storm and flooding events.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.