
Here's a special holiday update of some key events and data you may want to know about today.
First up, the number of Americans filing for jobless benefits unexpectedly fell last week. At the same time, a closely watched survey of consumer sentiment moved higher mainly through continued optimism over household finances. All this suggests the sharp slowdown in job growth in March may well have been an aberration.
The US Administration has reversed itself and now decided not to declare China a currency manipulator. Instead it will 'ask'(remind) the IMF of its role in this area. It has reversed position on export guarantees as well, deciding to keep the American EXIM Bank. (And the President has signaled he will likely keep Janet Yellen as the Fed chair, also reversing an earlier stance.)
The OECD has released a review today that suggests that employment is growing in the 35-group nations, pushed up in equal measure by falling unemployment rates and rising participation rates. It turns out employment rates now are higher that before the GFC.
In Australia, their small business ombudsman has been investigating the behaviour of large corporates around how they pay their small suppliers. They found an abusive, unfair system where the large are taking advantage of the small. In fact, Australian corporates apparently pay their small suppliers 26.4 days after the due date, on average. That was the worst of the nineteen countries surveyed (New Zealand was not included.) Their ombudsman says the situation is so serious, it calls for legislation to force change.
And staying in Australia, their central bank issued its latest update of its financial stability assessment yesterday. The general conclusion is that the financial system is in good condition. Indeed the Reserve Bank says that banks have actually become more resilient and able to deal with challenges. Their main concern is the lift in mortgage debt and slower growth of household incomes. If unemployment were to rise and/or interest rates were to lift markedly, that would create challenges for some families who basically have not built up any buffers for a bumpy ride. But it is just a risk at present – interest rates look to remain stable and the job market is still healthy.
And more from Australia. Rising electricity prices and recent blackouts in South Australia are driving people across the country to install solar power capability, with panel installations in March at a five-year high.
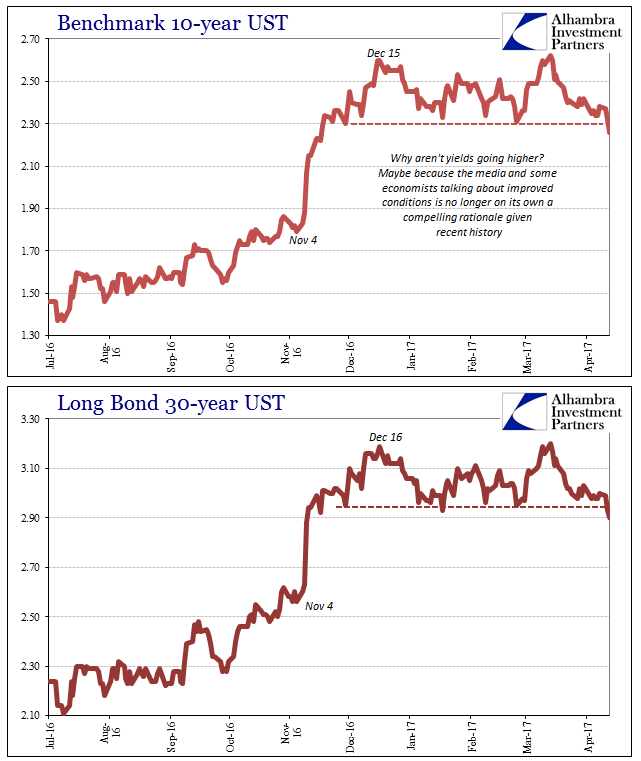
In New York, the UST 10yr yield is sharply lower today, now at 2.23%. An escalation of the conflict in Afghanistan seems to be behind the risk-off rise.
The US benchmark oil price is lower today and now just under US$53 a barrel, while the Brent benchmark is just over US$56.
The gold price has jumped another +US$11 today, now at US$1,286/oz.
The New Zealand dollar is a little lower against the greenback this morning and now at 69.9 USc. On the cross rates it has held its own at 92.4 AU¢, and 65.9 euro cents. The TWI-5 is now at 75.1.

The easiest place to stay up with event risk over the holiday period is by following our Economic Calendar here »
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.