
Here's my Top 10 links from around the Internet at 10:00 am today in association with NZ Mint.
Bernard is back tomorrow with his version.
As always, we welcome your additions in the comments below or via email to bernard.hickey@interest.co.nz.
See all previous Top 10s here.
1. The world's central banker
As of November 2012, the People’s Bank of China had total assets of US$4.8 trillion, more than the European Central Bank or the US Federal Reserve.
The PBOC now supplies more than half the world’s total liquidity and manages foreign reserves worth almost US$3.3 trillion.
Gulp. No wonder European politicians try to persuade the Chinese to buy their bonds. Two University of Queensland professors have taken a close look at its rise.
With its new authority, the PBOC began to flex its muscles in the 2000s, particularly under the governorship of Zhou Xiaochuan, an economist with intimate ties to the political leadership. Although the party still exerts control over the financial sector, the bank has been exploring new, more market- oriented instruments and mechanisms within its discretion to establish a credible monetary policy and maintain price stability.
From 1979 to 1994, economic growth averaged 10.1 percent while inflation averaged 7.7 percent. From 1995 to 2011, economic growth averaged 9.9 percent while core inflation fell to an average of only 3.1 percent. This track record gave the PBOC greater authority and room for maneuver in macroeconomic management.The PBOC also played a central role in liberalizing China’s exchange rate in 2005 and again in 2010, despite mounting internal resistance. Recognizing the importance of a sound banking sector for carrying out monetary policy, the central bank also took the lead in recent banking reforms aimed at improving corporate governance and market discipline. Under Zhou, the bank has also been active in reforming the securities, insurance, and bond markets, internationalizing the renminbi, and establishing state-of-the-art payment and settlement systems.
But the PBOC still faces plenty of challenges. In the short--to-medium-term, it will have to address bad loan risks, especially an increasing prevalence of shadow banking and banks’ exposure to real estate and local-government debt. In the longer term, it will have to ensure stability as China transforms into a more domestically driven economy. What makes these tasks more daunting for the PBOC is that it must constantly bargain and negotiate with other bureaucracies and with the party leadership. It also must implement a more market-oriented monetary policy while constrained by the legacies of the communist past, such as state control of key financial sectors.
2. The US bank stress tests
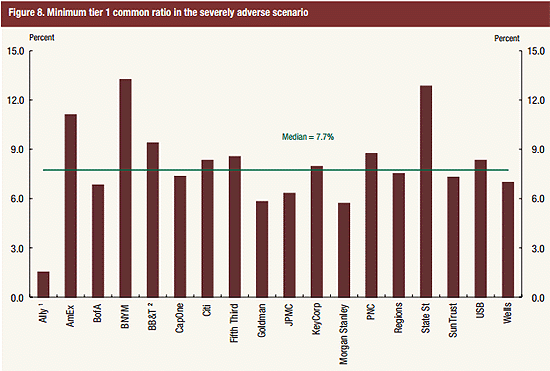
US banks have enough capital to withstand a severe economic downturn, the Federal Reserve has said, after announcing that 17 out of 18 major banks passed its annual stress tests.
Government-controlled Ally Financial, the rescued former finance arm of General Motors, was the only bank to fail the test of capital strength. Wall Street banks Morgan Stanley, at 5.7%, and Goldman Sachs, at 5.8%, were the next two lowest.
3. 725 happy bankers
In Britain, total of 428 employees of Barclays and 93 at RBS earned more than £1m last year according to data released under their new transparency rules. And 204 HSBC employees were paid more than £1m last year, of which 78 were in the UK, where the group has its headquarters.
4. Today's raw market data ...
A quick new week update:
| as at 11:10am |
Today 9:00 am |
Friday |
Four weeks ago |
One year ago |
| NZ$1 = US$ | 0.8213 | 0.8287 | 0.8366 | 0.8198 |
| NZ$1 = AU$ | 0.8028 | 0.8062 | 0.8111 | 0.7751 |
| TWI | 75.86 | 76.09 | 75.88 | 73.05 |
| Gold, US$/oz | 1,582 | 1,588 | 1,652 | 1,697 |
| Dow | 14,386 | 14,336 | 13,975 | 12,951 |
| Copper, US$/tonne | 7,730 | 7,621 | 8,216 | 8,391 |
| Volatility Index | 12.59 | 13.06 | 12.94 | 15.64 |
5. A recipe for division
EU consumers are increasingly asking a simple but discomforting question: Why, in a trading bloc notorious for regulating things like the shape of bananas and the font size on food labels, was something as simple as identifying the difference between a cow and a horse so difficult? The NY Times says the horse meat saga is exposing some fundamental weaknesses.
The horse meat fracas has also put a spotlight on the tenacity of cultural and national stereotypes that were supposed to fade away as a new common sense of European identity took hold. Particularly pronounced has been a tendency in the richer nations of Western Europe to point a finger at what they often see as their poor and unreliable country cousins in the former Communist East.
Growing calls for mandatory “country of origin” labeling on all processed meats sold in Europe have stirred concern in Brussels about a surge in what Mr. Borg, the health and consumer affairs commissioner, has called “veiled protectionism.” Until now, only unprocessed meat had to identify its place of origin.
“The Germans are saying we are only going to eat German products. The French are saying the same for French products. What happened to the common market? This is really serious,” said Françoise Grossetête, a French member of the European Parliament.
6. Yes we're confident, but who knows why
Robert Shiller has spend a career trying to understand what motivates (or demotivates) consumer behaviour. He is still puzzled.
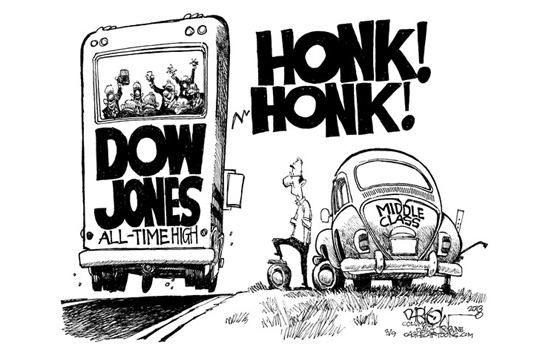
For example, why is a record high in the United States stock market a reason for optimism? Nothing is remarkable about reaching a market record: the S.& P. Composite Index has done it 1,007 times, based on daily closes, since the beginning of 1928. That’s about once every 23 trading days, on average, though the new records tend to come in bunches.
The important fact is that we haven’t set a nominal stock-market record in six years. And we haven’t set one in 13 years if we use the inflation-corrected S.& P. Composite total-return index. That this index may be about to set a record means only that we haven’t made any real money in the stock market in 13 years, which hardly seems a reason for confidence.
But public thinking is inscrutable. We can keep trying to understand it, but we’ll be puzzled again the next time the markets or the economy make major moves.
7. Serious wealth
Norway’s sovereign wealth fund, one of the world’s biggest investors, grew by around NZ$120-billion in 2012 to more than NZ$860 billion, which was one of its best years on record as it benefited from the striking upturn by stock markets. It did it by avoiding EU government stocks, selling out of Apple, and loading up on Aussie bonds.
At the end of last year it sharply cut its holdings of bonds issued by the government of Britain and France, two countries struggling to reduce debt levels while their economies stutter. The fund reduced its holding of British government debt by 13 per cent in the fourth quarter. French government debt holdings fell by a quarter.
The fund also more than quadrupled its holding of Australian government debt.
It earned close to 30 per cent on investments in the financial sector (including HSBC), which also had the biggest weight in its portfolio with 23 per cent. Consumer goods, the second-biggest segment within its share portfolio, also returned a hefty 24.5 per cent.
Meanwhile, in poorly performing sectors, such as utilities and telecommunications, it only had a minimal exposure.
8. 'Don't just do something - stand there'
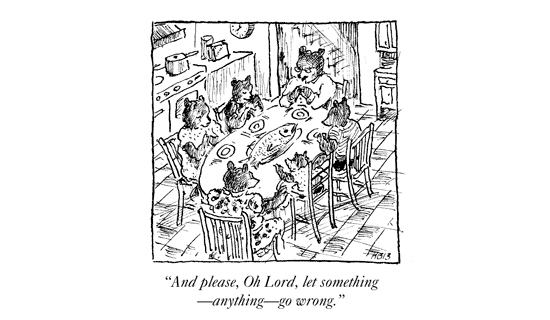
Anatole Kaletsky has four reasons why he thinks Obama should just do nothing on the budget deficit 'crisis'. You will need to read his piece for those four reasons, but he reckons 'deficit denial' is what the US needs right now.
Ronald Reagan had a catchphrase when faced with a crisis, especially a synthetic “crisis” of the kind Washington loves to concoct. He would call in the officials and media advisers rushing manically around the West Wing and calmly tell them: “Don’t just do something – stand there.” In this respect, as in several others, “No Drama Obama” seems to resemble the man he once admiringly described, despite their ideological animosity, as the last great “transformational” U.S. president.
With Wall Street hitting new records as Washington supposedly plunges into its latest fiscal crisis with the budget sequestration that began this week, Obama could do well to emulate Reagan’s laid-back style. In addition to doing nothing about the latest manufactured fiscal crisis, he could explain why nothing is the right thing to do.
To be more specific, Obama could negotiate a truce in the budget war. Instead of insisting that Republicans must “pay” for Democratic spending cuts by agreeing to higher taxes, the president could offer a much more attractive deal to both sides. If Republicans eased the sequester and demanded no new spending cuts, the Democrats could promise not to raise any taxes. Such a ceasefire would be seen by both parties as an honorable draw. Republicans would have fulfilled their pledge to stop higher taxes; while Democrats would have thwarted efforts to gut government and the welfare state.
There would be only one drawback. My fiscal ceasefire proposal does nothing to reduce deficits or government debts. But doing nothing on deficits is exactly the right policy for the U.S. today.
9. Job losses
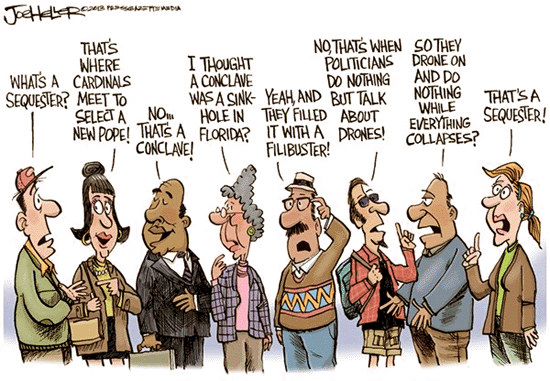
Just one report of jobs lost this week. It is very quiet on that front. However 21 positions are being 'disestablished' at the Wairarapa DHB. Still, that is the only one we have for March so far. (It is a grim comparison, but the road toll is higher.)
We are keeping a tally of reported job losses and we are asking readers for help keeping track of them. Let us know when you see some.
10. Today's quote
"This planet has – or rather had – a problem, which was this: most of the people living on it were unhappy for pretty much of the time. Many solutions were suggested for this problem, but most of these were largely concerned with the movements of small green pieces of paper, which is odd because on the whole it wasn’t the small green pieces of paper that were unhappy.” - Douglas Adams
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.