
Here's my Top 10 links from around the Internet at 10:00 am today.
Bernard is back tomorrow with his version.
As always, we welcome your additions in the comments below or via email to bernard.hickey@interest.co.nz.
See all previous Top 10s here.
1. 'A reckless and distorted system'
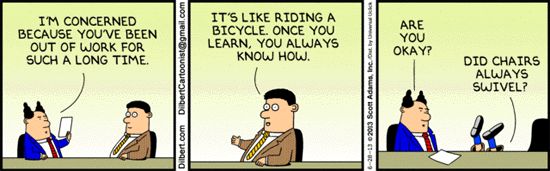
Simon Johnson is scathing about how British banking regulators are doing their job.
He says bankers have sold us a story that their risky practices are the necessary cost of a dynamic system.
This as a misguided and dangerous lie, he claims.
In the end, banks are just loan books. But with dangerously high levels of leverage, they are only as safe as a single-digit percentage of these loans. A distressingly small number of failures by borrowers can wipe out their equity, cascading into depositor losses (via OBR). And its not just 'loans' as we traditionally know them; gross exposure via derivative positions from far away places could be their undoing. Johnson is right on this one; I have long called for much lower leverage by financial institutions.
More at Project Syndicate:
With great fanfare (and generally favorable press coverage), the PRA announced that some banks do not have enough loss-absorbing capital – relative to target levels of equity that are ludicrously low. The Bank of England’s Financial Policy Committee (FPC) said that the target should be 7% of risk-weighted assets under Basel III definitions. And, in the PRA’s presentation, this amounts to a leverage ratio of around 3% for most of these banks (again using Basel III definitions), though a couple of banks will need an additional adjustment to reach that level.
In plain English, a supposedly well-capitalized bank in the UK can have 97 cents of debt per one dollar of assets (and just three cents of equity). Such a low loss-absorption capacity would get you run out of town in the US, where regulators are weighing a 5-6% leverage ratio (twice as much equity on a non-risk-weighted basis), and some responsible officials are still pushing for 10% or higher.
British officials – and those elsewhere – should take a day off and read Anat Admati and Martin Hellwig’s book, The Bankers’ New Clothes: What’s Wrong with Banking and What to Do About It, an inspired “how to” guide for thinking about why we need more equity in our financial system. Then they should come back to work and do their job properly, by phasing in much higher capital requirements in a responsible manner.
2. Fat and lazy
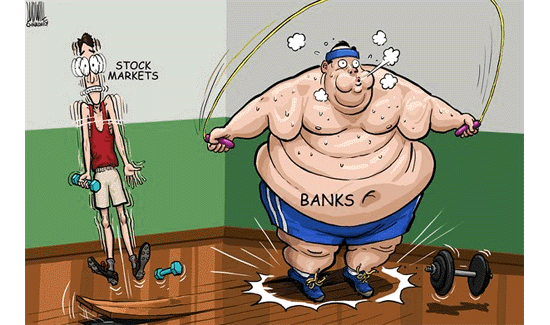
Some of you may have seen this piece a few days ago in the NZ Herald. But it is worth repeating here. Bloomberg columnist William Pesek suggests Australia is in a pretty vulnerable position these days; a high-cost, unreformed economy that has not used any of its time to get ready for a different China.
No country is more vulnerable to the much-dreaded slowdown in China than resource-rich Australia. The mining boom that fueled nearly all of its recent growth is nearing a cliff of economic risk.
“Australia is a leveraged time bomb waiting to blow,” says Albert Edwards, Societe Generale SA’s London-based global strategist. “It is not just a CDO, but a CDO squared. All we have in Australia is, at its simplest, a credit bubble built upon a commodity boom dependent for its sustenance on an even greater credit bubble in China.”
There’s a bit of hyperbole in this view. But highly-advanced Australia is about to pay the price for growing so addicted to a developing nation.
3. A bear market beginning?
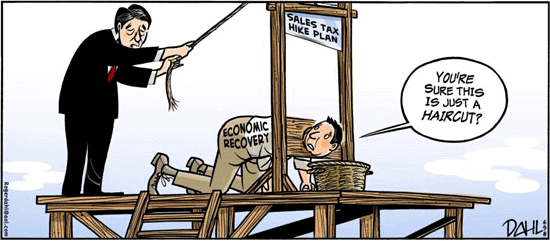
A new period of uncertainty and volatility has begun, and it seems likely to lead to choppy economies and choppy markets. Indeed, a broader de-risking cycle for financial markets could be at hand. So says Noriel Roubini who assesses what faces us at Project Syndicate:
Whether the correction in risky assets is temporary or the start of a bear market will depend on several factors. One is whether the Fed will truly exit from QE as quickly as it signaled. There is a strong likelihood that weaker US growth and lower inflation will force it to slow the pace of its withdrawal of liquidity support.
Another variable is how much easier monetary policies in other developed countries will become. The Bank of Japan, the European Central Bank, the Bank of England, and the Swiss National Bank are already easing policy as their economies’ growth lags that of the US. How much further they go may well be influenced in part by domestic conditions and in part by the extent to which weaker growth in China exacerbates downside risks in Asian economies, commodity exporters, and the US and the eurozone. A further slowdown in China and other emerging economies is another risk to financial markets.
Then there is the question of how emerging-market policymakers respond to the turbulence: Will they raise rates to stem inflationary depreciation and capital outflows, or will they cut rates to boost flagging GDP growth, thus increasing the risk of inflation and of a sudden capital-flow reversal?
4. Today's raw market data ...
A quick new-week update:
| as at 11:10am |
Today 9:00 am |
Friday |
Four weeks ago |
One year ago |
| NZ$1 = US$ | 0.7736 | 0.7785 | 0.7962 | 0.8007 |
| NZ$1 = AU$ | 0.8474 | 0.8401 | 0.8292 | 0.7817 |
| TWI | 73.54 | 73.61 | 75.01 | 72.18 |
| Gold, US$/oz | 1,192 | 1,233 | 1,403 | 1,592 |
| Dow | 14,903 | 15,003 | 15,232 | 12,837 |
| Copper, US$/tonne | 6,751 | 6,706 | 7,331 | 7,648 |
| Volatility Index | 16.86 | 16.86 | 16.28 | 16.76 |
5. Health sector cost myths
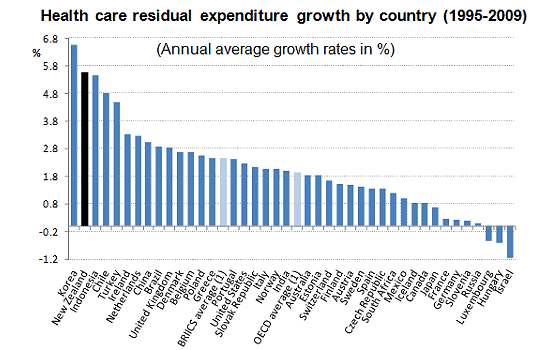
Health care costs are exploding world-wide, right? Costs are rising particularly fast in the USA where the private sector is putting profit before affordability. At least in New Zealand, we have public control to contain reasonable health care costs. That is the narrative that most Kiwis believe. Only, its wrong, as a new study by the OECD shows. New Zealand, Korea, Indonesia, Chile and Turkey fit the narrative, but not so the other 35 countries surveyed.
As Michael Cullen once observed, unless we get control of health care costs, in the end we will all be working just for it.
6. Borrowers beware
Student loans are interest-free in New Zealand, something many borrowers seem to regard as "too expensive". Student fees - much of it borrowed - accounts for about 47% of all tuition costs. Some of it is paid by international students (who pay 100%) but the rest is a cost to taxpayers (about $2 bln per year).
American students pay interest at the rate of 3.4% on their student loans. But because of an unresolved partisan Federal budget argument, that rate rose to 6.4% today (well, actually tomorrow - July 1 in the US). Students there aren't happy. Student loans weren't originally meant to be subsided welfare, rather access to funds that may not otherwise have been available. But the voting middle classes were involved and politicians quickly turned it into a benefit for voters. We just went a bit further than the US in one now-famous election bribe. Here's a summary of the American situation from the LA Times:
At a time when lawmakers face pressure to cut costs and reduce the deficit, the loan issue has invited an ideological debate over whether student borrowing should be a moneymaker for the federal government.
And there is a lot of money at stake.
A new report from the Joint Economic Committee showed that student debt has risen significantly, from $550 billion in late 2007 to about $1 trillion in the first quarter this year. The same report said that without congressional action, the higher Stafford interest rates would add $4,500 to the cost of a four-year college degree.
"The fundamental issue is whether the United States government should be making a profit off our students," Sen. Elizabeth Warren (D-Mass.) said. "We should not be burdening our students further."
But Sen. Angus King (I-Maine), one of the authors of the compromise plan, said federal student loans were not intended to be a subsidy program. "What we tried to do is design a system that was both fair to taxpayers and to students," he said.
7. A dubious history
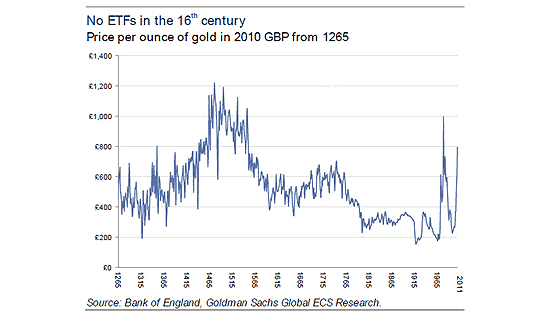
Gold is in a bit of a bear market at present, having fallen all year and is now selling for less than US$1,200/oz. But it's not always been like that, has it? Well, actually it has. It was in a bear market from 1500 to 1965 - that's a 450 year bear market! From 1265 to 1500 it did quite well as an investment, and in the past 50 years. But other than that ... The take-away is that bear markets for gold can be quite long, and outlast your children's children's children. This chart is from Zerohedge: there's not a lot of history behind the idea that "gold is a good [insert feature] ... "

8. The secret is quick action
Just a few years ago, Latvia was on the edge of bankruptcy. Now, it's poised to join the euro zone in 2014. In an interview with SPIEGEL ONLINE, Prime Minister Valdis Dombrovskis explains why austerity turned the country's economic fortunes around.
A physicist by training, 41-year-old Valdis Dombrovskis was elected Latvian Prime Minister in 2009 after serving as finance minister from 2002 to 2004 and as a member of the European Parliament from 2004 to 2009. In 2011, his center-right New Era Party merged with two other parties to form the new political party Unity. Now the country's longest-serving prime minister, Dombrovskis has pushed through some of the toughest austerity measures in Europe in order to rescue the state from bankruptcy and prepare Latvia to join the euro-zone by 2014.
SPIEGEL: Why did austerity work in Latvia, while in Greece it has deepened the crisis?
Dombrovskis: Latvia started to restore financial stability quickly. Greece and the other countries waited too long. They postponed necessary measures, as they believed austerity and structural adjustments would be bad for the economy. It turned out that not doing anything, sometimes for years, was much worse.
9. The middle-class revolution
Francis Fukuyama argues today's political turmoil has a common theme: the failure of governments to meet the rising expectations of the newly prosperous and educated. From Egypt to Brazil, middle class activists are trying to change governments. But these efforts are being held up by poorer, less educated power bases who are resisting 'modernising' changes.
Fukuyama's is a seasoned observer and his analysis is always worth reading:
Families who have durable assets like a house or apartment have a much greater stake in politics, since these are things that the government could take away from them. Since the middle classes tend to be the ones who pay taxes, they have a direct interest in making government accountable. Most importantly, newly arrived members of the middle class are more likely to be spurred to action by what the late political scientist Samuel Huntington called "the gap": that is, the failure of society to meet their rapidly rising expectations for economic and social advancement. While the poor struggle to survive from day to day, disappointed middle-class people are much more likely to engage in political activism to get their way.
10. Today's quote
"Speculators may do no harm as bubbles on a steady stream of enterprise. But the position is serious when enterprise becomes the bubble on a whirlpool of speculation. When the capital development of a country becomes a by-product of the activities of a casino, the job is likely to be ill-done." - John Maynard Keynes
11. Today's joke
"A rich, dying man, laid on his deathbed, requested to be joined at his bedside by his vicar, his bank manager and his lawyer. He instructed them that he wished to be buried when he finally passed away, along with all his money. He gave each of them fifty thousand pounds and asked them to throw the money on top of his coffin in the burial plot when he died. A couple of days later the old man passed away and was buried within the week. At the wake, the three men were chatting and the vicar was suddenly overcome with guilt. He confessed to the other two that he had only thrown only half of the money onto the coffin as the church needed urgent repairs to the roof. The bank manager thought, ‘What the heck if we are having a confession,’ and told the other two men that he had also only thrown half the money in, as the ‘Credit Crunch’ was hitting hard and he needed some money for the bank to stop it going bust. The lawyer jumped up and said to the other two, ‘I think that is a shameful act on both of you. I threw a cheque in for the full amount!”
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.