
As part of our summer series on the household term deposit market, we now want to take a look at the 'term' structure of the market.
We have previously posted an RBNZ analysis, and also a review of which banks offered the best rates consistently. Now it is a look at the length of time depositors are prepared to lock up their funds.
Households have $261 bln in deposits at banks (S42). Given there are 1,995,500 households, that is a rather remarkable $130,830 in the average household bank deposit. Clearly, this is not evenly distributed, so some households have very large combined bank account balances.
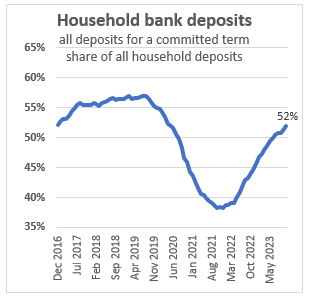
A bit more than half of these overall bank balances are in a term-committed deposit. As you can see households shifted their holdings to at-call (transaction or savings) accounts aggressively during the pandemic, but haven't yet shifted back to TDs at the pre-pandemic level yet.
When they do get back to the 56% level, that means another $10.5 bln will shift across. This last bit might take some time given the lessons of the pandemic. But good interest rate offers will help and are behind the fast recovery.
Savers might be attracted to the interest rates in term offers, but they are still choosing short terms.
Less than 5% of all household deposits are for terms of 1 year or longer,
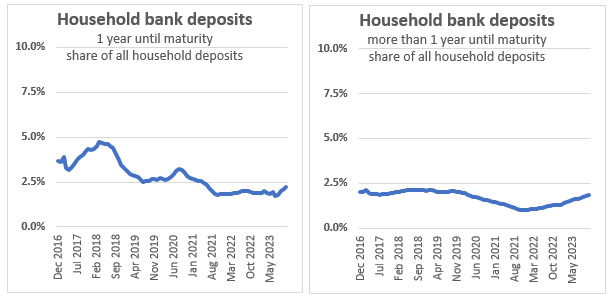
and there is clearly no rush currently to increase holdings for these longer terms.
The real weight of TD's are in the less-than-a-year terms.
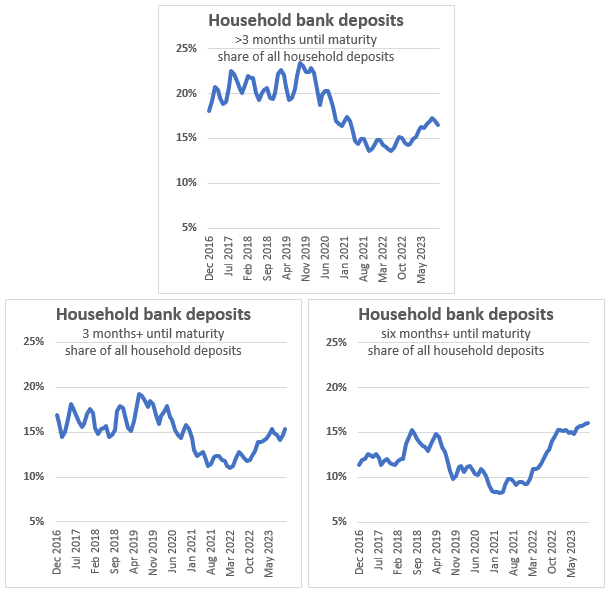
However, the six to 12 month terms have become increasingly popular, no doubt induced by the relatively high interest rates on offer. "6%" rates are doing the trick, drawing in a record share for these slightly longer terms. Pre-pandemic, when rates were low, it was the less-than-3-month category that dominated. That is shifting longer post-pandemic with the new high offer rates.
Solid, above-inflation interest rate offers do move saver behaviour.
To have balances this large, households with them are obviously not young, or 'starting out'. It is safe to say they are 'old' and corralling their resources into cash as they approach or are in retirement. It is a natural transition, and helps explain why the age cohort has economic power and is vocal expressing themselves when they feel challenged. Boomers confirming and reinforcing the stereotype that the rest of society has concluded.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.