
Home ownership is likely now out of reach for typical first home buyers in most parts of New Zealand unless they have a 20% deposit.
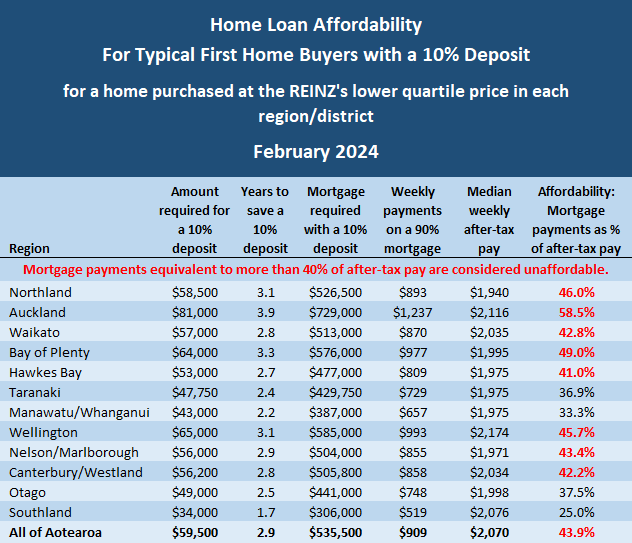
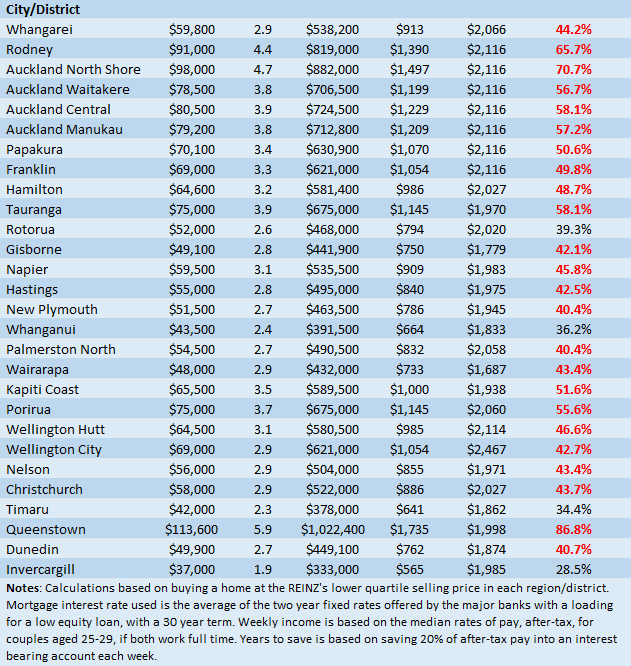
The latest affordability analysis by interest.co.nz shows Rotorua, Whanganui, Timaru and Invercargill are now the only urban centres in NZ where it would still be affordable for typical first home buyers on average wages to buy a home with a 10% deposit.
In all other areas the mortgage payments they would have to make if they purchased a home at the lower quartile price for that district with a 10% deposit, would eat up more than 40% of their after-tax pay, the threshold at which mortgage payments are considered unaffordable.
In Auckland, the country's most populous region, mortgage payments on a lower quartile-priced home purchased with a 10% deposit would devour a whopping 58.5% of the after-tax pay for a typical first home buying couple.
Affordability improves markedly for those first home buyers who can scrape together a 20% deposit.
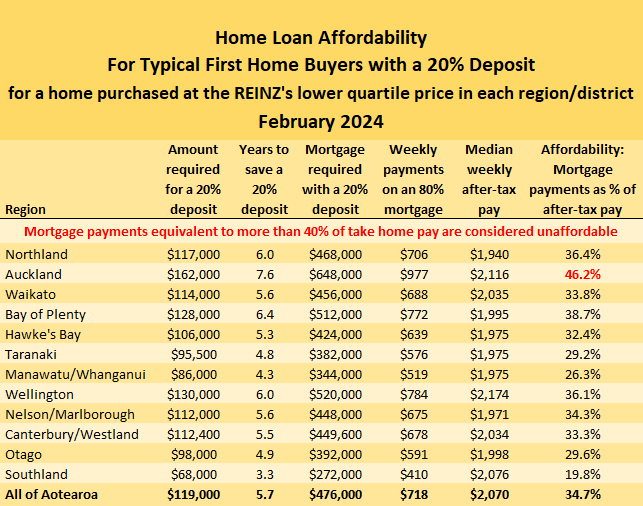
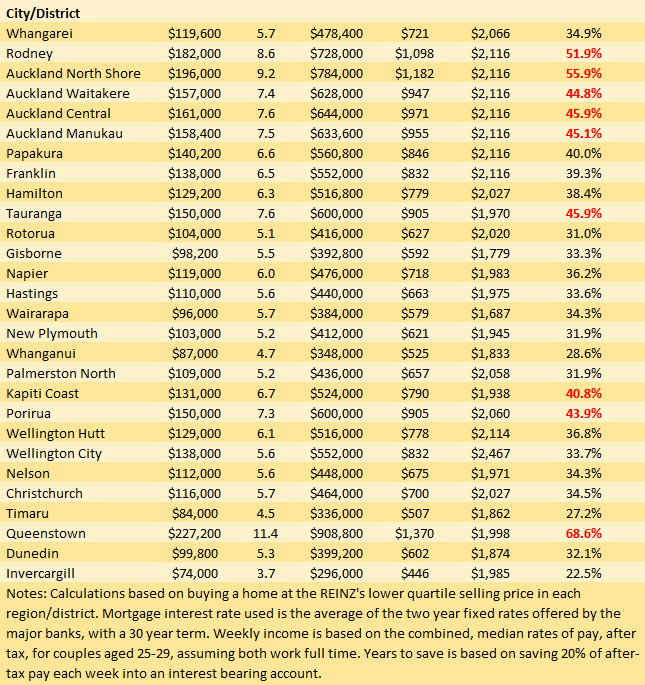
Auckland, Tauranga, Kapiti Coast, Porirua and Queenstown are the only urban centres that remain unaffordable for typical first home buyers even if they have a 20% deposit.
Within the Auckland Region, Rodney, North Shore, Waitakere, the central suburbs and Manukau would all be out of reach for typical first home buyers on average incomes, even if they had a 20% deposit.
Papakura would be marginal, with mortgage payments there eating up exactly 40% of average after-tax pay. So even a slight deterioration in affordability there would push it into unaffordable territory, while Franklin on Auckland's southern fringe would be considered affordable at 39.3%, but only just.
So getting a deposit together is the key to home ownership.
The trouble is house prices are now so astronomically expensive that getting even a 10% deposit together may not be possible for many aspiring first home buyers on average wages, and a 20% deposit would likely be out of the question.
The Real Estate Institute of New Zealand's national lower quartile price, the price at which 25% of sales were below and 75% were above, representing the most affordable end of the housing market, was $595,000 in February.
That would require $59,500 for a 10% deposit and $119,000 for a 20% deposit.
In higher priced regions such as Auckland, those amounts increase to $81,000 for a 10% deposit and $162,000 for a 20% deposit.
Interest.co.nz estimates a couple working full time on the median rates of pay for 25-29 year olds, would need 3.9 years to save a 10% deposit for a lower quartile-priced home in Auckland, if they managed to save 20% of their after-tax pay each week into an interest bearing account, or 7.6 years to save a 20% deposit.
Unfortunately, even if they saved a 20% deposit, they probably wouldn't be able to afford the mortgage payments on a lower quartile-priced home.
Which means home ownership in Auckland is now largely restricted to people earning higher than average wages.
Increasingly, home ownership is not just out of reach for low paid folk, it is out of reach for those on average wages as well.
The tables below show the main affordability measures for purchasing a lower quartile-priced home with either a 10% or 20% deposit, in all urban centres around the country.
The comment stream on this story is now closed.
•You can have articles like this delivered directly to your inbox via our free Property Newsletter. We send it out 3-5 times a week with all of our property-related news, including auction results, interest rate movements and market commentary and analysis. To start receiving them, register here (it's free) and when approved you can select any of our free email newsletters.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.