
A sharp increase in the number of mortgagee sale properties has emerged over the last few weeks.
Interest.co.nz has been tracking the number of mortgagee sales on the market each week since November 2022. For the most part their numbers have remained relatively low.
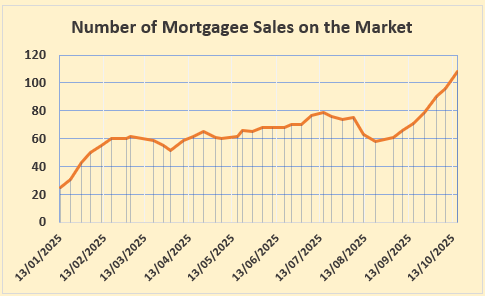
Up until early October 2023 there were less than 50 mortgagee sale properties on the market at any time. In mid-October 2023 they pushed past 50, and passed 60 in April last year.
They hovered between 50 and 60 for most of last year, then began rising again this year.
The increase in mortgagee sales has been particularly strong since late September this year. At the beginning of October it went past 90 for the first time since interest.co.nz began collating the numbers. By mid-October, the numbers had surged to 109. (See the graph below for the trend so far this year).
The timing of the increase is surprising because it comes as mortgage interest rates have been falling. However, Reserve Bank data shows the total value of impaired loans held by banks increased by $15 million in August to $563 million.
There are several things banks can do to prevent a mortgagee sale when a customer strikes financial difficulties including; extending the term of a loan, converting it to interest-only payments for a period of time and, even payment deferral while the customer tries to restructure their finances.
However, the fact the number of mortgagee sales has been rising even as interest rates fall suggests the most likely reason is borrowers have faced an unexpected drop in income, usually due to job loss or business failure.
In such situations, no amount of mortgage restructure can make up for the fact the borrower simply has no money coming in.
The borrowers who will be most vulnerable in such a situation will be those who bought during the 2021/22 housing boom, particularly those who purchased their property with a low equity loan at the maximum term available, and then suffered a loss of income.
As well as losing their ability to make their mortgage payments, these people may also have faced the indignity of being tipped into negative equity, as the value of their home declined in the face of a weaker housing market, leaving them with little wriggle room to restructure the loan.
In such situations, a mortgagee sale becomes almost inevitable. And the borrower may still owe the bank money even after the property is sold, if the sale didn't raise enough money to fully repay the mortgage and any additional bank charges plus the real estate agent's commission on the sale.
That could see the borrower not only losing their home, but potentially facing bankruptcy as well.
The comment stream on this article is now closed.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.