
By Greg Ninness
In Auckland it is still possible for a young couple who purchased their first home five years ago to move up the property ladder and buy a more expensive home, even if one of them only works part time, according to Interest.co.nz's latest Home Loan Affordability Reports.
The reports track how affordable the mortgage payments would be for three typical couples at different stages of the property ladder in each of the major centres throughout the country:
- A couple aged 25-29 who both work full time and are looking to buy their first home at the REINZ's lower quartile selling price.
- A slightly older couple aged 30-34 with a young family where one works full time and the other for 20 hours a week, who would have purchased their first home five years ago at the lower quartile price at the time, and are now looking to move up the property ladder and buy their next home at the REINZ's current median selling price.
- A couple aged 35-39 who both work full time and who purchased their first home 10 years ago at the lower quartile price at the time, and are now looking to buy their next home at the current median selling price.
It is assumed each couple earn the median rate of pay for people of their age in and the mortgage payments are considered affordable if they take up no more than 40% of their take home pay.
The reports show that housing remains affordable for all three groups except in the overheated property markets of Auckland and Queenstown.
In Auckland, a lower quartile-priced home would be unaffordable for a couple on a median income because the mortgage payments would take up 43.6% of their take home pay, before allowing for other property related expenses such as rates, insurance and maintenance.
The rising house price effect
However moving on up to the second rung of the property ladder should still be affordable for couples who purchased their first home 5-10 year ago, because they would have benefited from a significant increase in their equity from rising house prices.
If they had purchased their first home five years ago at the REINZ's lower quartile price at the time and resold it at the current lower quartile selling price, they would have equity of $368,535 to put towards the purchase of median priced home.
Their equity comes from the increase in the value of their first home over the last five years less an allowance for agent's selling commission, plus the capital payments they would have made on their mortgage over that time.
To buy a home at the REINZ's current Auckland median price of price $825,000 they would need a mortgage $465,665 and the payments on that would be equivalent to $529.63 a week or 38.6% of their take home pay.
So moving up the property ladder would still be affordable for them, even when one partner is only working part time, although after the mortgage payments were made they'd have $842 a week to pay for everything else. So there wouldn't be much spare cash if they had a young family.
However their situation would improve significantly if/when the partner working part time returned to full time work.
For the slightly older couple aged 35-39 who purchased their first home 10 years ago and who now both work full time, moving up the property ladder would be even more affordable.
Selling their first home after 10 years would leave them with equity of $434,735, which means they'd need a mortgage of $390,265 to buy a median priced home.
Assuming the mortgage term was 30 years, their repayments would take up just 23.7% of their take home pay.
That gives the older couple plenty of options.
They could keep their mortgage payments modest and divert some of their money into savings and investments, or they could pay off their mortgage faster and then start saving in earnest for their retirement.
The reports highlight the disparity in wealth in Auckland between those who have owned their home for a number of years and have benefited from the increase in equity which rising house prices have provided, and those who are struggling to make the leap and get on to the first rung of the property ladder.
Queenstown
The only place facing affordability issues is Queenstown, where the problems are even worse.
The mortgage payments on a lower quartile-priced home in the resort town would suck up a whopping 48.9% of typical first home buyers' take home pay, and it's unlikely that a couple who purchased their first home there five years ago would be able to move up the property ladder and buy their next home in the town if one of them was working part time.
Even a couple who bought their first home in Queenstown 10 years ago and who both now work full time, wouldn't have a lot of cash left over if they traded up and bought a median priced home. That's because the mortgage payments would eat up 37.5% of their take home pay, which is just within affordable limits.
But outside of Auckland and Queenstown, housing remains affordable for all of the typical home buyers profiled in the Home Loan Affordability Reports, giving people outside of the two property hotspots more options when planning their financial futures.
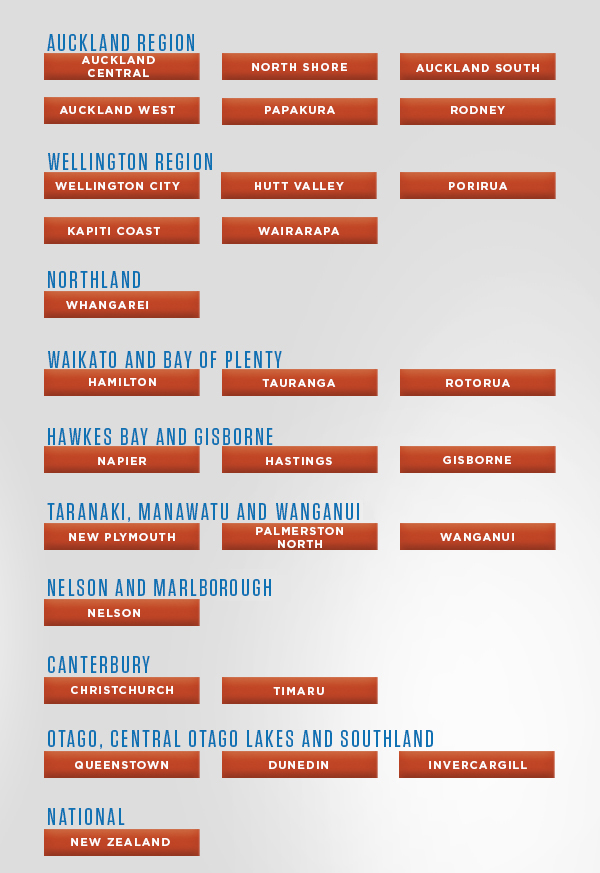
The full suite of Home Loan Affordability Reports are available for most of the regional centres throughout the country - click on the links below to read any of the reports:
You can receive all of our property articles automatically by subscribing to our free email Property Newsletter. This will deliver all of our property-related articles, including auction results and interest rate updates, directly to your in-box 3-5 times a week. We don't share your details with third parties and you can unsubscribe at any time. To subscribe just click on this link, scroll down to "Property email newsletter"and enter your email address.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.