
By David Hargreaves
The suffering, amazingly, is not yet over for long-suffering shareholders in building giant Fletcher Building after it put its shares into a trading halt on Thursday.
Fletcher now says it is expecting to breach one or more of its covenants in its financing arrangements as a result of further losses expected.
The company, which has booked substantial losses in the past year - mostly on government-related projects - told the NZX that it had identified yet more problems in its strife-torn building and interiors division.
Last year the B&I division lost $292 million.
The company has already forecast further losses for that division in this financial year of $160 million. Now it's indicating that losses will be even more than that.
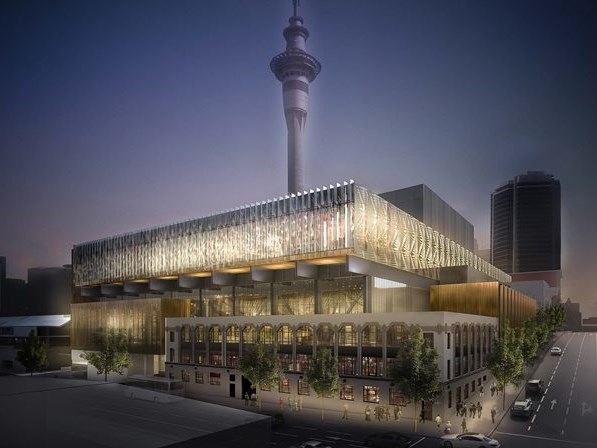
Problematic projects for the company have included the new Sky City International Convention Centre in Auckland and the new Justice and Emergency precinct in Christchurch.
Fletcher has now indicated that as part of its preparation of six month accounts for the period to December 31, 2017, it has been reviewing "key projects" in the B&I division and now expected further "material" losses in that division that would see it breach "one or more of the covenants in the Group’s financing arrangements".
It made this statement to the NZX:
Fletcher Building has today requested a trading halt of its shares and capital notes on the NZX and ASX exchanges. The trading halt has been sought because the Company is in the process of reviewing the key projects in its Building and Interiors (B+I) business as part of the preparation of the Group accounts for the six months ended 31 December 2017.
Although the project reviews are not yet complete, the current expectation of the Board is that there will be further material losses in the B+I business beyond what was provided for in October 2017. Once the extent of those further losses is determined and provided for, it is expected that this would result in a breach of one or more of the covenants in the Group’s financing arrangements.
The Company expects the trading halt to continue until the commencement of trading on Monday 12 February 2018 prior to which it will provide to the market the results of its review.
In the midst of the turmoil last year, Fletcher parted company with chief executive Mark Adamson - the final catalyst seemingly being an incendiary internal email Adamson sent regarding the problems in the B&I division, which chairman Ralph Norris publicly apologised for. Adamson has been replaced by Ross Taylor.
In the update to shareholders at the annual meeting last October, Fletcher indicated that it would make losses in this financial year of about $160 million in the B&I division. Presumably the Thursday statement from the company indicates that the damage will be considerably more than that.
The update to shareholders talked of operating earnings this financial year - excluding the troubled division - of $680 million to $720 million.
Fletcher is expecting the trading halt to continue till Monday at which point it will provide the market with more information.
As per its financial results for the year to the end of June 2017, Fletcher had over $1.9 billion of term borrowings.
Included in this was $389 million of bank loans, with this information given in the annual report:
At 30 June 2017 the group had a syndicated revolving credit facility on an unsecured, negative pledge and borrowing covenant basis, with ANZ Bank New Zealand Limited, The Bank of Tokyo-Mitsubishi UFJ Ltd, Bank of New Zealand, Commonwealth Bank of Australia, Citibank N.A., The Hongkong and Shanghai Banking Corporation Limited and Westpac New Zealand Limited. The funds under this facility can be borrowed in United States, Australian and New Zealand dollars. The borrowing covenants relate to net debt to EBITDA and interest cover and at 30 June 2017, and throughout the year, the group was in compliance with the covenants.
Then there was $1.123 billion of 'private placements', with this detail provided in the annual report:
The group has borrowed funds from private investors (primarily US & Japanese based) on an unsecured, negative pledge and borrowing covenant basis. These borrowings comprise A$231 million, US$582 million, C$15 million, EUR41 million, GBP10 million and YEN10,000 million with maturities between 2017 and 2028. The borrowing covenants relate to net debt to EBITDA and interest cover and at 30 June 2017, and throughout the year, the group was in compliance with the covenants.
Additionally, there's also $329 million in capital notes and $62 million in 'other' loans.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.