By David Skilling*
The inflation trajectory, and the accompanying monetary policy response, is one of the big economic and market uncertainties for the year ahead. But beyond the near-term issues, the structural environment for inflation and monetary policy is also changing.
Double digit inflation provides a taste of some of the pressures ahead as economic and political regime change continues. Our 2023 outlook paper noted pressures for an ‘unravelling of the macro policy order’ as the global economy moved onto a wartime footing. The disinflationary environment of the past few decades is being replaced by new realities.
Transitory inflation
My basic view is that the inflation surge since 2021 was largely due to several post-Covid dynamics: global supply chain frictions; the strength of the rotation of consumer spending from services to goods; the exit of large numbers of workers from the labour force (either temporarily or permanently); as well as aggressive macro stimulus, particularly fiscal policy.
The severity of the supply side shocks, coupled with a strong economic recovery, led to multi-decade highs in inflation across advanced economies. This inflationary process was strengthened and lengthened by Russia’s invasion of Ukraine: food and energy prices surged, particularly in Europe.
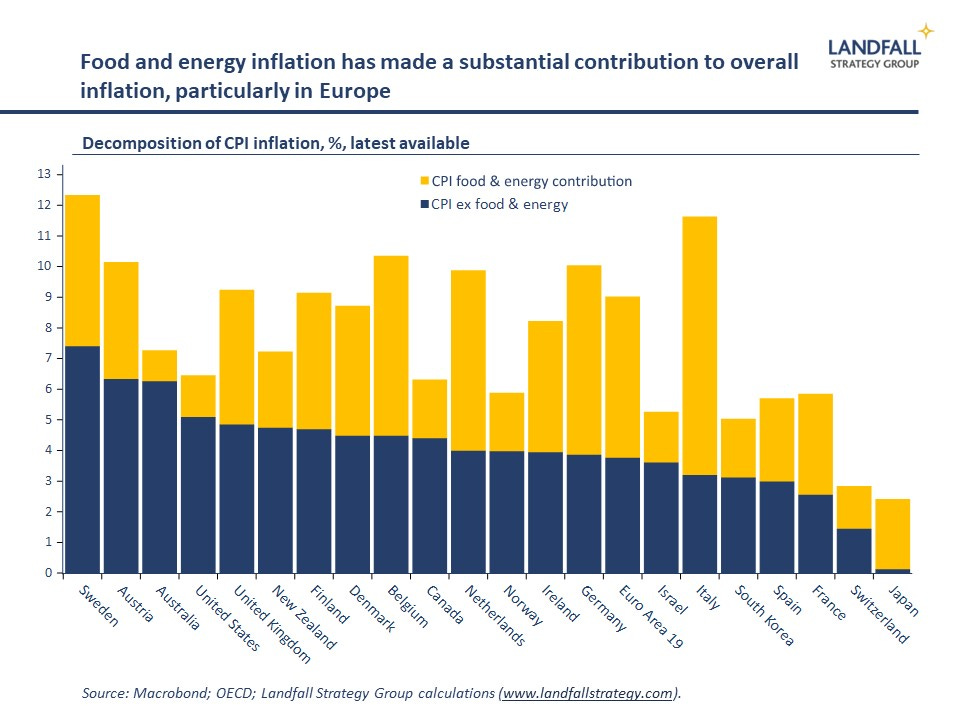
By extension, my view is that inflation will reduce as these factors moderate (I’m in the ‘team transitory’ camp). Indeed, many inflationary dynamics are currently unwinding: as noted last week, global supply chain costs are easing; food and energy prices are reducing; and consumer demand is rebalancing back towards services, removing a source of friction.
Inflation surprised on the way up, and it’s likely to surprise on the way down. Inflation has begun to reduce sharply from its peaks.
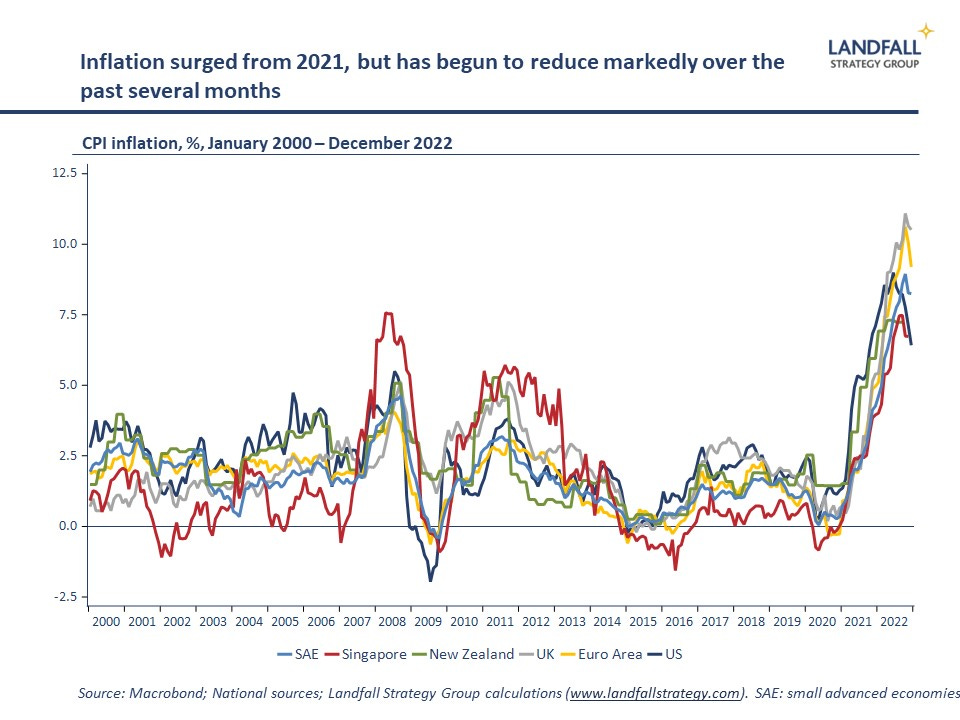
Core inflation remains well above target levels, but I see little evidence of a wage/price spiral or a meaningful de-anchoring of inflation expectations across advanced economies.
Tighter monetary policy is required to address inflationary pressures due to excess demand. But central banks need to be careful not to overdo the tightening response, using monetary policy to address supply side shocks (from energy prices to post-Covid labour markets).
Wartime inflation
However, at the same time as transitory inflation is coming down, other structural drivers of inflation are picking up that will lead to sticky inflation at higher trend levels than over the past few decades.
Over much of the past few decades, there has been a relatively benign inflation environment: the deflationary effects of globalisation; the massive expansion of the global labour force, as China and other emerging markets integrated into the global economy; positive demographics; technology; and so on. But many of these deflationary factors are either weakening or reversing, creating a less benign environment.
Beyond these factors, the inflation outlook will be shaped by the shift to a ‘wartime’ global economy. The economic dynamics unleashed in response to rising geopolitical tension will shape the inflation context: pressures for substantially higher government spending (increased military spending, industrial policy, the energy transition); more rapid economic decoupling in pursuit of strategic autonomy; increased supply chain frictions and risks; and so on.
History shows that periods of war, both hot and cold, tend to be inflationary. And although the ‘war’ is likely to be mainly economic rather than military, inflationary pressures will still manifest – particularly given the likely disruptions to a deeply integrated global economy. The Great Moderation and post-Cold War peace dividend, which provided the context for the inflationary environment of the past few decades are in the rearview mirror.
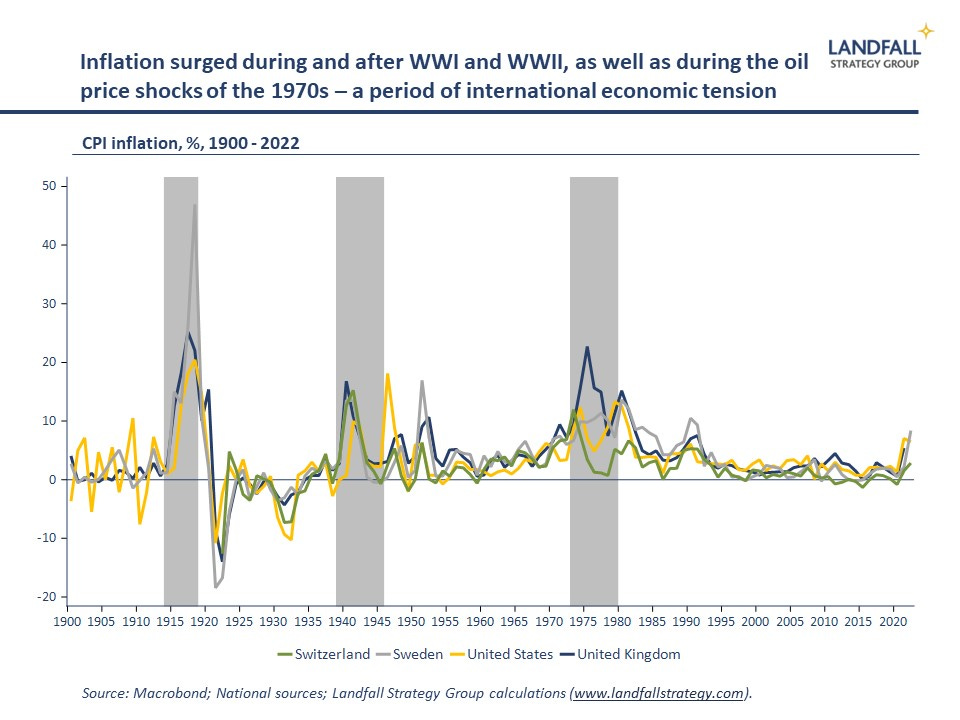
Trend inflation that is sticky above the 2% targets is more likely than not. The current inflation surge will moderate, but will be replaced by structural inflation pressures: ‘war by other means’ will mean expanding demand as well as supply-side constraints.
Policy debates
These dynamics will lend strength to several monetary policy debates. There are a few lines of active discussion that I have been struck by.
First, expect more focus on the inflation target. Keeping trend inflation at or below 2% in this environment will require increasingly tight monetary policy, which is not economically or politically sustainable. There is already an active debate about whether a higher target – say 3% – may be more appropriate. As inflation remains sticky above 2% over the medium-term, this debate will intensify.
Second, the recent experience of countries has highlighted the use of non-monetary levers. France, for example, has used (government financed) price caps on energy bills to control inflation. On some estimates, this has reduced headline inflation by ~3%. Other countries have also implemented price caps, imposed windfall taxes on profits, managed wages through tripartite arrangements, released strategic petroleum reserves, and so on.
There is an increasingly active debate on strategic price controls (Isabella Weber) as well as on the use of non-monetary policy levers (Olivier Blanchard and Paul Krugman). Structurally higher inflation will provide impetus to this debate, as has been the case in previous wartime situations.
And third, growing political debate about the extent of central bank independence is likely. Central bank independence was one of the institutional markers of the emergence of the new policy regime from the late 1980s/early 1990s, and will come under pressure in a new global strategic context.
The government’s growing borrowing requirements as spending demands increase – from military spending and industrial policy to the net zero transition – will create a need to find buyers for this debt. Pressures for ‘fiscal dominance’ will grow in some economies as governments require/encourage central banks to provide greater fiscal space (low rates, buying government debt, and so on).
Monetary policy is not immune to political realities. As discussed in our 2023 outlook note, if policy institutions are in tension with changing strategic priorities, it is likely that it is the institutions that will give. Inflation is importantly a political phenomenon, and monetary policy will be subject to political influence.
What this means
Significant changes are likely in the operation of monetary policy. Nominal interest rates will continue to increase, as we move away from the QE environment implemented in response to below-target inflation. Indeed, negative interest rates have all but disappeared from the global economy: with Japan the latest to move above the zero threshold.
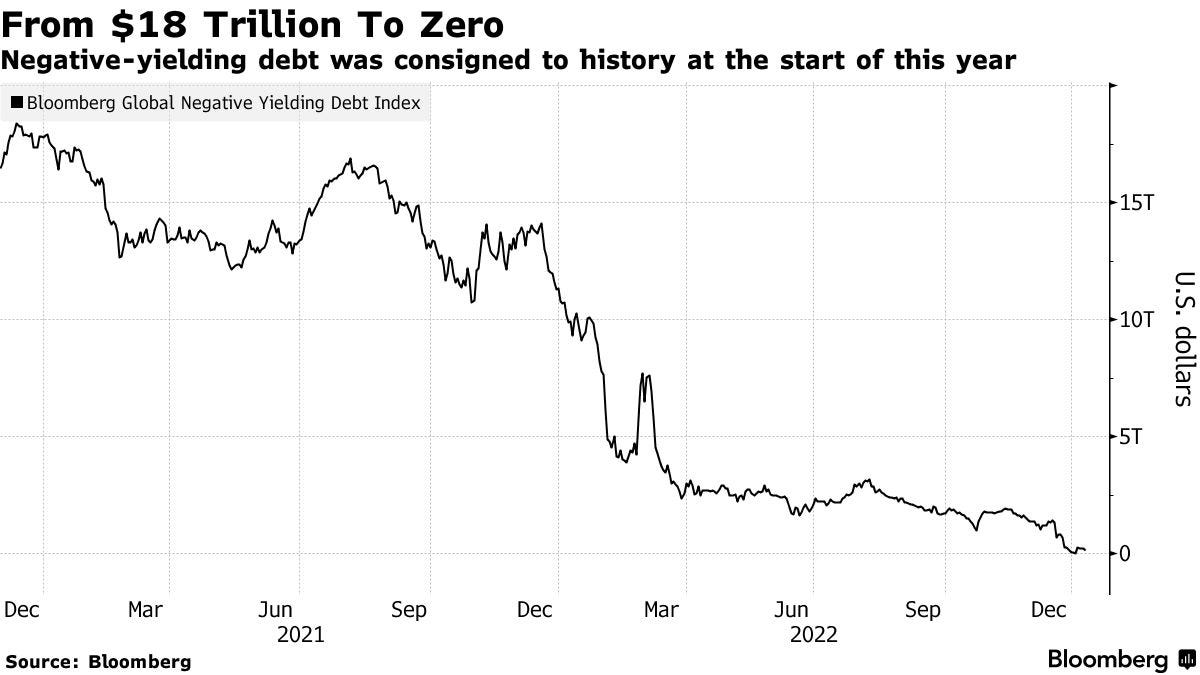
But the more accommodating monetary policy stance - a higher inflation target, increased reliance on other instruments to control inflation, and perhaps a measure of financial repression - means that policy rates will likely be lower than would otherwise be expected given higher inflation.
So expect higher trend rates of inflation, as a consequence of changing global economic dynamics, government responses to strategic competition, as well as more accommodating monetary policy. My guess is that inflation will be controlled, but that there will be greater comfort with inflation in, say, the 3-4% range.
Together, this means that real interest rates will likely remain under downward pressure. [As an aside, this is consistent with the very long term negative trend in real interest rates documented by striking Bank of England research!]
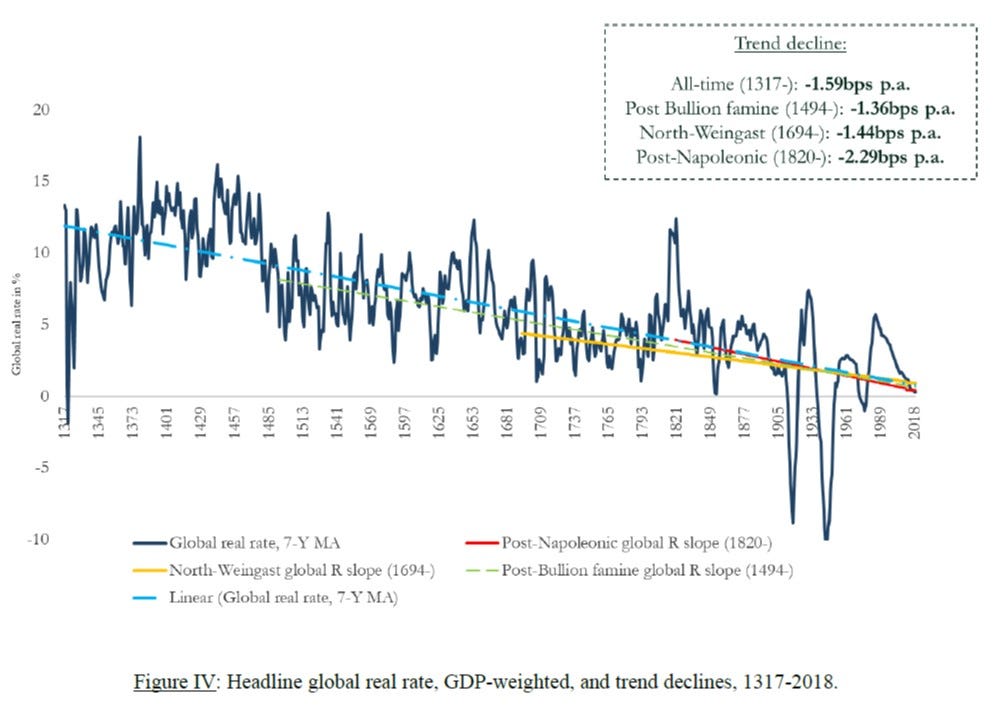
Monetary policy will adapt to new global economic and political realities. However, this transition will be bumpy, with experimentation, policy lags, and over/under-shooting. And not all economies will move at the same speed: small economies, which have fewer degrees of policy freedom than large economies, are likely to follow not lead. Although I think there is clear direction of travel, there will be turbulence ahead.
*David Skilling ((@dskilling) is director at economic advisory firm Landfall Strategy Group. The original is here. You can subscribe to receive David Skilling’s notes by email here.
**Get in touch (by reply email or at contact@landfallstrategy.com) if you would like to access the full paper referred to in the article above.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.