The Commerce Commission's final decision on interchange fees on the Visa and Mastercard networks delivers only a third of the savings estimated for consumers in its December 2024 draft decision.
Today's decision estimates a $90 million annual reduction in the benefits to merchants and consumers of lower caps on the fees paid by New Zealand businesses to accept card payments.
That's down from the $260 million suggested in the draft decision.
The commission said it would continue to study the surcharges by which merchants pass these fees through to customers.
"Consumers can expect these cost savings to flow through to fewer and lower surcharges, but regulation may still be needed to curb excessive surcharging," said Chairman John Small.
“We’ll be exploring what regulation may be needed to address excessive surcharging, which we consider to be anything more than the cost businesses face to accept Visa and Mastercard payments."
The Commission decided not to regulate fees for commercial credit cards or prepaid debt cards, but will continue to study that area.
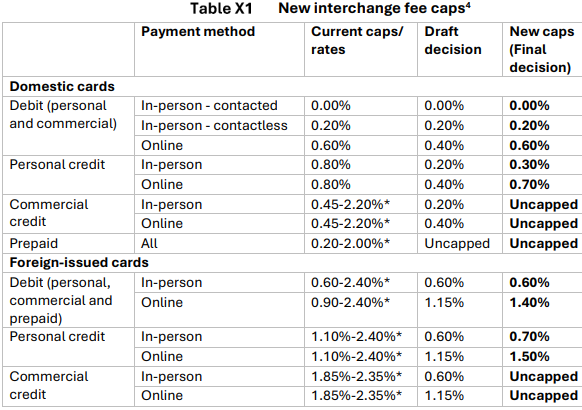
The final ruling will replace fee caps introduced in the 2022 Initial Pricing Standard, which the Commission says is saving businesses $140 million a year.
In the document explaining the reasons for its final decision the commission says businesses are "still paying too much," $1 billion a year to accept MasterCard and Visa payments of which $600 million in interchange fees.
The current retail payment system "lacks strong competitive pressure, and most merchants are still price takers for interchange fees."
Interchange fees remained significantly higher than in comparable jurisdictions and were more than double those of Europe for personal domestic credit card transactions.
However, Small told RNZ, the commission "decided we needed to leave a bit more money in the system [than proposed in the draft decision] to incentivise new entry and dynamic competition."
The document says some submitters argued setting fees too low could reduce innovation, stifle competition in the retail payment system and hamper the emergence of open banking.
"Many" submitters called for changes to or the removal of caps on credit cards on the grounds that these involved higher fraud costs, among other things.
Submitters (other than retailers) also called for a ban or reduction in surcharging. Consumer submissions were skeptical merchants would pass on savings from interchange fee caps.
Not all merchants imposed excessive surcharges and some imposed none, the commission said.
However, it said it "expects to regulate surcharging," adding that it wanted to deal with interchange fee cost first.
Fees on commercial credit card transactions will not now be regulated.
The commission said it considered fees currently charged to be excessive and "unless we see these fees coming down ... we will consider consulting further."
Submitters argued online transactions also have high underlying costs.
ANZ submitted that online transactions make up approximately 92% of the value of fraudulent transactions.
The commission appears also to have accepted arguments personal credit cards should attract higher fees because thy have high underlying costs, including fraudulent use.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.