
Here's our summary of key economic events over the weekend that affect New Zealand with news China is on a knife-edge in its battle to keep Omicron out.
This year, Chinese New Year, the Year of the Tiger, starts officially on February 1, and then there is are about two weeks of public celebrations until Lantern Festival. And the related travel season is about to start now and will run until the end of February. This year it will be stunted with restrictions around their hosting of the Winter Olympics and the threat of an Omicron outbreak. It is a nervous time in China as a growing set of travel bans are being imposed. For traders with China, consumption should rise, but logistics problems will be intense as well.
Average new home prices in China's 70 major cities fell in December from November as concerns about property default and tighter policies aimed at driving speculators out of the property market grow. On a year-on-year basis they rose by just +2.6% in December, after a 3.0% gain a month earlier and down from +5% in mid 2021. This was the weakest annual rise in new home prices in five years.
But there was better news for them on the trade front. China's trade balance swelled in December as export growth stayed elevated and rising +4.8% from November while import growth slowed, falling -2.8% from the prior month. Both were up about +20% year-on-year and took them to an overall 2021 surplus of +US$676 bln or about 2.8% of total world trade. The politically sensitive surplus with the US came it at +US$39 bln in December which in its historical context isn't that remarkable. It was +US$30 bln in November and +US$30 bln in December 2020. But clearly, American tariffs have had zero impact. (The US had an overall trade deficit with all-comers in 2021 of -US$850 bln or -3.6% of GDP; less than half was with China.) China ran a trade deficit of -US$4.5 bln in December with Australia; with New Zealand that deficit was -US$0.4 bln in the month. Going forward, all this depends on how they react to the spreading pandemic.
In the US it is earnings season on Wall Street with some major fourth-quarter earnings coming from companies such as Bank of America, Goldman Sachs, Morgan Stanley, P&G and Netflix.
Elsewhere, central banks in Japan, China, Indonesia, Malaysia, Turkey and Norway will be reviewing policy rates this week. On Friday, the South Korean central bank made a rare back-to-back rate hike, adding another +25 bps to the policy rate and taking it to 1.25%. Inflation fears are driving these moves.
Back in the US, retail sales in December came in much weaker than expected after a flat November. And it was the largest month-on-month fall in ten months, but on a year-on-year basis it is up almost +17%.
Compounding that, US industrial production unexpectedly slipped in December from the prior month following a good rise in November. On a year-on-year basis it is +3.8% higher. Compared with pre-pandemic December 2019, it is +0.5% higher.
Completing the downbeat tone of the weekend US data, the UofM sentiment survey sank to a decade low as attitudes to current life are battered by the surging Omicron pandemic and a rising fear of inflation's impact on them. Three-quarters of consumers in early January ranked inflation, compared with unemployment, as the more serious problem facing the country.
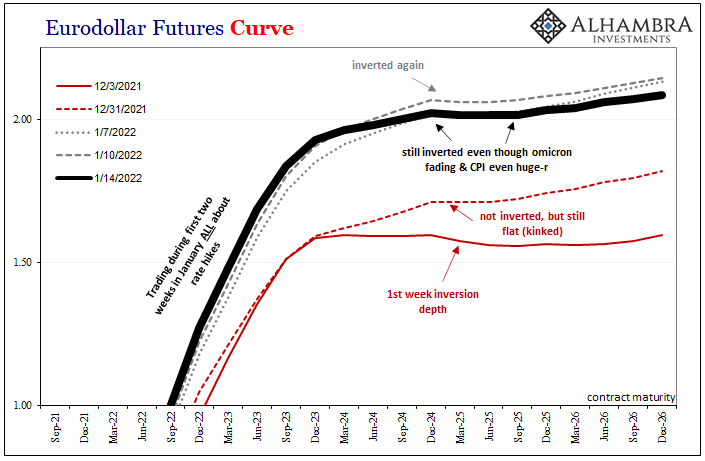
In American bond markets, funds are now flowing out in the expectation of Fed rate hikes in 2022. Holding bonds now risks capital losses. The high-profile boss of JPMorgan Chase, Jamie Dimon, said the weekend he expects six or seven Fed interest rate hikes in this cycle, based on the resilience of the US economy and American household balance sheets. But getting there will be turbulent for financial markets, he warned.
In Australia, home loans jumped +6.3% in November from October, mostly driven mostly by an improvement in owner occupier lending of +7.6%. But this probably won't be repeated for a set of reason, firstly the hit Omicron is taking, secondly the RBA's wind-back of its money printing, and thirdly rising mortgage interest rates ahead of an RBA change at some point.
In fact, labour shortages from Omicron stand-downs and scarcity of merchandise for sale are together likely to put plenty of pressure on Australian inflation levels and the RBA may well have to consider interest rate rises much earlier than they have previously signaled. Markets are starting to price that scenario in.
In NSW, there were 20,978 new community cases reported yesterday, a fall and a hope that they are topping out, now with 342,838 active locally-acquired cases (and undoubtedly an undercount), and 20 more deaths. Hospitals face serious staff shortages, and they have been told the number of COVID-positive people needing inpatient care could exceed 4500 within the month. They are now up to 2,650 having doubled in a week. More than half of all NSW ICU patients are unvaccinated. 17,791 pandemic cases in Victoria were reported yesterday, also a reduction even if small. There are now 237,559 active cases in that state - and there were 13 deaths. Queensland is reporting 17,445 new cases and 3 new deaths. In South Australia, new cases have held at 3,450 yesterday with 2 more deaths. The ACT has 1316 new cases and 2 deaths and Tasmania 825 new cases. Overall in Australia, 86,060 new cases were reported yesterday.
The UST 10yr yield opens today at 1.79% and up another +2 bps and a one year high. The UST 2-10 rate curve starts today slightly steeper at +82 bps. Their 1-5 curve is also slightly steeper at +106 bps, while their 3m-10 year curve is also steeper at +175 bps. The Australian Govt ten year benchmark rate is down -1 bp at 1.87%. The China Govt ten year bond is unchanged at 2.81%. The New Zealand Govt ten year is also unchanged at 2.47%.
The price of gold starts today at US$1818/oz and little-changed.
And oil prices start today firmer again, up +50 USc to just over US$83.50/bbl in the US, while the international Brent price is now just over US$86/bbl.
The Kiwi dollar will open today at 68 USc and dropping -¾c from Friday's brief spike. Against the Australian dollar we are firmish at 94.5 AUc. Against the euro we are holding at 59.7 euro cents. That means our TWI-5 starts the today at 72.3 and the same as where we opened a week ago.
The bitcoin price has moved up by +1.2% to US$43,411. Volatility over the past 24 hours has been modest at +/- 1.4%.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.