sign up log in
Want to go ad-free? Find out how, here.

Harold James explains what is really driving the Trump Administration's currency and bond-market interventions

Currencies / opinion
Harold James explains what is really driving the Trump Administration's currency and bond-market interventions
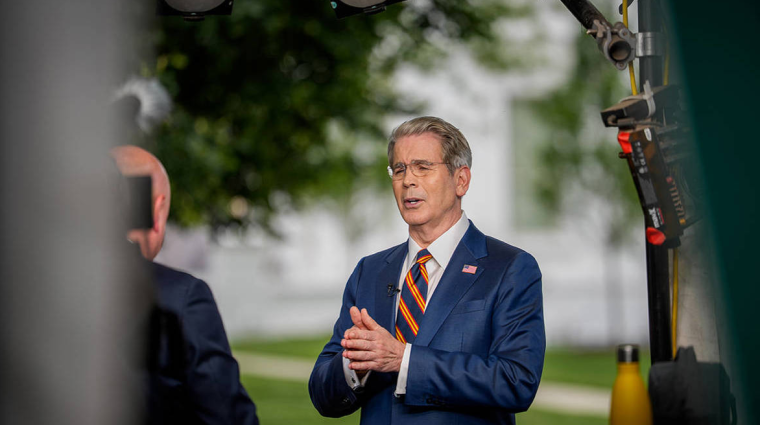
Scott Bessent, US Treasury Secretary

In a Reuters photo from late July, US Treasury Secretary Scott Bessent can be seen holding a to-do list with just one item: purchase $5 billion to $10 billion worth of yen. As he explained soon thereafter, invoking the famous phrase that then-European Central Bank President Mario Draghi used to save the euro in 2012, the Trump administration will do “whatever it takes” to prop up the Japanese currency.

Bessent’s public rationale for this surprise intervention was that the yen is undervalued, and that the US does not want to see a round of currency wars in which countries try to prop up their exports by undervaluing their currencies. Such conflicts do carry a powerful historical echo, given their role in destroying the world economy and threatening international peace in the 1930s. The victorious Allied powers organized the 1944 Bretton Woods Conference precisely to prevent the kind of protectionism and currency wars that had produced World War II.

But currency wars did return in the 1980s, when a surging dollar led Americans to believe that the yen (along with Germany’s Deutsche Mark) was undervalued. These suspicions then generated much academic research into whether currency interventions are effective. The overwhelming consensus was that they are not. A single intervention might move the markets for a short time, but in the longer run, economic fundamentals will reassert themselves and market pressures will return. The only enduring solution is to alter existing policy regimes.

Both in the 1980s and now, a Japanese effort to address underlying fundamentals would involve higher interest rates and perhaps also a fiscal contraction, with the US simultaneously lowering interest rates and issuing less debt (implying its own fiscal contraction). But neither side is likely to undertake such measures. Japanese Prime Minister Sanae Takaichi has made it clear that she thinks interest rates are high enough; and barring a dramatic economic downturn, lower US rates would only fuel stock-market exuberance and inflation concerns.

Exactly as economic theory would suggest, the yen has already started to fall again since its immediate post-intervention surge. More and more interventions will be needed to achieve Bessent’s desired exchange-rate effect, but markets will treat them with increasing skepticism. Since everyone knows how interventions play out, they are typically reserved for dramatic market situations. Not since the Fukushima disaster in 2011 has the US sold yen, and not since the height of the 1997–98 Asian financial crisis has it bought yen.

In any case, fears of currency and trade wars probably do not reflect the Trump administration’s real motive, considering that it has been openly following the 1930s playbook on tariffs. Nor should we believe Trump’s own explanation: that propping up the yen is a “signal of friendship” to a country that has “been very good to us, with the exception, of course, of Pearl Harbor.” Usually, the president’s measure of “friendship” is the trade balance—on the assumption that countries with a surplus must be taking advantage of the US. Yet US goods exports to Japan in 2025 totaled roughly $82.1 billion, while imports from Japan reached $149.8 billion.

For his part, Bessent has rather oddly mentioned other undervalued currencies alongside the yen, including the South Korean won and the Chinese renminbi. But if he cares about these currencies, too, he should support a big international currency reordering—a reworking of Bretton Woods. In reality, Bessent and Trump’s only genuine motive is to help the United States. In its August intervention, the US Treasury sold euros rather than dollars because it wanted to make clear that it would not approve of Japan (or anyone else) offloading US Treasuries.

The puzzle of why the US is so concerned with a falling yen has historical parallels not to the 1930s or the 1980s, but to the 1960s. At the time, the Bretton Woods fixed-exchange-rate regime, designed to prevent currency wars that could become real wars, was under increasing strain. Claims on the dollar were building up as a consequence of US military spending and investment abroad, but the country that was most vulnerable was the United Kingdom. Fearing a domino effect in which a financial crisis in the UK could trigger an attack on the dollar, US officials came to see the British pound as their “outer perimeter defense.”

The yen is playing the same role today. Japan’s government debt-to-GDP ratio is 248%, which looks like the limit to how much government spending is possible. The US figure is 122%, and bond yields have been rising throughout the summer, reflecting investors’ reluctance to purchase more government debt, the lure of AI investment, and America’s deteriorating fiscal situation (which was not helped by having to repay large sums collected for tariffs that have since been struck down).

Higher borrowing costs make life harder for the government (US debt service in 2025 consumed more of the budget than defense expenditure). They also raise mortgage, auto-loan, and credit-card rates, making voters more likely to turn against incumbents.

Seeing the writing on the wall, Bessent has already taken an even bigger gamble, intervening in bond markets to drive down the most politically sensitive long-term rates. But doing that requires more short-term issuance, which will push up the money supply and inflation. When markets realize how desperate the current and subsequent governments are, long-term rates will rise again, and Bessent’s bond excursion will have proven futile. It may already be happening: Following an initial boost to bond prices, a reversal appears to be underway.

Bessent wants to make debt look safe and cheap once more, but he is unlikely to succeed. He pursued a similar ploy late last year to weaken the Iranian currency, explaining that this would produce regime change without boots on the ground. Will people in countries that see the US as a menace consider a similar strategy and launch an attack on the yen and the dollar? One can think of worse ways to bring about regime change in Washington.


Harold James, Professor of History and International Affairs at Princeton University, is the author, most recently, of Seven Crashes: The Economic Crises That Shaped Globalisation (Yale University Press, 2023). Copyright: Project Syndicate, 2026, and published here with permission.

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

13 Comments

Japan’s government debt-to-GDP ratio is 248%, which looks like the limit to how much government spending is possible.

Apart from confusing a stock and a flow, this sentence highlights the challenges economists have with accounting. The Japanese Govt has a comparable net financial worth to other oecd countries and their earnings from their financial assets offset their debt servicing costs. The Govt also owns most of its own debt. They are in zero trouble and could comfortably expand the debt side of their balance sheet. 

There are very few Govts with a net positive financial worth. But we are one of them. We have managed it by running large private sector deficits for years to offset our current account deficits. In Japan, the Govt has run deficits and the country has run current account surpluses, which has enabled huge domestic private sector savings. 

Up
4

Unfortunately a big chunk of those savings (and return) resides in USD....and that is the problem.

Up
1

Why is it a problem? Do you think the US is going to refuse to settle them? 

Up
2

They have already put off settling an attempt to realise some (the recent event), however the instability of the US economy/institutions/leadership and the willingness to ignore the debasement of USD means that the USD is not a safe hold either by value or default risk....too many USDs and no or not enough takers....they (Japan) are stuck holding what increasingly nobody else wants or needs.

Up
2

You spot a crucial flaw in the standard narrative about Japan, Jonny. 

Focusing on their 248% gross debt-to-GDP ratio completely misses how their balance sheet actually functions. Yes, their massive holdings of financial assets and robust earnings offset their debt servicing costs comfortably. But this strength is deeply anchored by Japan's Net International Investment Position, which reveals them as a massive net global creditor.

Personally, apart from this one flaw, I found Harold James’s article to be a refreshingly realistic and non-nepotistical commentary. IMO, it is rare to see that level of sharp, unaligned critique from a Princeton-based academic. He explicitly identifies that Washington is trying to use Japan as an outer economic defense perimeter. 

This highlights a deeper, unresolved issue regarding true economic sovereignty. For the last 80 years, Japan has rarely been permitted to craft a genuinely independent fiscal and monetary policy with their occupier constantly breathing down their neck. True stability will only come when Japan can act principally in its own sovereign interest.

Which brings us to the fascinating contrast between the US and Japan regarding fiscal dominance. Japan is in a state of mild, deeply insulated fiscal dominance. Because roughly 88% of their debt is held domestically in their own currency, the risk of a sudden crisis is effectively zero. 

The Bank of Japan can manage a slow-burning equilibrium of financial repression because their massive domestic asset base and world-leading net-creditor status act as a massive structural shield.

The US, on the other hand, faces a far more volatile and debilitating flavour of fiscal dominance. Unlike Japan, America relies heavily on the willingness of global markets to fund its deteriorating fiscal position. 

With US debt servicing now consuming such a huge portion of the federal budget, Scott Bessent is forced to take desperate gambles - such as intervening in bond markets to artificially suppress politically sensitive long-term rates. This required short-term issuance will actively push up the money supply and feed inflation, further highlighting the minuscule purchasing power of their fiat debt-instrument-based currency. 

When the global markets fully realise how cornered Washington is, US long-term rates will surge, exposing the ultimate futility of their position. America is trapped by global market sentiment, while Japan is anchored by domestic wealth.

I agree with you to on NZ's true financial quagmire. While our headline public debt looks low by Western standards, our Net International Investment Position is appaling. We run massive net international liabilities because we rely heavily on foreign capital to fund persistent current account deficits.

Unlike Japan, we have achieved a cleaner government balance sheet by running large private sector deficits for years. This shifts the systemic vulnerability directly onto New Zealand households and businesses. 

We are deeply exposed to the whims of foreign lenders. The common narrative deployed by the status quo cheerleaders is to trumpet our low public debt position in order to claim that our economy is not in deep trouble - this completely ignores our deeply entrenched structural crisis.

How on Earth do we think New Zealand can realistically fix this deep reliance on foreign capital without crushing domestic private savings even further?

The fundamental differences becomes even clearer when you look at the stark contrasts in societal and household savings behavior across the US, New Zealand, and Japan. 

In Japan, decades of a current account surplus have allowed the country to amass a colossal pool of private domestic wealth, meaning the government borrows directly from its own thrifty citizens. 

The United States exhibits a hyper-consumption culture where the household net savings rate sits at a meager 4.9 percent, leaving the state reliant on selling its debt to foreigners. New Zealand sits at the absolute bottom of this spectrum. 

According to OECD data reported by RNZ, New Zealand recently recorded a negative net household savings rate of -1.3 percent, meaning Kiwi households are actively spending more than they earn. 

While Japan’s government debt is cushioned by massive domestic savings, New Zealand's low public debt hides a private sector that is entirely starved of savings and deeply indebted to external lenders.... and the beat goes on.


Up
5

This article and the comments are really quite informative to me. Thank you

Up
5

The fact that the Japanese govt owns a lot of its own debt is not a good thing and they are not in zero trouble.  Engaging in money printing and buying your own debt like Japan has only lasts while you can support the global financial system.  

The following is along the lines of the above article.

https://www.youtube.com/watch?v=_i-MswQoweE

The TRUTH About Why America Bailed Out Japan

On the last day of July, the United States did something it had not done in 28 years: it walked into the currency market and spent billions rescuing another country's money. The White House called it friendship. Governments do not spend tens of billions on friendship, and Treasury secretaries do not say "whatever it takes" about things that don't let them sleep at night. The real story runs through Tokyo. Japan is America's banker, holding over a trillion dollars of U.S. Treasuries, and its collapsing currency forced Washington into a corner: rescue the yen, or watch American borrowing costs spiral just as the 30-year yield hits its highest level since 2007. The machine Washington built for the job reveals exactly what the people running the system fear most. It is not the yen - it's a falling US bond price.

Up
1

Japan has kept debasing its currency and as result the citizens are effectively getting poorer. Japan is one of the few top oecd countries we can go to with NZ pesos and it seems cheap. The poor Japanese aren’t happy with influxes of overseas tourists. Go to any Japanese ski field and it’s full of Aussies and Kiwis. There is a cost.

The USA is following a past historic trend of trying to move the long term cost down as it gets further into debt. This will just keep weakening the US dollar and they hope that theres no where else to go.

We have seen a near 30% real drop in property values on average post COVID and many finding their equity decrease in NZ. Many of our export industries are doing ok, companies reporting not bad results.

Maybe we are witnessing the pain of not being able to rely simply on ever increasing house prices and how reliant so many were on this.


Up
1

Japan has kept debasing its currency and as result the citizens are effectively getting poorer. Japan is one of the few top oecd countries we can go to with NZ pesos and it seems cheap.

While that might appear to be the case, broad money growth in the US, Anglosphere, and EU has been far greater than in Japan. So arguably their respective currencies should be weak in terms of store of value and in purchasing power. 

Do you think Aotearoa citizens became richer because house prices have increased because of the Ponzi? Or is this just a result of broad money growth?

Up
0

Probably both and lots of new people arriving causing "growth" here.

Japan hasnt had population growth and in fact is shrinking in size - cheap houses outside big urban areas. Remember the 70s and 80s when Japan was going to take over the world.

I have suspect this demographic change is driving a lot of change in ways we have not seen for centuries. Will China be the next Japan in 30 years as they start to lose numbers and age?

For all the angst about immigration the US, and Oceania, are likely to keep adding new souls over time which by default will keep demand going in some form.


Up
0

Japan has gone through many periods of JPY strength to their own dismay. For ex, 2007-2012, ranging from about ¥122 to a record intraday ¥75.31. Even during the Covid period, JPY almost reached par with USD. 

The future demographic challenges facing Japan were known as far back as the 80s.  

So I don't buy the idea that demogs driven JPY value. Nor do I buy that Aotearoa and Aussie are superior economies because we can open the gates. 

Up
0

I certainly don’t see NZ as superior. How do you explain their currency fall?

I think demographics will play a major role in economies going forward and no one can know how exactly as we haven’t experienced it before. Less people and older ones will change total volumes of stuff needed and the type of stuff.

The post 1945 world order is rapidly maturing.

Up
1

I certainly don’t see NZ as superior. How do you explain their currency fall?

Partly by design. Most East Asian governments seek a beneficial exchange rate - one that sustains export competitiveness and macroeconomic stability - rather than simply the weakest possible currency. And remember what the Plaza Accord was about: to address an overvalued dollar. The U.S. considered Japan to have unfair advantage because of a weaker yen.

Up
0