

Here are the key things you need to know before you leave work today (or if you already work from home, before you shutdown your laptop).
MORTGAGE/LOAN RATE CHANGES
Harmoney has raised rates today on personal loans.
TERM DEPOSIT/SAVINGS RATE CHANGES
None here today.
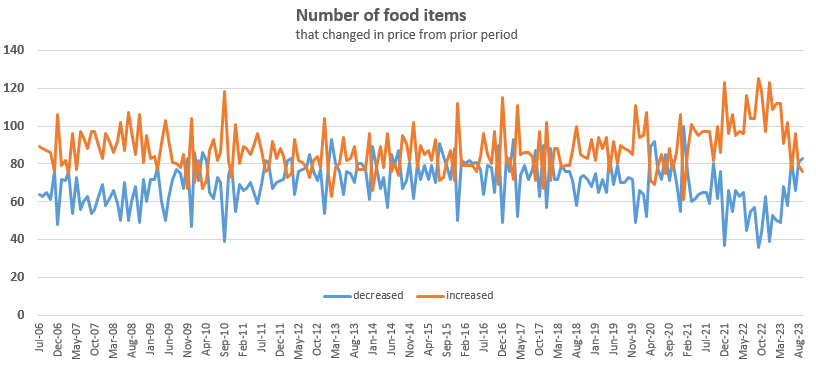
FOOD PRICE PRESSURE EASES
Food prices actually dropped in October, dragging the annual increase back to +6.3%. That is down from +8.0% in the year to September, and they peaked on this basis at +12.5% in June 2023. Stats NZ says food prices 'fell across the board in October'. Tracking food price changes shows that for the first time since 2020 we now have more items decreasing in price than increasing. (A click on that second link shows it clearly.)
CAPITAL GAINS RETURN
QV says the average value of NZ homes is up by more than +$18,000 in the last 3 months. Property values are slowly rising in most regions with the biggest increase occurring in Auckland, where they were up more than +$33,000 (+2.7% in the quarter).
FOR CAR INSURANCE, SHOP AROUND
Consumer NZ surveying has found premiums for comprehensive car insurance have increased up to +38% since 2021. Cyclone Gabrielle occurred during this period resulting in heavy claims. Shopping around, especially when you are focused on coverage and conditions, may also be able to deliver lower premium costs. Consumer NZ found that switching car insurance providers could result in a family of four saving up to $670 a year on average. But be careful about just targeting premium cost - you may be giving up important coverage for those benefits. (Just for perspective, our largest general insurer's gross written premiums went up +12% in 2023 from 2022 which were up +7% from the prior year. So car insurance premiums rose faster than that overall. In fye 2023 IAG group tax paid profit was AU$832 mln. In fye 2020 IAG tax paid profit was US$435 mln.)
DTI RATIOS STILL DROPPING
Latest quarterly Reserve Bank figures show that ahead of the possible introduction of debt to income restrictions next year, new buyers are, in any case, mostly borrowing on low DTI ratios
HIGH HOUSEHOLD INCOMES REQUIRED
The average gross incomes of borrowers taking out a mortgage in September are rising. In September 2021, owner occupiers borrowing for their own house with a DTI ratio of between 4 and 5 had a gross household income of $144,000 on average. In 2022 it was up +21% to $175,000. And now in September 2023 it is up +13% to $198,000. For first home buyers the increases have been much more modest; the same 4-5 DTI cohort required a $131,000 gross household income in 2021. That was up less than +5% to $137,000 in September 2022. And now it is up to $146,000 in September 2023, a further rise of +6.6%. Those with gross incomes of $65,000 in 2023 got their mortgages on a DTI of 3, obviously having to have large deposits.
UP BUT TO WHERE?
The RBNZ says it is 'building towards a higher level of foreign reserves holdings now.' But Assistant Governor Karen Silk says there is no clear answer to the question of what the right level of foreign currency reserves the RBNZ should hold is.
SETTLEMENT BALANCES STAY UNUSUALLY HIGH
Bank settlement balances were $49.2 bln as at October, little-changed from the $49 bln a year ago. But that is six times higher than five years ago. They peaked at $56.4 bln as at December 2022. Remember, the RBNZ pays banks the OCR as interest on these balances. Over the past year, that amounted to $2.487 bln or 30% of the profits banks earned in that period
SENTMEMENT SAGS
In Australia, the widely watched NAB business confidence index fell to -2 in October from a downwardly revised flat reading in the prior month, pointing to the lowest level since May. However business conditions edged up.
BACK TO LESS THAN A DECADE AGO
Australia released its September short-stay visitor arrivals data today and they are still not back to 2013 levels yet, struggling to get to levels that existed a decade ago. They were 584,000 in the month, and the largest source was New Zealand (22%), followed by China (10%), then the USA (6%). Interestingly, short term tourists from New Zealand made up 22% of their September 2013 level as well. But tourists from China made up 12%. From the US 7%. So same basic mix, just less from everywhere.
SWAPS ON HOLD
Wholesale swap rates have probably changed little today. The real reaction will come at the close. Our chart will record the final positions. The 90 day bank bill rate is up +1 bp at 5.63% and now just +13 bps above the OCR. The Australian 10 year bond yield is up +1 bp from yesterday to 4.68%. The China 10 year bond rate is unchanged at 2.67%. And the NZ Government 10 year bond rate is up just +1 bp at 5.26% from yesterday, and the earlier RBNZ fixing was at 5.18% which was also up +1 bp today. The UST 10 year yield is now at 4.65% for a -1 bp dip from this time yesterday. The UST 2yr is now at 5.05% so that curve inversion is little-changed at -40 bps.
EQUITIES TURN BACK UP
The NZX50 is up +0.3% in late trade today. The ASX200 is up +0.7% in afternoon trade. Tokyo has opened up +0.6%. Hong Kong has opened up +0.3% and Shanghai has opened up +0.2%. The S&P500 ended little-changed on Monday.
GOLD STABLE
In early Asian trade, gold is now at US$1945/oz and up +US$5 from where we were this time yesterday. Earlier in New York it was at US$1946/oz and earlier still in London at US$1931/oz.
NZD SOFTISH
The Kiwi dollar has moved little today, still at 58.8 USc which is close toe where we were this time yesterday. But against the Aussie we are almost -½c softer at 92.2 AUc. Against the euro we are also a little softer at 55 euro cents. That means the TWI-5 is down -20 bps at 68.6.
BITCOIN FALLS
The bitcoin price is weaker today, now at US$36,387 and down -2.2% from where we were this time yesterday. Volatility over the past 24 hours has again been modest at just over +/- 1.5%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs

This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.