sign up log in
Want to go ad-free? Find out how, here.

A review of things you need to know before you sign off on Tuesday; Rabobank raises longer TD rates, NZIER survey finds optimism ahead, consumer spending weak & stressed, NEVs rule, swaps rise, NZX firmish, NZD holds, & more

Economy / news
A review of things you need to know before you sign off on Tuesday; Rabobank raises longer TD rates, NZIER survey finds optimism ahead, consumer spending weak & stressed, NEVs rule, swaps rise, NZX firmish, NZD holds, & more

Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).

MORTGAGE RATE CHANGES
WBS (Wairarapa Building Society) has added a three year fixed rate offer, of 5.75%. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.

TERM DEPOSIT/SAVINGS RATE CHANGES
Rabobank increased its TD rates for all terms 18 months and longer. WBS has also launched a three year TD rate at 4.55% pa. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.

BUSINESS CONFIDENCE (ABOUT THE FUTURE) SURGES
The Q3 NZIER survey finds business optimism bounced back during the quarter as firms expect stronger economic recovery over the next 12 months. However they report patchy conditions here and now as an increasingly number of firms bemoan a lack of sales currently.

WEAK & NOT GETTING BETTER
Consumer spending continued to run below year-ago levels in August and September, as consumers coped with rising petrol prices, rising interest rates and bad weather. That is according to Paymark who said their transaction data shows September  reaching only $3.6 bln, which is down -1.3% from the same month a year ago. Remember, their data does not adjust for inflation (4.1%)

RISING FASTER THAN INCOMES
That was followed by ANZ's card tracking data for September, also released today. It was up +0.5% from August, to be +5.8% higher than the same month a year ago. Annual spending growth is positive across all groups. But much of this is because spending at service stations was up +2.8% in the month as fuel prices lifted, up +14.2% for the year. Spending at second-hand stores is also lifting strongly, in contrast to a sharp fall when oil prices first jumped. Spending on public transport was up +10% from a year ago.

NEVs RULE
Yesterday we noted the high level of new car sales in September. But we missed an interesting point of context. More than 70% of those new cars sold were NEVs, that is EVs or hybrids. That level has been climbing sharply recently, and was only exceeded once in the past - in December 2023, the last time you could get a government subsidy. It does rather prove the point that the subsidy wasn't actually needed. Buyers will buy if the features justify it.

THINGS GETTING TIGHT
With only 32 days until the general election, the polls and debates are coming thick and fast. The latest one seems to have the Nats atrophying quickly in a slide that must be worrying them - especially given the NZIER survey today. There are now only 11 percentage points between them and the Greens in this poll. Ouch.

TOWER INCREASES ITS FULL-YEAR PROFIT GUIDANCE
General insurer Tower has raised its full-year underlying net profit after tax guidance for the September year to be between $69 million and $79 million. This is up from its previous guidance range of $55 million to $65 million. According to Tower, the uplift reflects the insurer’s $45 million large event allowance not being fully utilised during the 2026 financial year, which meant Tower returned to a more “typical earnings profile”. Tower will release full details of its FY26 performance with its financial results announcement on November 26.

NZX50 FIRMISH
As at 3pm, the overall NZX50 index is up +0.2% so far and also up +0.3% for the past 5 trading sessions. It is up +5.1% from six months ago. From a year ago it is only up +1.8% now. Market heavyweight F&P Healthcare is down -0.1% so far today. Gentrack, EBOS, Property for Industry and Tower gain whil Serko, a2 Milk, Sanford and Hallensteins decline.

LOOKING AHEAD TO TOMORROW'S GDT AUCTION
Tomorrows full dairy auction, the first since September 15, is likely to bring mixed results although generally higher in USD. The WMP and SMP prices should be up by about +4% from last week's Pulse event. The milkfats (butter, AMF, etc) might well be quite soft, down about -5%.

"WORST SINCE THE EARLY 1990s"
In Australia, the Westpac-Melbourne Institute consumer sentiment survey for October makes grim reading too. This is how they introduced these results: :"Australian consumers remain stuck in a cost-of-living nightmare that seems to have no end in sight. At just over 80, the latest sentiment Index is amongst the forty worst reads since our monthly survey began in the early 1970s. We have had two others in this unfortunate group already this year – in April and June – with another eight recorded in 2022–23. Altogether this marks the worst period of recurring extremely weak sentiment since the disastrous recession in the early 1990s."

A RECORD NOW WITH INTENSIFICATION TO COME
And just so you know, El Niño is now at near-record levels. Both oceanic and atmospheric indices reflect values consistent with a strong El Niño, with further intensification forecast during the rest of spring (that is, until the end of November).

SWAP RATES RISE
Wholesale swap rates will likely be firmer today, maybe up as much as +5 bps. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was softer by -1 bp at 3.22% on Monday. Today, the Australian 10 year bond yield is up +11 bps at 5.41%. The China 10 year bond rate is now at 1.68% and unchanged. The Japanese 10 year bond is now at 3.12% and up +3 bps. The NZ Government 10 year bond rate is now at 5.12% and up +4 bps from this time yesterday. (The RBNZ 10 year rate is 'prior day' and was down -1 bp at 5.04% on Monday.) And the UST 10yr yield is now at 5.32% and up +7 bps from yesterday. That last time it was this high was in 2002.

EQUITIES MOSTLY FIRM
The NZX50 has firmed +0.2% from Monday's close. The ASX200 has opened up +0.7%. Tokyo is up +0.2%. The KOSPI is down -0.5% today. Hong Kong is up +0.7% in Tuesday trade while Shanghai is still closed for their public holidays. Singapore is down -0.3% in early Tuesday trade today. Wall Street ended its Monday trade with the S&P500 up +0.7% and the Nasdaq up +1.1%.

OIL PRICES SLIGHTLY SOFTER
American oil prices have eased -80 USc from this time yesterday with the WTI benchmark now at just over US$89.50/bbl, while the international Brent price is just under US$100.50/bbl and down -US$1 despite the renewed Middle East uncertainties.

CARBON PRICE HOLDS
After yesterday's flurry of trades, today there are veery few. The price remains little-changed at $52/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.

GOLD DIPS SLIGHTLY
In early Asian trade, gold has fallen almost -US$20/oz from this time yesterday, now at US$4140/oz. Silver is down -50 USc at just on US$61/oz.

NZD HOLDS SOFT
The Kiwi dollar is still  just under 56.1 USc and little-changed from where we were this time yesterday. Against the Aussie we are also down -20 bps at 80.4 AUc. Against the euro we are still unchanged at 49.9 euro cents. This all means the TWI-5 is is now just under 59.8 and down -10 bps.

BITCOIN DIPS
The bitcoin price is now at US$85,876 and down -0.8% from yesterday at this time. Volatility has been modest at just under +/- 1.1% again.

HOW THE GLOBAL ECONOMIC FORCES AFFECT US
If you want to catch up on what happened last night, try our Economy Watch podcast, here.

Daily exchange rates

Select chart tabs

Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: CoinDesk

Daily swap rates

Select chart tabs

Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA
Source: NZFMA

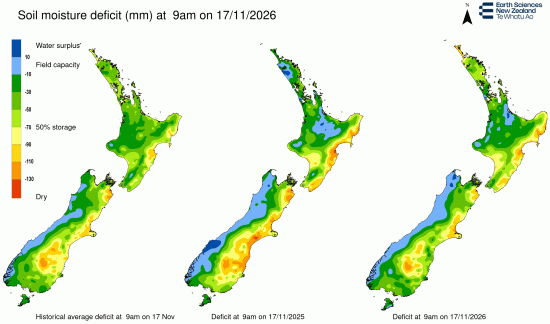
This soil moisture chart is animated here.

Keep abreast of upcoming events by following our Economic Calendar here ».

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

44 Comments

Firmus Technologies, an Aussie AI-infrastructure and cloud-services company, builds and operates specialised data centres that provide the computing capacity needed to train and run AI models.

Founder Oliver Curtis was found guilty of involvement in a conspiracy to commit insider trading and jailed in 2016 (now free). Firmus’s proposed IPO values its equity at approximately AUD43.7 billion.

The company just missed its first rent payment. 

https://www.afr.com/rear-window/firmus-missed-first-rental-payment-to-d…

Up
2

Do you have a private AI account on monthly subscription?

I just joined Anthropic USD $20 per month sub, all to get Opus 5.5

Once people realise how much AI could save them for example let ai log into your electricity provider and then search for better deals etc


Up
0

I am a Perplexity Pro subscriber and I buy tokens for Perplexity Computer. I'm also connected to Alibaba Cloud and JDI, but don't use any of their tools, even though they send my invitations to use for free. 

Up
0

look to inkbox.ai  for email and messaging txt type integration free level, not sure if perplexity have a chrome extension?

many sites block bots direct login, but local chrome xtnsion bypasses.


Up
1

I don't use Chrome for various reasons, including ethics. I use Brave. Perplexity has an “AI data retention” toggle to reduce how queries are used for training.

Up
0

Can you give Babs a lend of your ai login?

“This isn’t some complicated forecasting dispute. Labour seems to have taken the Government’s own numbers and forgotten to reverse the signs when undoing their policy, turning a $44.8 million cost into a $44.8 million saving.”

“Hiding behind the defence that its costings were reviewed by consultants no longer holds water. We saw an almost identical problem with the Greens getting confused by negative numbers in their tax plans, and those numbers were externally verified too.”

https://x.com/TaxpayersUnion/status/2107260390342082970

Up
1

"prove the point that the subsidy wasn't actually needed. Buyers will buy if the features justify it."

Hmm, is that the best way of looking at the EV situation? I mean if the subsidy had remained in place, there would be many more EVs on the road by now without doubt, carving a huge chunk off NZ's trade deficit. Service and retail spending probably wouldn't have fallen off the cliff to the same dire extent? Not to mention the environmental benefits of the CO2 emissions that could have been avoided if the measures had stayed in place. 

"transaction data shows September  reaching only $3.6 bln, which is down -1.3% from the same month a year ago. Remember, their data does not adjust for inflation (4.1%)"

Penny wise, pound poor......

Up
4

Agree, EV sales dropped significantly when the discount was removed. Price will always be a factor in people's decisions. And old school hybrids are still an ICE vehicle, just a slightly more efficient one. 

Up
1

Yeah I think that conclusion from David was a stretch. What it shows is that making oil more expensive by blowing up a region makes people seek alternatives to oil. 

Up
3

there would be many more EVs on the road by now without doubt

I don't really buy this. People were enticed by the subsidy, but the reality being that even without it, the numbers stack up for mass savings over time with EV's, and at the time lots were being sold, we were still in the rockstar economy stage, fuelled by people hocking their houses for obscene money, so many had money to burn on these things. EV's are still selling as with the cost of fuel and risk of this for some time to come, or worse, it seems a logical investment for many too.
It was clear that the subsidy, once announced, resulted in the manufacturers simply increasing the pre-import price by the same amount to bolster their profits, which didn't benefit the NZ public.

Up
0

Blimey - the US 10-year Treasury is now at 5.32%, up another 7 basis points, while the largely unmentioned 30-year is lurking around 5.67%.

Across the Atlantic it gets even more alarming.

The UK 10-year is around 5.4%, while the 30-year has been flirting with 6% - territory Britain hasn't seen since the 1990s.

And then there's the lovely little Threadneedle Street secret - on September 17, as long-dated gilt yields surged towards levels last seen in 1998, the Bank of England halted active sales of long-dated gilts and paused its open-market QT auctions.

Better still, the BoE now intends to sit on around £120 billion of its longest-dated gilts - including bonds running all the way out to 2071 - rather than sell them back into the market. Another £222 billion of shorter gilts maturing before 2035 can simply roll off naturally.

In other words, just as Britain's long end begins to smoke, Threadneedle Street decides this might not be the ideal moment to dump another more long-duration government debt onto the market.

France isn't looking much prettier. Its 10-year is around 4.9%, the 30-year around 5.5%, sovereign CDS have blown out dramatically, and markets are now charging France more than Italy across important parts of the curve.

Remember when Italy was supposed to be Europe's problem child?

Tonight, when London and Europe are properly underway, watch the French and Italian spreads, CDS and long bonds - and particularly those British gilts.

The global sovereign bond market appears to be repricing risk in real time.

Nothing to worry about, folks, cough, sputter - and whatever you do, try not to talk about Threadneedle Street.

Up
1

Then add this to the mix...

"We know the diesel crisis is but one of many — from sovereign debt to unwinnable wars. A bond market can be stabilised. Supply chains can be rerouted. Nations can be reindustrialised. Wars can be ended. But is anyone predicting that will happen soon?

Every day they go unresolved the risk compounds. The longer they run, the more certain an economic depression becomes — only on a scale humanity has not seen in a century."

https://fountainbridge.substack.com/p/diesel-rationing

Up
1

I've been pointing out the inevitability of us being in this predicament, for 20 years, on this site. 

Maybe not by this exact pathway, but inevitable it was. Always. 

Up
3

I drove my first long distance trip (900 km) with my new EV over the last weekend, down past the desert road from Auckland and back.  After being a petrol head my whole life, I can now say that I will never own another ICE car.

Up
7

was it self-driving?    another WTF moment, I am ready for a self-driving Ford Ranger EV now


Up
0

Not fully self driving, the NZ law doesn't allow it yet.  What do you mean: "another WTF moment" ?

Up
0

Tesla self drive means you just have to be ready to take control... its very good


Up
0

It will still be working as a piece of infrastructure, beyond the collapse. 

Interesting to be in this late phase and contemplate the ramifications. 

Up
0

How many charges?

Up
0

2 charges, each took about 25 minutes, which was quicker than the 45 minute lunch break we had.

Up
1

But does it have a spare tyre? I was amazed that most EVs don’t. You have a puncture and you have to call the people at Tesla to send you out a “loan” tyre which could take up to 2 hours. 

Up
2

Presumably with a jack and wheel brace.


They do (well they used to) have a puncture repair product alone with a small 12v air compressor, which should cover most punctures (so long as the driver doesn't just keep driving on the flat tyre).

Up
0

The New York Fed has been visiting and reviewing major banks’ lending to private-credit firms since spring 2026. "Big banks": JPM Chase, Wells Fargo, Barclays and Morgan Stanley.

It signals closer scrutiny of the links between banks and private credit. This is a meaningful warning that supervisors want to test whether private-credit valuations and bank lending safeguards can withstand deterioration. But the reported visits are not themselves an enforcement action, a declaration of insolvency or proof of losses.

https://www.semafor.com/article/10/05/2026/private-credit-worries-spur-…

Up
1

Fed is getting a whiff of GFC hidden debt.

Up
1

I was commenting on another site about how I am surprised no party has contemplated the most obvious fix to the cost of living, taking GST off food. And before you say its impossible or stupid:

  • “In Australia, basic food staples are generally exempt from the 10% Goods and Services Tax (GST), while processed, hot, or restaurant-consumed foods are taxable”
  • “In the United Kingdom, most basic grocery food is zero-rated (0% VAT), while hot food, catering, and luxury items carry the standard VAT rate of 20%”
  • “The United States does not have a federal Goods and Services Tax (GST)”
  • “In Ireland, Zero Rate (0%) applies to most basic foodstuffs sold in retail shops, including fresh meat, milk, vegetables, bread, and cold takeaway food”
  • “Basic groceries are taxed at 0% (zero-rated) nationwide in Canada”
  • "France applies three main Value Added Tax (VAT)—referred to locally as TVA—rates to food and beverages, ranging from a reduced 5.5% to a standard 20% depending on the item and how it is sold"
  • "In Germany most food products qualify for a permanently reduced VAT rate of 7%, which is designed to make staple items affordable. This stands in stark contrast to Germany's standard VAT rate of 19%, which applies to non-essential goods, electronics, alcohol, and general services."
  • "In the Netherlands, all food and non-alcoholic drinks are taxed at a reduced VAT (Value Added Tax, comparable to GST) rate of 9%, whether bought in a shop or served in a restaurant."
  • "Japan's consumption tax (similar to GST) applies a standard rate of 10% to most goods and services, while food is generally taxed at a reduced rate of 8%, though a temporary reduction to 1% for grocery food and takeout is scheduled to begin in April 2027."
  • “New Zealand charges a standard 15% Goods and Services Tax (GST) on almost all food and non-alcoholic beverages, with no exemptions for basic staples or fresh produce”

I struggled to find a country that didn't do it. Singapore is similar to us although only 9% across the board. 

I asked AI to compare OECD countries: "New Zealand's 15% GST on food is structurally unique and effectively higher than the vast majority of OECD countries."

No wonder people are struggling to put Kai on the table. 

Up
0

It's certainly possible, but it would as considerable complexity, inefficiency and therefore cost to the system. Better to just reduce taxes on low earners.

Up
8

The problem is that once the retailers have established what prices their customers will pay then those same prices will be ratcheted back up. Think about it. What prices at your supermarket actually reduced back to those pre-existing before covid, and when supply chains returned to normal. Same applies to local body rates, take away the GST  surcharge, and the councils will simply swoop in and claim the 15% for themselves, because ratepayers are proven to be able to afford it.

Up
3

Its a low margin cost plus industry. You cant add 15% to your margin and get away with it, competitors will come out of the woodword. Our supermarkets currently are 1% more profitable than others and we are out to get them, they couldn't get away with 16%

Up
0

You haven’t thought about it. Supermarket prices such as bread have bounded past 15%. Take 15% off and what’s to stop that being reestablished and given the current political dithering and posturing over supermarket operations and pricing, where exactly is that white knight competition to emerge from.

Up
2

Take 15% off and prices are 15% lower than now. 

Up
0

That is very true. For exactly how long though? what was costing you $115.00 is now $100.00. But the retailer knows you are capable of  paying $115.00. The market will yield that price.  What exactly stops the retailer for putting that price  back on the shelf. Perhaps without too much indecent haste. Or are you advocating imposing simultaneous price controls such as Rowling’s ill fated MRPs or Muldoon’s ludicrous freezes. 

Up
2

The fact that another retailer could sell it cheaper. 

By your argument we may as well raise GST to 100% and no one could increase their prices as they are set at what people can afford. 

These seem like the same old excuses for having GST on food. Can you honestly say our food should be the same price as other countries even with a 15% tax on top? How is that possible unless other countries supermarkets are making 15% more margin than ours? 

Up
0

Para 1. The fact is that NZ’s two major supermarket chains control 80 - 90% of food sold at retail. 

Para 2. Is nonsensical.

Para 3. Is irrelevant.

Up
2

So 15% GST is a magic number, lowering it would not reduce prices but raising it would. 

Up
0

“but raising it would? Blimey, that’s rather weird. Entirely your suggestion.  Can’t imagine  anyone else coming up with it.

Up
1

Take GST off of food and you'd see a price drop immediately we presume, but supermarkets can charge whatever they wish for their goods, and thus they would ratchet the price back up soon thereafter as they already have the information of what people are willing to pay, and a lot were willing to pay with GST on anyway. Those supermarkets rewards cards are simply to gather your purchasing data and use it to price goods to extract more profit from you, not for your own discount or good. So no, taking GST off of food would not, longer term, result in much of a saving. It would only bolster the profit margins of the supermarkets and there is nothing at all that the public could do about that.

Up
2

Will be an interesting leaders debate tonight. I suspect it will be more a case of who loses the least votes to a "minor" party. 

Up
1

Luxinda has the mad cat ladies vote cornered with his $664k middle eastern kitten doco funding. The white anting public service must be laughing.

https://x.com/TaxpayersUnion/status/2107184267172229263

Up
0

Cluxon, in my opinion, is on the verge of anointing himself, as the most dismal failure of a prime minister that NZ has ever witnessed post WW2, and likely before. It is beyond belief that the National Party has clung on to his ever growing ineptitude, like a clutch of blind mice, when NZ needed a degree of substantial and forthright leadership. 

Up
4

herald poll has him as winner?

Up
0

Stuff poll has him as loser! It is all so utterly predictable that it is laughable. May as well send in the clowns and we can all have a proper laugh,  performed by professionals. 

Up
1

Will be an interesting leaders debate tonight

No it won't

Up
1

NZ Election.... one word

P O L Y M A R K E T


Up
0