Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
Kiwibank has announced fixed home loan rate changes but they either only match their main rivals (the short ones) or they stay well above them (the long ones). ANZ have added 4 year and 5 year 'specials' (minimum 20% equity) but in fact these two 'enw' rates aren't very special or competitive. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
No changes to report today. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
CAPITAL GAINS BECOMING CAPITAL LOSSES
One-in-four Auckland residential property sales were made at a loss in September quarter. The number of residential properties being sold at a loss continues growing, with almost half of the apartments sold in the third quarter selling at a loss
RISING, BUT THE LOCALS ARE UNHAPPY
In the September year there was a net population gain of +22,611 from migration in September year. That is a level similar to the years 2005 to 2013. In the same year to September 2025, the net gain was +12,700. But despite that, we need to note the loss of NZ citizens which has now topped -64,000 in the current September year.
RISING QUICKLY
The pace of inbound tourism is rising, aided in large part by the weak NZD. Arrivals from Australia are now +6% higher than pre-pandemic levels, and real impetus is being added by arrivals from China. While these are not yet back to pre-pandemic levels, they are now recovering very quickly. Overall, inbound tourism is up +9.8% from year-ago levels. We will likely see an impact of this in the Q3-2026 GDP result.
A GRIM START TO THE END OF YEAR RETAIL PERIOD
October retail sales were disappointing with a broad-based reduction as measured by tracking electronic card transactions. While spending on fuel jumped (+4.8%), that is being 'paid for' by sharpish cutbacks in discretionary (-1.6%) and durables (-2.1%) spending, and more so when you adjust for inflation. Wallets are still shut and retailers will be hoping for some Black Friday and Christmas season shopping relief. Things are not starting from a great position.
BRUISED BUT SOLVENT
The insurance industry regulator, the RBNZ, instructed the bulk of the health and life insurance sector to do stress testing. They required participating insurers (about 70% of the sector) to identify severe but plausible scenarios that threaten their business model and then identify potential responses. The results of this 'reverse stress testing' has brought changes in the way some of them operate, and confirmed they would all survive and their clients not be affected. The type of stresses anticipated included combined pandemic shocks with reinsurance disruption or investment losses. Some also considered cyberattacks and operational disruption.
NZX50 FIRM
As at 3pm, the overall NZX50 index was up +0.5% today. From a week ago it is now up +1.1%. From six months ago it is up +9.0%. From a year ago it is up +4.2% now. Market heavyweight F&P Healthcare little-changed so far today. There have been 52 gainers led by Mainfreight, The Warehouse, Investore and Lodestone Energy. There have been 22 decliners led by Oceania, Scales, Meridian and Briscoes.
HEALTHY APPETITE I
The results of ASB's 5 year bond sale are in and they took $700 mln of over-subscriptions on top of the $100 mln they said they were seeking. It will yield 4.782% per annum.
HEALTHY APPETITE II
There were 79 bids for today's $450 mln NZGB bond tender of two maturities and those bids totaled almost $1.95 bln. Twenty-two bids won some allocation. Yields were -35 bps lower than at the prior equivalent tender of the May 2031 bond three weeks ago but little different for the April 2037 bond with was tendered only last week.
PUSHED BACK
Heartland has extended its TSB takeover deadline to March 2027 as TSB’s capital and liquidity ratios review is still ongoing and the Reserve Bank needs more time to assess the proposed TSB-Heartland merger.
NOT NEEDED
Japanese producer prices have been increasing at above a +7% rate since since May and June. They were expected to start trending lower with analysts expecting an October rise of +6.5% (year-on-year, +0.3% from September). But in fact they rose, up +7.1% from a year ago, up +0.7% from the prior month. This is not a good signal.
NO RELIEF EXPECTED
Australian inflation expectations stayed a very high 5.3% in November according to the widely respected Melbourne Institute survey. (The same survey showed wage expectations weak at +1.3%.)
FEE FAILURES
And staying in Australia, ASIC is suing banking giant CommBank alleging they overcharged 42,000 business customers in fees and failed to disclose some or take timely action to remedy the issues. The action involves CommBiz, CBA’s online banking platform for business customers.
SWAP RATES A TOUCH SOFTER
Wholesale swap rates have probably eased today on global shifts. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was up +3 bps at 3.18% on Wednesday. Today, the Australian 10 year bond yield is down -1 bp at 5.04% from this this time yesterday. The China 10 year bond rate is now at just over 1.59% and up +1 bp. The Japanese 10 year bond is down -1 bp at 2.76%. The NZ Government 10 year bond rate is now at 4.76% and down -2 bps from yesterday at this time. (The RBNZ 10 year rate is 'prior day' and was up +6 bps at 4.77% on Wednesday.) And the UST 10yr yield is now at just on 4.99% and down -2 bps from this time yesterday.
EQUITIES MIXED
The NZX50 has risen +0.6% so far today. But the ASX200 has opened down -0.4%. Tokyo is up +0.5%. The KOSPI is up +0.4% at its open. Hong Kong is down -1.2% in early Thursday trade while Shanghai is up +0.1%. Singapore is little-changed in early Thursday trade. Wall Street was firmer in Wednesday trade with the S&P50 ending up +1.3% and the Nasdaq rose +1.6%. But both of these closes happened before rumours started swirling about changes and consequences at Nvidia and its dominating boss.
OIL PRICE LITTLE-CHANGED
American oil prices have eased slightly, down -50 USc from yesterday at this time with the WTI benchmark now at just on US$86/bbl, while the international Brent price is little-changed at just on US$92/bbl.
CARBON PRICE HOLDS
There have been no trades reported today so far, so the price is unchanged at $50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD EASES BELOW US$4000
In early Asian trade, gold has retreated another -US$62 from this time yesterday, now at US$3984/oz. Silver is down -US$1 at just under US$51.50/oz.
NZD FALLS BACK
The Kiwi dollar is down -40 bps from yesterday at just on 55.7 USc. Against the Aussie we down -20 bps at just under 81.3 AUc. Against the euro we are unchanged at 50.2 euro cents. This all means the TWI-5 is now just over 59.7 and down -20 bps from this morning.
BITCOIN ON HOLD
The bitcoin price is now at US$73,622 and little-changed from this time yesterday. Volatility has been low at just over +/- 0.9%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
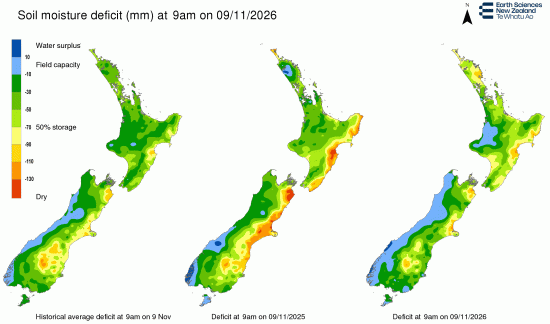
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.