
Here's our summary of key economic events overnight that affect New Zealand, with news the Europeans have thrown the kitchen sink at their economic problems.
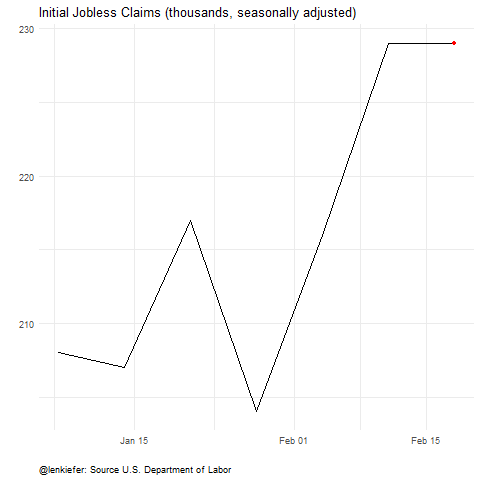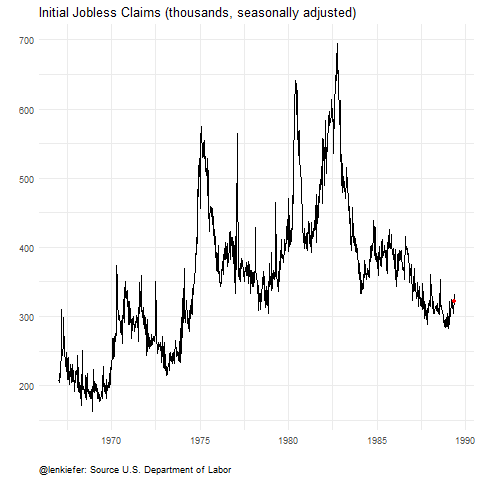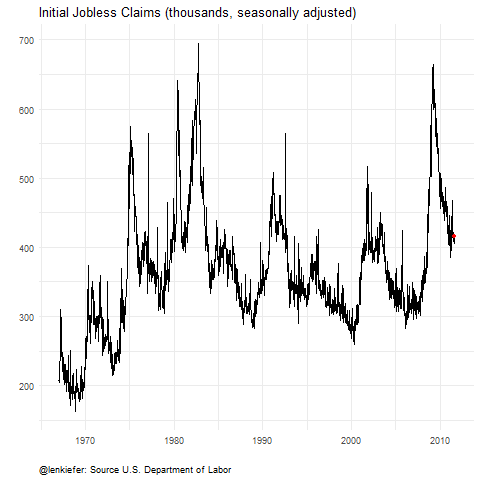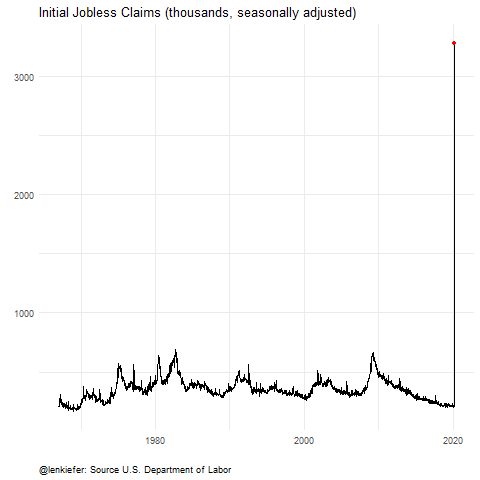
But first, the latest update for new unemployment claims in the US records almost +1.9 mln taking the level of "insured unemployed" to 20.5 mln. Millions more are uninsured. The new claims are slightly above what was expected for last week (+1.8 mln). The non-farm payrolls report out tomorrow will give a fuller picture of the giant American labour market.
US employers announced almost 400,000 layoffs in May, a sharp reduction from the almost 700,000 in April. So far in 2020 there have been company announcements of almost 1.5 mln layoffs. Of course, announced layoffs are just a fraction of actual layoffs, but the trend is clear. In all of 2019, announced layoffs totalled 590,000.
The American trade balance got sharply worse in April, taking it back to year-ago levels. Clearly tariffs don't work to fix this problem. Their deficit with China increased -US$9 bln to -US$26.0 bln in April. For the year to date, the US is running a -US$76 bln deficit their largest with any country. Overall, US exports fell -30% from the same month a year ago, and their imports fell -20% on the same basis. The 2020 trade situation is getting more out of balance for them although it had improved marginally in earlier months.
In China, loan deferrals for struggling SMEs are gathering pace. Up to 15 May 2020, Chinese banks provided deferrals on ¥1.3 tln yuan in principal repayments, involving 750,000 borrowers.
In Hong Kong, crowds are gathering to mark the Tiananmen Square massacre anniversary despite an official ban. Police have not intervened so far. If they don't, it is sure to infuriate Beijing.
Indonesian motor bike sales fell a massive -80% in May, year-on-year. Indonesia tops India as the world's largest motorbike market.
The ECB said it would scale up its bond-purchase program by almost double to nearly €1.4 tln, a move that puts its stimulus effort in line with the US Fed.
Germany has followed France to use a multi-billion-euro recovery plan to support an electric car switch, while SUVs face higher taxes.
In Australia, data out yesterday revealed that retail sales plunged a record -18% in April, while strong iron ore prices delivered a +AU$8.8 bln trade surplus on top of the +AU$10.4 bln surplus in March.
An alliance of Australasian experts has lodged a comprehensive blueprint for the resumption of ‘safe’ trans-Tasman travel with the New Zealand and Australian Prime Ministers, recommending multiple layers of protection to be embedded across the passenger journey
Japan is getting ready to relax quarantine regulations for business visitors soon, and the first list of countries that will be exempted are Thailand, Vietnam, Australia and New Zealand.
The latest compilation of Covid-19 data is here. The global tally is now 6,573,300 which is up +135,000 in a day, still rising at a faster pace than recently.
Now, just over 28% of all cases globally are in the US, which is up +22,000 since this time yesterday to 1,862,000. This is a similar rate of increase and the spread isn't abating. US deaths are now exceed 108,000. Global deaths now exceed 388,000.
In Australia, there have been 7240 cases (+11 since yesterday), 102 deaths (unchanged) and a recovery rate of just under 92% (unchanged). 23 people are in hospital there (-2) with 4 in ICU (-1). There are now 474 active cases in Australia (-13).
There were zero cases again yesterday in New Zealand, so now only one person is left with it in the whole country. We are now at thirteen days with zero new cases.
The iron ore price is ignoring official Chinese warnings about a frenzy and is higher yet again today, and on high volumes of trades. Thermal coal prices are being ignored by buyers, dropping to ten year lows. Mines are shutting.
The UST 10yr yield is up again, today up another +5 bps at 0.81%. Their 2-10 curve has steepened to +62 bps. Their 1-5 curve is also steeper at +23 bps, and their 3m-10yr curve is now at +69 bps. The Aussie Govt 10yr yield is up another +7 bps to 1.08%. The China Govt 10yr is up too, by another +2 bps to 2.85%. And the NZ Govt 10 yr yield is also firmer, up +2 bps to 0.93%.
The gold price has made back most of what it dropped yesterday, today rising +US$21 to US$1,721/oz.
Oil prices are higher today. The US crude price is up about +US$1 to just on US$37.50/bbl. The Brent price is up to nearly US$40/bbl.
The Kiwi dollar has risen further. We are now just on 64.5 USc and a new fifteen week high. On the cross rates we are to 93.1 AUc. Against the euro we have actually slipped back bit to 56.9 euro cents. That means our TWI-5 has moved up slightly to 69.2.
Bitcoin is higher than this time yesterday by +2.4% at US$9,810. The bitcoin rate is charted in the exchange rate set below.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.