
 By Roger J Kerr
Global event risk has caused our long term interest rates to plumb new lows over recent weeks as the heightened uncertainties in Europe have a seen a wave of safe-haven buying of US Treasury Bonds, which has driven US and NZ bond yields lower.
The return of US 10-year bond yields to 1.82% is at odds with the growing evidence of the US economy recovering under its own steam.
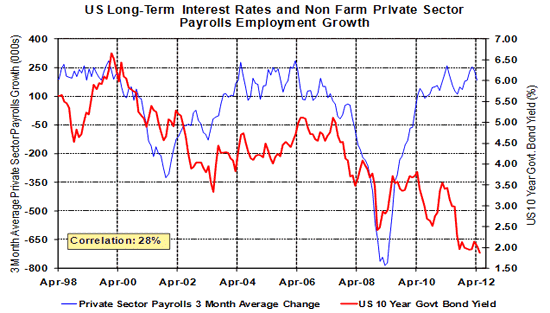
Historically, there has been a reasonable good correlation between US 10-year Treasury bond yields and US employment growth.
However, as the chart below depicts, over the past two years this linkage has completely broken down with the three-month average Non-farm Payrolls employment figures back in the +100,000 to +250,000 region, while bond yields have gone the other way.
In normal market circumstances stronger jobs growth in the US is associated with higher GDP growth, thus some inflationary pressures and higher market bond yields.
The massive divergence and gap that has opened up does not make a lot of sense if you just look at the US domestic economy in isolation (yields should be much higher).
What is happening is that global investor worries about Europe have driven investment funds into the security and safety of Uncle Sam’s IOU’s.
The small matter of investment bankers, J P Morgan losing US$2 billion in market proprietary trading does not help investor confidence much either.
If you subscribe to the view that Europe completely collapses and the US economy heads back into recession you would expect US bond yields to stay below 2% for a long time yet.
However, if you see the current market sentiment as relatively short-term and it will blow over within a few weeks, the more positive US economic picture does point to their long-term interest rates eventually increasing (and taking our three to 10 year swap rates up with them).
Decisions by NZ corporate borrowers to hedge their future debt/interest rate risk at the current record low swap interest rate levels, or not as the case may be, is totally based on the future direction of US bond yields and has very little to do with the RBNZ and the NZ economy.
If you think the US and global economy is doomed you will not fix interest rates at the current record low levels.
If you believe the US economy is back on track (as I do), it cannot be a difficult to decision to fix higher percentages for longer.
--------------------------------------------------------------------------------------------------------------------------------
To subscribe to our daily Currency Rate Sheet email, enter your email address here.
--------------------------------------------------------------------------------------------------------------------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.