
Here's my Top 10 links from around the Internet at 10:00 am today in association with NZ Mint.
Bernard is back tomorrow with his version.
As always, we welcome your additions in the comments below or via email to bernard.hickey@interest.co.nz.
See all previous Top 10s here.
1. In praise of the 'currency wars'
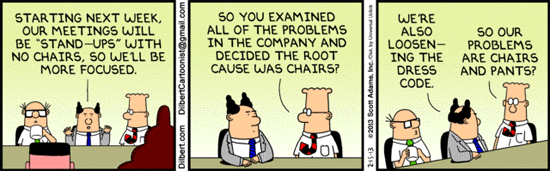
We are hearing a lot about 'currency wars', but is it all way overblown?
History can teach us about these things and some are suggesting we are jumping to wrong conclusions about QE.
Maybe it is not a zero-sum game which is what the critics argue. The Economist points out these may be "positive-sum currency wars".
Maybe we should like them.
Maybe NZ will be a net beneficiary? Your view?
The whole point of lowering real interest rates is to stimulate consumption and investment which ordinarily leads to higher, not lower, imports. If this is done in conjunction with looser fiscal policy (as is now the case in Japan), the boost to imports is even stronger.
Thus, QE’s impact on its trading partners may be positive or negative; it depends on a country’s trade intensity, the substitutability between its and its competitors’ products, and how sensitive domestic demand is to lower rates. The point is that this is not a zero sum game; QE raises a country’s GDP by more than any improvement in the trade balance.
2. The cost of political correctness
Our youth unemployment rate is a disgrace. It's at very European levels of 30.9%. Miraculously though, young people find jobs as soon as they get older. At 20-24, the unemployment rate falls to 12.4%, and then to 6.6% when they are 5 years older, then to 4.9% in another five years.
Australia's youth unemployment rate is half ours at 17.8%. The difference? Basically we make employers pay young people who need training the same rate as adults with work skills. Of course they will choose an adult. The Aussies recognise what needs to be done and make the appropriate adjustment. You can work out how many more young people would have jobs here if we had a youth unemployment rate the same as in Australia. The answer? 17,600 more young people in jobs. Our stance is seriously bad public policy.
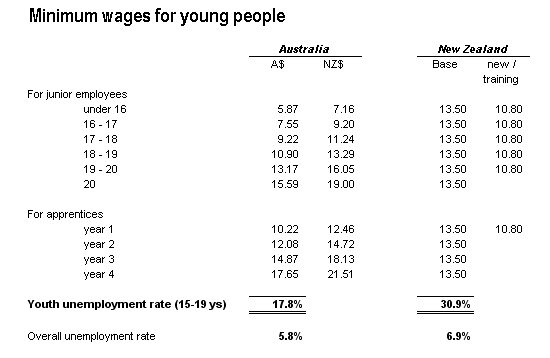
3. China's income gap problem
Minxin Pei is a sceptical expert observer of Chinese politics. He is impressed by what the Chinese Communist Party is saying about addressing growing inequality at home, but deeply doubtful that they can action what they say. Without real change, instability in China seems assured.
For instance, employees and executives in monopolistic state-owned enterprises have much higher real income than their counterparts in the private sector, mainly because they enjoy many hidden subsidies. Government officials are given, as legal perks, apartments for a fraction of their market value. They have lavish entertainment budgets and unrestricted use of official vehicles for personal purposes. They receive high-quality healthcare for free and enjoy generous retirement pensions.
But such privileges pale in comparison with how these officials and their families can turn their political power into opportunities to amass private wealth. These well-connected individuals can acquire state-controlled assets, such as land, mines, and companies, at prices substantially below market, and then flip them quickly for windfall profits -- all in pro forma compliance with official procedures.
This form of crony capitalism has produced a new Chinese kleptocracy. Addressing such inequality would benefit ordinary Chinese citizens, and the privileged and the powerful would have to foot the bill. Achieving such a feat is difficult but possible in democracies as less well-off voters far outnumber plutocrats. In autocratic regimes, however, ruling elites rarely initiative such efforts.
4. Today's raw market data ...
A quick new week update:
| as at 11:10am |
Today 9:00 am |
Friday |
Four weeks ago |
One year ago |
| NZ$1 = US$ | 0.8440 | 0.8516 | 0.8354 | 0.8316 |
| NZ$1 = AU$ | 0.8204 | 0.8221 | 0.7939 | 0.7783 |
| TWI | 76.81 | 77.27 | 75.09 | 73.47 |
| Gold, US$/oz | 1,612 | 1,646 | 1,690 | 1,723 |
| Dow | 13,979 | 13,942 | 13,493 | 12,807 |
| Copper, US$/tonne | 8, | 8,197 | 8,021 | 8,370 |
| Volatility Index | 12.46 | 12.66 | 12.43 | 17.78 |
5. The evidence
Hugh P bangs on relentlessly about how well Texas has done through the recession and how well its housing markets have performed. Now his colleague Wendell Cox has summarised the evidence. The whole article is worth a read. Anything NZ can learn here? I have to agree, as a nation we tend to reject other success stories and adopt solutions being tried in cities that 'fail' (ie the UK). Hardly seems smart.
Part of the explanation for the high living-environment score is doubtless Texas’s low cost of living. In 2011, the US. Bureau of Economic Analysis put Texas’s “regional price parity,” a measurement of the price level of goods in an area, at 97.1, a bit lower than the national level of 100 and far lower than the California level of 114.8. Adjusted for cost of living, Texas’s per-capita income is higher than California’s and nearly as high as New York’s. Factor in state and local taxes, and Texas pulls ahead of New York.
More than three-quarters of the cost-of-living difference between Texas and California can be explained by housing costs. As Figure Six shows, Texas mostly dodged the real-estate bubble of the 2000s: the affordability of houses in large metro areas spiked in America as a whole but rose only modestly in Texas. A major reason that Texas real estate is so affordable is that the state lacks the draconian land-use restrictions that drive California housing prices into the stratosphere.
6. A game changer?
A new report from PwC looks at the impact of expected growth in shale oil production on global oil prices and assesses how these changes could impact the wider economy and the oil and gas industry over the period to 2035. By any measure they are bullish.
Shale Oil – the Next Energy Revolution, examines scenarios that consider the potential impact of future growth in shale oil production on global oil prices and assesses how these changes could impact the wider economy and the oil and gas industry over the period to 2035.
- Shale oil production has the potential to reach up to 14 million barrels of oil per day by 2035
- This extra supply could push global oil prices down by around 25%-40% in 2035 relative to an EIA baseline projection of $133 per barrel in that year (in real terms)
- UK GDP could increase by around 2%-3.3% by 2035 (around £30-50 billion at today’s GDP values)
- Global GDP could rise by around 2.3%-3.7% by 2035 (around $1.7-2.7 trillion at today’s GDP values)
- Presents significant strategic opportunities and challenges for the oil & gas industry and governments
Lower global oil prices due to increased shale oil supply could have a major impact on the future evolution of the world economy by allowing more output to be produced at the same cost. These effects could build up gradually as shale oil production rolls out across the world to produce an estimated rise in global GDP of around 2.3%-3.7% in 2035. This would be roughly equivalent to adding an economy the size of the UK to total global GDP in that year.
7. Robots on the farm
Last week we brought you the story that virtual fences are on the way to manage livestock. This week we can report that the future may see robots doing weed control. Better than Roundup? More here »
"Right now it's sometimes recommended that if you've got a herbicide-resistant weed population, to go out and spray more or do another application, because that will kill it, maybe," Young says.
But, Young says, more herbicide can lead to even stronger resistance and additional chemical runoff into the environment. So he and other researchers are pursuing robots as an alternative to dealing with the superweeds of the future.
Imagine fleets of small robots, constantly roaming the rows, seeking and destroying alien plant forms. Today, farmers spray herbicide on everything to kill a few weeds. Young said robots could treat each weed individually.
"The computer would know what species it's dealing with, the appropriate weed-control tool, and you'd be done with it," Young said.
8. deja vu all over again
It is cliché now to say that we live in a 'risk society.' We simultaneously celebrate 'risk-takers' and blame those who undertake 'risky speculations' without much pausing over the contradiction. Our governments try to regulate risk out of society, at the same time try to encourage the development of new start-up businesses. We have an odd relationship with risk. But then again, we always have.
Freaks of Fortune, by Jonathan Levy, is a history of the United States looked at through Americans’ evolving conceptions of financial risk. It is reviewed by Steve Waldman:
There’s a running refrain on Battlestar Galactica: “All this has happened before, and all this will happen again.” One of the delights of Freaks of Fortune is to learn just how true that has been of finance:
• Following the crisis of 2008, it has become common to call for a separation between “speculative” and “safe” finance. The so-called Volcker Rule would prohibit banks from making certain kinds of risky investments. More radical proposals would bifurcate the financial system into safe “narrow banks” that invest only in government securities and investment funds that would function without any form of government insurance. All of these proposals echo the Depression-era Glass-Steagall Act, which imposed a separation between “safe,” federally insured “commercial banks” and risky “investment banks.” But Glass-Steagall itself is an echo of the status quo prior to 1873, when banks were divided into “savings banks,” intended to preserve the wealth of ordinary people and restricted to conservative investments, and “commercial banks,” the risky, freewheeling profit-seekers. In the 1870s, as in the 1990s and 2000s, the managers of “safe” banks lobbied and innovated and cheated around restrictions on the use of funds in their care.
• Private mortgage-backed securities, with their slicing-dicing reassignment of loans to unidentifiable groups of investors, are often described as novelties. In fact, Levy points out, “mortgage debentures” that bundled, tranched, and resold mortgage cash flows were a staple of the 1880s. They were justified on the same theories of diversification that would be dolled up with math and trotted out again a century later. Mortgage lenders of the Gilded Age bore no resemblance at all to the George Bailey–style local banker. New York financial firms held western mortgages acquired through brokers. To borrowers, a mortgage was a faceless master.
• Financiers have evaded accountability with appeals to the quantitative, statistical, “scientific” nature of their art long before supercomputers and stochastic calculus. In 1877 the president of the Equitable of New York refused to justify his firms’ valuation practices to a regulator: “There are certain fundamental rule[s]…which can only be understood by actuaries.” When such appeals proved insufficient to deter inquiries, a captured New York legislature explicitly stripped policyholders of the right to ask.
9. Job losses
Our story about job losses got a lot of reader support. Unions responded saying they would help (of course.)
We are keeping a tally of reported job losses and we are asking readers for help keeping track of them. It is just a crude list of announcements - no-one really thinks the Mainzeal employees will actually be out of work for long, if at all. But political parties have made a big deal about the issue and we want the evidence, and suspect it is out there.
But the only problem is that no-one has actually reported any losses since we launched it. I did expect it to gather regular evidence.
Does that mean the few that are being reported are being over-hyped? Or perhaps you have forgotten because the story announcing it is now off our busy home page? Adding this reminder here is our attempt to keep the issue current.
10. Today's quote
"I'm living so far beyond my income that we may almost be said to be living apart." - ee cummings
Dairy prices
Select chart tabs
11. woops, nearly forgot ...
Clarke & Dawe and the August scores.
12. Bonus for Bernard, the mad cyclist
I know the vid is an ad, but forgive me - it's from a town I lived in for more than 10 years so I have a soft spot for it, and besides it will make much more sense if you read this story first.
13. Westpac limits insurance
Westpac Australia as told staff that they are not to sell residential house insurance cover to homeowners in floodzones unless those homeowners have a mortgae with the bank. Cover for home owners is starting to get pretty selective just as premium costs are starting to rise fiercely. As most of the NZ domestic insurance industry is Australian owned, and few reinsurers will be applying a rating or risk difference between NZ and Australia, our premiums will probably follow Aussie risks as much and Kiwi ones.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.