
Here's my Top 10 links from around the Internet at 10:00 am today.
Bernard is back tomorrow with his version.
As always, we welcome your additions in the comments below or via email to bernard.hickey@interest.co.nz.
See all previous Top 10s here.
1. The only thing you need to know about China
China is going to have to spend NZ$8.6 tln over the next 20 years - just to absorb the expected flow of rural migrants into its cities.
Don't take my word for it - the authority on that figure is our own Helen Clark, as head of the UNDP who came up with the research (while she was in NZ, incidentally).
That's almost NZ$0.5 tln per year in spending - NZ$430,000,000,000.00 actually.
This is at the heart of why the Chinese are sure they can sustain 7%+ growth for the foreseeable future.
How they do this is going to affect us all for generations to come. The UN wants them to spend it in a way that satisfies western middle class sensitivities (all 'green', 'fair' and 'social'). Not sure how likely that is though.
“The battle against climate change, the fight against inequalities, and the response to a rapidly ageing population – to mention a few – will depend on measures taken within the context of China’s burgeoning cities,” argues the report, entitled Sustainable and Liveable Cities: Toward Ecological Civilisation.
“China is experiencing urbanisation at a speed and scale that is unprecedented in human history”, said Helen Clark, UNDP Administrator, at the report launch in Beijing. The report states that in 2011, there were more people living in China’s cities than in its countryside for the first time, when only six decades earlier a mere 10 per cent lived in an urban setting. “By comparison, this same demographic transition took 150 years to occur in Europe and 210 years in Latin America,” said Clark.
According to the report, the urban population is forecast to grow by an additional 310 million people to 70% of the total population by 2030. By this point, over one billion Chinese people will live in cities.
2. Hurricane season
Anatole Kaletsky has a sobering list. The 'good thing' when you read his piece is that not a lot of this will directly affect us. Indirectly, maybe, but it's only likely to affect us if it all goes to custard. NZ - the place to be.
This year, exactly on cue, the seasonal risks are again building up: war in the Middle East; a watershed decision in U.S. monetary policy, plus the announcement of a new Fed chairman; a German election that could make or break the euro; the long-awaited “third arrow” of Shinzo Abe’s Japanese reform program; another internecine conflict over the U.S. budget and Treasury debt limit that could result in a government shutdown or even a temporary default. And I am not even counting probable policy upheavals in China, India, Brazil, Indonesia, Turkey and other crisis-ridden emerging economies, whose timing is less certain but which could also fall within the next few months.
3. 'Abenomics for everyone'
Someone like me is old enough to remember Japan as an economic powerhouse. But for many now, it is an icon of zero-growth. But something else is happening: both China and India are now slowing. Why?
Yuriko Koike thinks she knows why. (A 1987 Kiwi clue: Roger Douglas was right. Keep reforming in spite of the feint-hearted or the cup-of-teaers will win and the drive will dissolve.)
How did Asia’s boom fade so quickly? Economics is supposedly a cold-blooded subject. Yet successful economies are prone to one of the most dangerous emotions of all: self-satisfaction, that excessive pride that Confucius condemned, which makes governments wary of reforming what has been a winning model, even when stresses begin to appear.
Japan has paid a high price for this attitude. Even after its property bubble burst 24 years ago, the authorities continued to believe that the country’s growth model needed no adjustment. The result was two lost decades of deflation and introspection before Japan finally embraced the reforms needed to kick-start a new, more open – and hence more vibrant – economic model.
China and India, it seems, have also succumbed to economic hubris. Three decades of success in China, and a decade in which India supposedly overcame the old, slow, “Hindu rate of growth,” are ending with both economies slowing precipitously. And both are slowing for the same reason: stalled reform, which is a direct result of governments being so satisfied with today’s conditions that they fail to address tomorrow’s rising dangers.
4. Today's raw market data ...
A quick new-week update:
| as at 11:10am |
Today 9:00 am |
Friday |
Four weeks ago |
One year ago |
| NZ$1 = US$ | 0.7720 | 0.7761 | 0.7778 | 0.8010 |
| NZ$1 = AU$ | 0.8691 | 0.8708 | 0.8731 | 0.7782 |
| TWI | 73.33 | 73.63 | 73.88 | 71.97 |
| Gold, US$/oz | 1,395 | 1,408 | 1,305 | 1,692 |
| Dow | 14,817 | 14,856 | 15,605 | 13,111 |
| Copper, US$/tonne | 7,095 | 7,211 | 6,950 | 7,650 |
| Volatility Index | 17.01 | 16.81 | 11.84 | 17.98 |
5. More pain coming?
The 'Great Repression' has punished savers. Now the rise in bond yields promises to do the same for fixed income investors.
The interest rate on ten-year US Treasury bonds has risen almost a full percentage point in the last six months, to 2.72%, implying a loss of nearly 10% in the price of the bond. And the recent rise in long-term rates is just the beginning of an increase that will punish investors who are seeking extra yield in long-term bonds, says Martin Feldstein. If it's up from here, what will be the consequences?
Although it is difficult to anticipate how high long-term interest rates will eventually rise, the large [US] budget deficit and the rising level of the [US] national debt suggest that the real rate will be higher than 2%. A higher rate of expected inflation would also cause the total nominal rate to be greater than 5%.
Today’s investors may not recall how much interest rates rose in recent decades. The interest rate on ten-year Treasuries increased from about 4% in the mid-1960’s to 8% in the mid-1970’s and 10% in the mid-1980’s. It was only at the end of the 1970’s that the Fed, under its new chairman, Paul Volcker, tightened monetary policy and caused inflation to fall. But, even after disinflation in the mid-1980’s, long-term interest rates remained relatively high. In 1985, the interest rate on ten-year Treasury bonds was 10%, even though inflation had declined to less than 4%.
The greatest risk to bond holders is that inflation will rise again, pushing up the interest rate on long-term bonds. History shows that rising inflation is eventually followed by higher nominal interest rates.
6. Hydrogen fuel from sunlight - another step
Photosynthesis is a natural miracle, one we understand but can't duplicate efficiently.
The earth receives more energy from the sun in a day than it uses in a year. Serious research is underway trying to produce hydrogen directly from the sun's rays, and it looks like some progress is being made. Energy storage is the goal. More from the Berkeley Lab involved:
While artificial photosynthesis can be used to generate electricity, fuels can be a more effective means of storing and transporting energy. The goal is an artificial photosynthesis system that’s at least 10 times more efficient than natural photosynthesis.
“In coupling the absorption of visible light with the production of hydrogen in one material, we can generate a fuel simply by illuminating our photocathode,” Moore says. “No external electrochemical forward biasing is required.”
7. 'The most pernicious cliché of our time'
A word has invaded the linguistic ecosystem that is so insipid, so insufferable that it must be stopped. The word is “disruptive”. Well that's what New Republic science editor Judith Shulevitz thinks.
She seems so threatened by change, she has written a deliciously acerbic reaction: she doesn't like disrupters, especially of the public institutions she admires. But she might have a point too ...
For one thing, they possess an almost utopian faith in technology: online or “blended” learning; massive open online courses, or MOOCs; cool health apps; and so on. Their convictions seem sincere, but they also coincide nicely with the interests of the Silicon Valley venture-capital crowd. If you use technology to disrupt the delivery of public services, you open up new markets; you also replace human labor with the virtual kind, a happy thought for an investor, since labor is the most expensive line item in all service-industry budgets.
Second, Christensen and his acolytes make the free-market-fundamentalist assumption that all public or nonprofit institutions are sclerotic and unable to cope with change. This leads to an urge to disrupt, preemptively, from above, rather than deal with disruption when it starts bubbling up below.
Third, they don’t like participatory democracy much. “The sobering conclusion,” write Christensen and co-authors in their book about K–12 education, “is that democracy ... is an effective tool of government only in” less contentious communities than those that surround schools. “Political and school leaders who seek fundamental school reform need to become much more comfortable amassing and wielding power because other tools of governance will yield begrudging cooperation at best.”
Many well-meaning philanthropic disrupters have taken that advice to heart, and the results reveal something George Orwell pointed out, which is that stale phrases mechanically repeated have dangerous political effects. It is too soon to see how disruption will play out in public-health and government agencies, but what it has done to public schools is now becoming clear.
8. RT is no ordinary news organisation
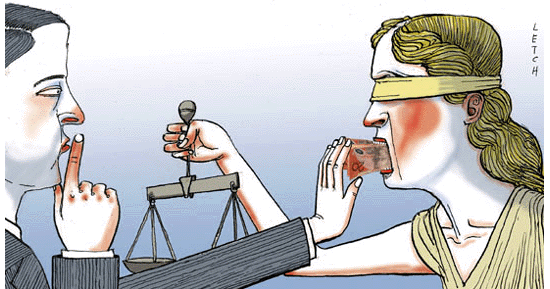
Available on our SkyTV and the internet, RT is a fast growing international broadcaster. But RT stands for "Russia Today" and yes, its a directly funded organ of official Moscow. Much more subtle than its Soviet counterpart, it differs from other public broadcasters in that it only pretends independence.
I wonder what the commercial underpinning is for SkyTV to run RT here. Cash from Moscow?
Most public broadcasters seem captured by the politics of their staff (BBC, NPR, ABC, VoA, etc.) but RT is captured by the politics of their paymasters. It's a dominance the Kremlin is pleased about, reports Spiegel Online:
Since 2005, the Russian government has increased the channel's annual budget more than tenfold, from US$30 million to over US$300 million. Russia Today's budget covers the salaries of 2,500 employees and contractors worldwide, 100 in Washington alone. And the channel has no budget cuts to fear now that Putin has issued a decree forbidding his finance minister from taking any such steps.
The Moscow leadership views the funds going to the channel as money "well invested," says Natalya Timakova, the press attaché to Prime Minister Dmitry Medvedev. "In addition, Russia Today is - and I hope the Germans will forgive me for this remark - significantly more modern than Deutsche Welle, for example, and it also has more money."
9. Common sense
A [former] economic adviser to Joe Biden makes some interesting points about minimum wages. He thinks something’s broken in an economy that serves up low wages to significant numbers of adults whose families depend on their earnings while profits are rising. And the benefits to low-wage workers far outweigh these costs when policy adjustments are made.
Workers spending more increases the velocity of money and businesses gain. Granted there are some tricky tradable/non-tradable issues for an open economy like New Zealand, but companies are proving that they can grow in spite of a high exchange rate, especially when they are committed to productivity and innovation.
I think we do need to be committed to ridding ourselves of low-paid-and-dead-end jobs. But too-low incomes anywhere cost everyone, not just the low-paid. It's like investing in preventive healthcare. It's obvious.
This is all just capitalism, and I’m all for it. But market failure is also a hallmark of capitalism, and those purporting to hold forth on the economy have a responsibility to recognize such failures, particularly when they violate norms of equity and opportunity.
If significant portions of some industries pay wages on which grown-ups cannot support a family, while other industries post historic profits, and, importantly, the gains to the latter fail to ever reach the former, then corrective policy is needed. Some of that should be done through wage subsidies and work support (for example, the earned-income tax credit, and health and housing support), and some should be through moderate increases in the minimum wage.
To me, that’s not radicalism. It’s plain common sense.
10. Today's quote
"More and more these days I find myself pondering how to reconcile my net income with my gross habits." - John Nelson
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.