
What can history teach us? Does it repeat? Does it rhyme?
Knowing what happened in the past can be instructional, even if it doesn't always repeat.
The pattern of interest rates in 2023 looks a lot like patterns prior to 2008.
Prior to 2008 we had a long period where term deposit rates were a minor premium to benchmark Government bond rates.
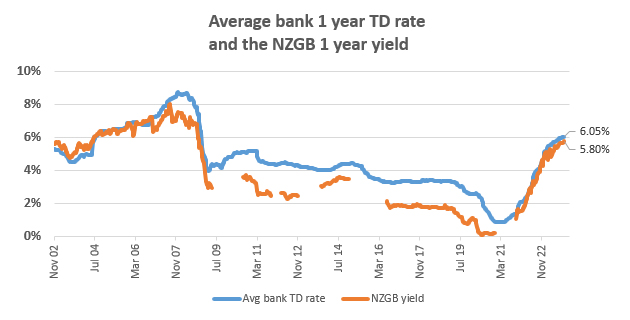
After the GFC, that premium rose sharply, mainly because the premium for safety rose. Benchmark rates were very low. The domestic (local currency) credit rating for NZ Government Bonds stayed at AAA (even if the foreign currency credit ratings fell from that). But the main trading bank credit ratings were two, then three notches below that.
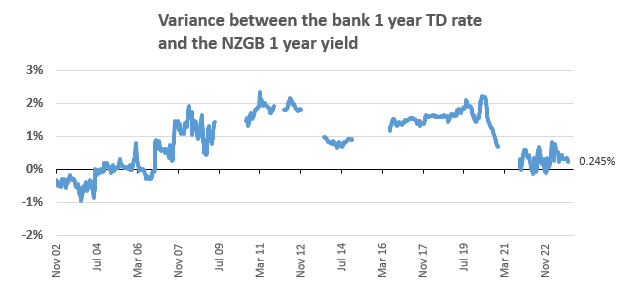
There have rarely been Government guarantees on bank deposits in New Zealand, so it makes sense that savers were rewarded with an interest rate premium for the risks involved. It has been more than 100 bps (1%) for more than a decade.
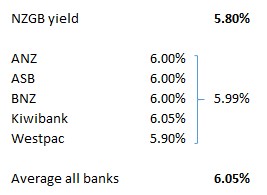
But now those premiums are disappearing again. And they are smaller for the main banks.
Why?
There may be a number of reasons, but it is a 'market' induced change. The actions of savers and lenders together, which generate fund flows in a competitive environment, are the actual source of these differences.
Market motivations can be influenced by regulatory actions.
Perhaps the impending arrival of a Government Guarantee for bank deposits is making depositors realise they will become essentially risk-free, so the premium between TDs and Government bond rates doesn't need to be much of a difference.
The Government announced its intention to bring in deposit insurance in mid 2020 and Cabinet approved the plan in 2021. It will be in place next year.
Regulatory de-risking of the banking system, through enhanced capital requirements, tighter liquidity and core funding standards, new conduct & culture expectations all also push the difference between 'risk-free' government debt and private sector bank debt closer together.
All these actions of the past 5-10 years make the current environment for savers quite different to the historic environment.
Savers probably should come to expect much smaller premiums from bank term deposit offers in future.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.