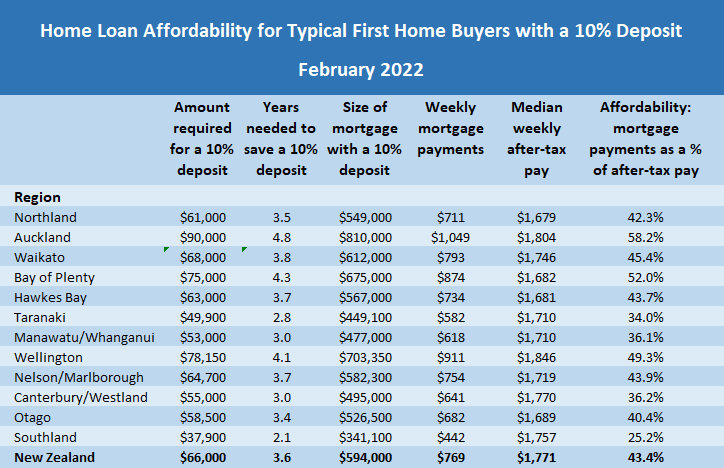
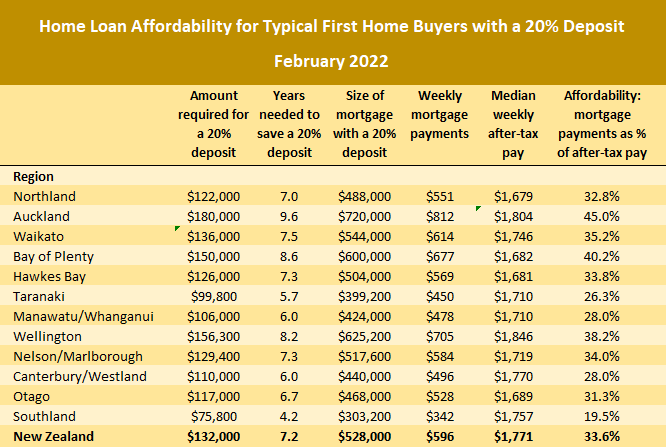
First home buyers have received some relief over summer, with significant price falls at the bottom of the market in Auckland and prices in the rest of New Zealand mostly flattening out at the start of the year, according to interest.co.nz’s Home Loan Affordability Report for February.
The most significant change has come in Auckland, where the Real Estate Institute of New Zealand’s lower quartile selling price peaked at $966,000 in November last year and has dropped back in every month since, slipping to $900,000 in February.
That’s a 6.8% price fall in the space of three months. Although $900,000 is still an eye watering amount of money to pay for a home at the bottom end of the market, the $66,000 reduction would have brought significant relief for anyone shopping for a home at the so-called affordable end of the market.
First home buyers would have been further helped by the fact that although mortgage interest rates are rising, they took a breather at the start of the year.
The average of the two year fixed mortgage rates offered by the major banks bottomed out at 2.52% in May last year and then rose steadily to peak at 4.21% in December.
The average dipped slightly to 4.19% in January and crept up to 4.20% in February.
In practical terms, the two year fixed mortgage rate has remained flat over summer, and although it has risen from its lows, it has only gone back to where it was in February 2019 and remains well below its long term average, although further rises are expected.
So how would this combination of a drop in house prices at the bottom of the market and a lull in mortgage rate rises have affected typical first home buyers over the summer months?
Firstly it brought down the amount they would have required for a deposit on a lower quartile-priced home, from $96,600 for a 10% deposit in November last year to $90,000 in February this year, saving them $6600.
You can double those numbers for a 20% deposit.
Secondly, it reduced the amount they would need to set aside for the mortgage payments on a lower quartile-priced home purchased with a 10% deposit, from $1115 a week in December to $1049 in February, a reduction of $66 a week.
However, even though those reductions would be useful, house prices in Auckland remain at such high levels that the prospect of home ownership is likely to be well out of reach for first home buyers on average incomes.
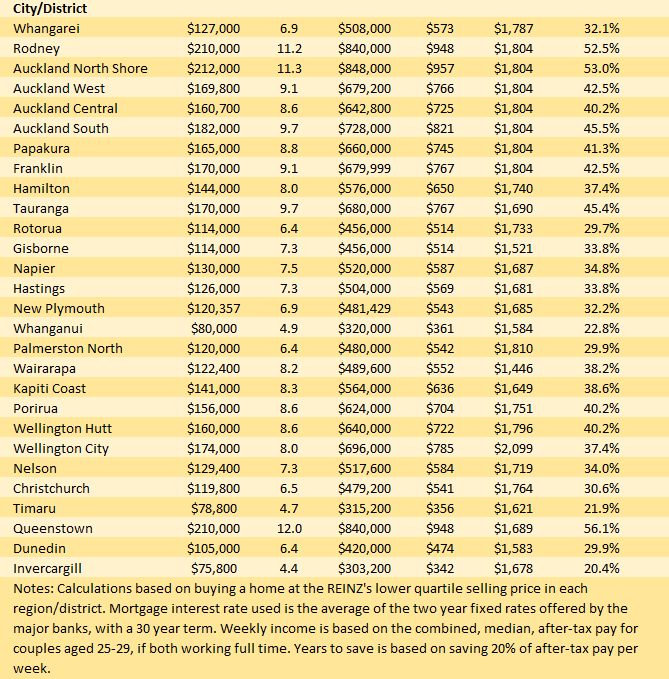
Interest.co.nz estimates that a couple who both work full time at the median rate of pay for 25-29 year olds in Auckland, would be taking home $1804 a week after tax between them.
That’s without allowing for any other deductions such as student loan payments.
That means that the amount of their weekly pay packet that would be eaten up by mortgage payments on a lower quartile-priced home would have declined from 62% in December last year to 58.2% in February this year.
The traditional rule of thumb measure is that mortgage payments are considered unaffordable when they take up more than 40% of after-tax pay.
By that measure, achieving home ownership in Auckland is not a realistic possibility for young couples on average wages without winning Lotto, finding a pot of gold at the end of a rainbow or receiving a visit from a generous fairy godmother.
However what the latest figures do show is that house prices can fall at a rate which more than negates the impact of rising interest rates. This could lead to a gradual improvement in affordability over time.
A different picture elsewhere in NZ
Outside of Auckland the situation is different.
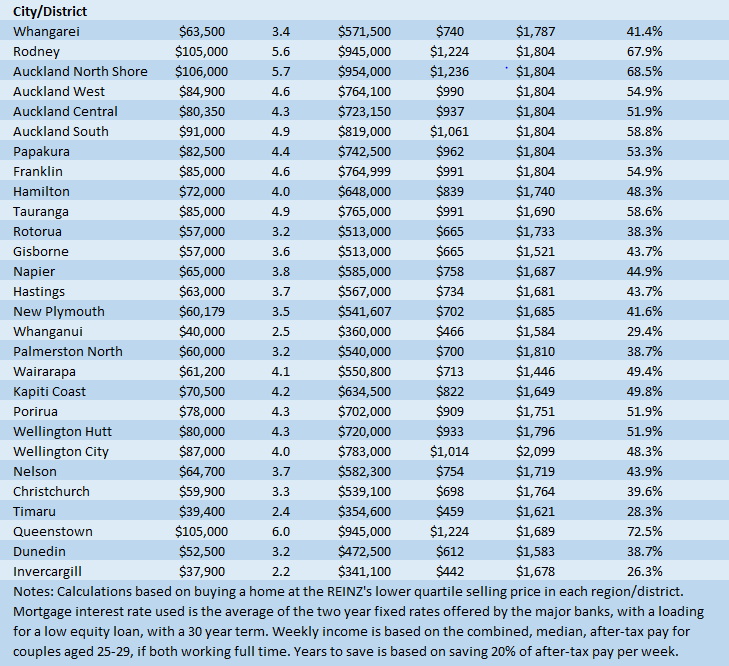
There haven't been the big price falls seen in Auckland over the last few months and prices are still going up in some regions, although at a much slower rate than previously. Four regions – Waikato, Manawatu/Whanganui, Canterbury and Otago hit record lower quartile prices in February.
The overall trend outside Auckland has been for lower quartile prices to flatten and that has been reflected in the national lower quartile price. This peaked at $670,000 in November last year, then declined over the next two months to $650,000 in January, before bouncing back up to $660,000 in February.
Those monthly movement were small, so the overall trend for prices at the bottom end of the market for properties in regions outside Auckland is for them to have settled near their recent peaks.
The big trends for prospective first home buyers to watch over the next few months will be whether price falls in Auckland continue, whether those price falls begin to spread outside of Auckland, and whether any price falls will be sufficient to offset ongoing rises in mortgage interest rates.
The comment stream on this story is now closed.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.