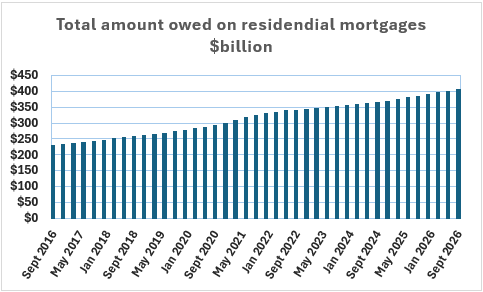
The amount of money owed to New Zealand banks for residential mortgages topped $400 billion for the first time in the September quarter (Q3).
According to Reserve Bank data, New Zealanders owed banks $401.7b on their residential mortgages at the end of Q3. That's up $20.5b, or 5.4%, from Q3 last year.
However, the total amount of residential mortgage interest bankers charged their customers headed in the opposite direction, declining to $4.84b in Q3 this year from $5.22b a year earlier. That's a drop of $370 million, or 7.1%.
That was in spite of the fact mortgage interest rates have been rising during that period, with the average of the two year fixed rate increasing from 4.72% in Q3 last year to 5.42% in Q3 this year.
The fact that total mortgage interest charged by the banks has declined while interest rates have risen, is likely due to a timing lag due to the amount of time it takes borrowers to come off longer term fixed-term rates.
Additionally, although the total amount of interest charged has declined on an annual basis, it has been rising compared to the previous quarter for the last two quarters (Q2 and Q3) of this year, suggesting the total of mortgage interest being charged by banks has turned around and is now starting rise along with interest rates.
The total amount of interest being charged is likely to continue rising well into next year if the Reserve Bank resumes increases to the Official Cash Rate (OCR), although following this week's surprise decision to hold the OCR at 2.75%, who knows what might happen.
New Zealanders with a mortgage were due to make $7.36b worth of mortgage payments to their banks in Q3, almost unchanged from $7.37b in Q3 last year.
In the 12 months to the end of September, total scheduled mortgage payments were $29.1b, slightly more than Statistics NZ's estimate of the $28.3b that people spent at supermarkets and grocery stores in the 12 months to March this year.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.