The Green Party wants to reform fiscal responsibility laws to encourage governments to focus on building economic capacity, rather than obsessively maintaining low debt levels.
A discussion document published on Tuesday said the fiscal tools of the 1980s had not equipped the country to meet 21st century challenges.
The Public Finance Act and fiscal advice provided by the Treasury was overly fixated on the risk of debt, while ignoring the costs of underinvestment and long-term considerations.
“For decision makers and policy advisers, this creates a bias toward lower debt levels and higher operating balances than may be economically optimal, while understating the risks and costs of underinvestment,” the document said.
Chlöe Swarbrick, the Green Party co-leader, put it more bluntly: The Coalition Government was currently “borrowing for tax cuts, while actively contracting the productive real world capacity of our economy.”
A lot of the blame for this perceived problem was directed at the Public Finance Act and the neoliberal governments of the 1980s and 1990s who wrote the bulk of it.
The Act, which is considered to be a world-leading fiscal framework, was first introduced by Labour after the 1984 currency crisis and was expanded by Richardson in 1994.
Swarbrick said the Act was more about ideology and risk aversion than economics. Fears of repeating the debt crisis and the personal politics of Ruth Richardson’s reforms were now baked into Treasury's fiscal management system.
The Green Fiscal Plan discussion document argued Treasury had calculated an overly cautious debt ceiling, and that its fiscal models failed to recognise benefits of spending.
Raise the roof
Treasury’s current advice suggests the government should keep net core Crown debt below 50% of gross domestic product, in order to retain a 40% buffer for responding to economic or natural shocks.
The model it uses to calculate this assumes interest rates could exceed nominal economic growth by 3 percentage points, and that the Government could run a surplus before interest costs of up to 3% of GDP after a crisis to stabilise debt.
The Green Party argues these assumptions are unnecessarily conservative. A 40% debt buffer would be enough to cover two Covid-19 shocks shocks at once, or more than 23 simultaneous Cyclone Gabrielles.
Additionally, the long-run average interest rate was only 0.8 percentage points higher than growth between 1991 and 2021. Treasury itself described the 3% used in the analysis as “a tail risk scenario”.
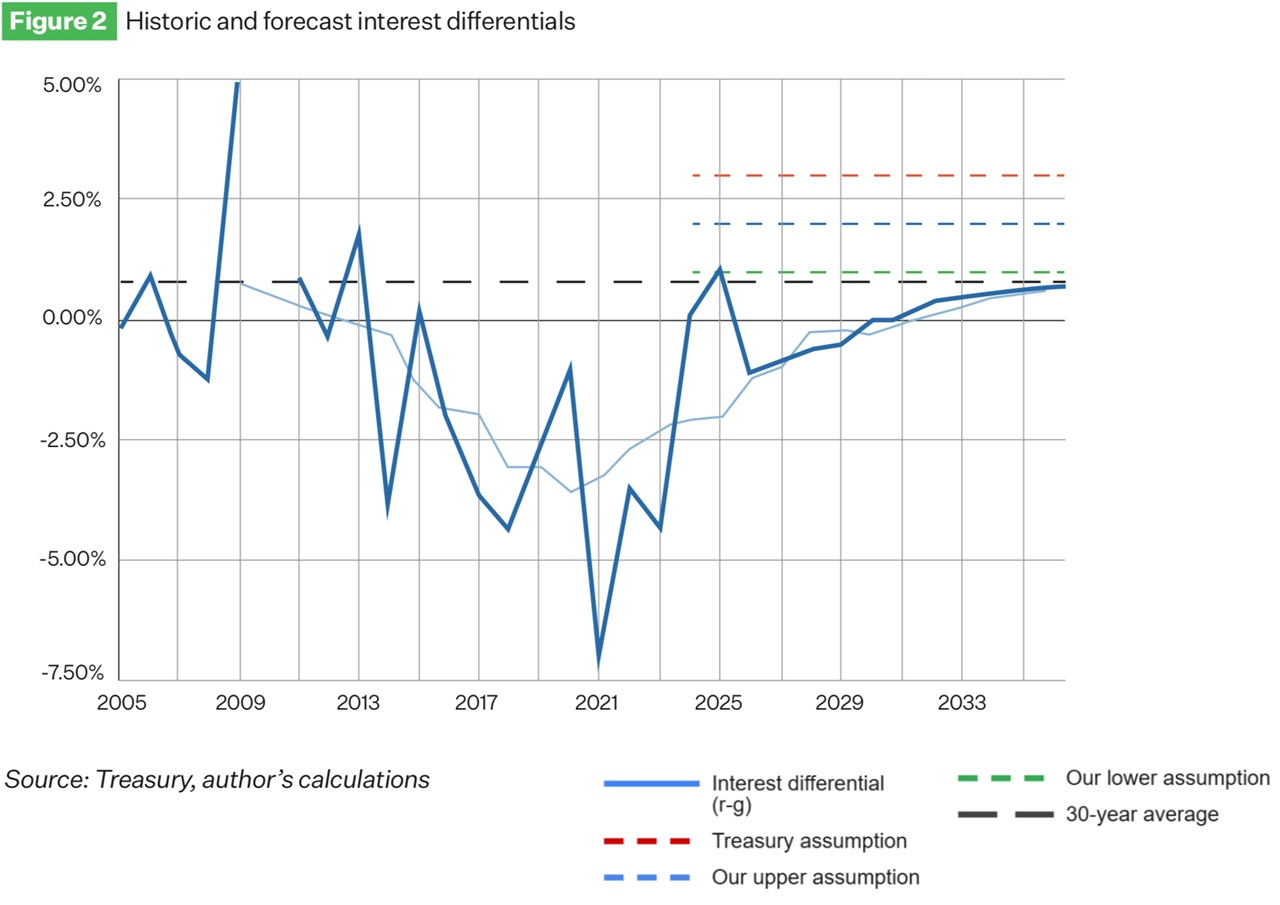
Essentially, Treasury’s model prepares for an unprecedented extreme shock. Such as a pandemic, a financial crisis, and a major earthquake all happening in quick succession.
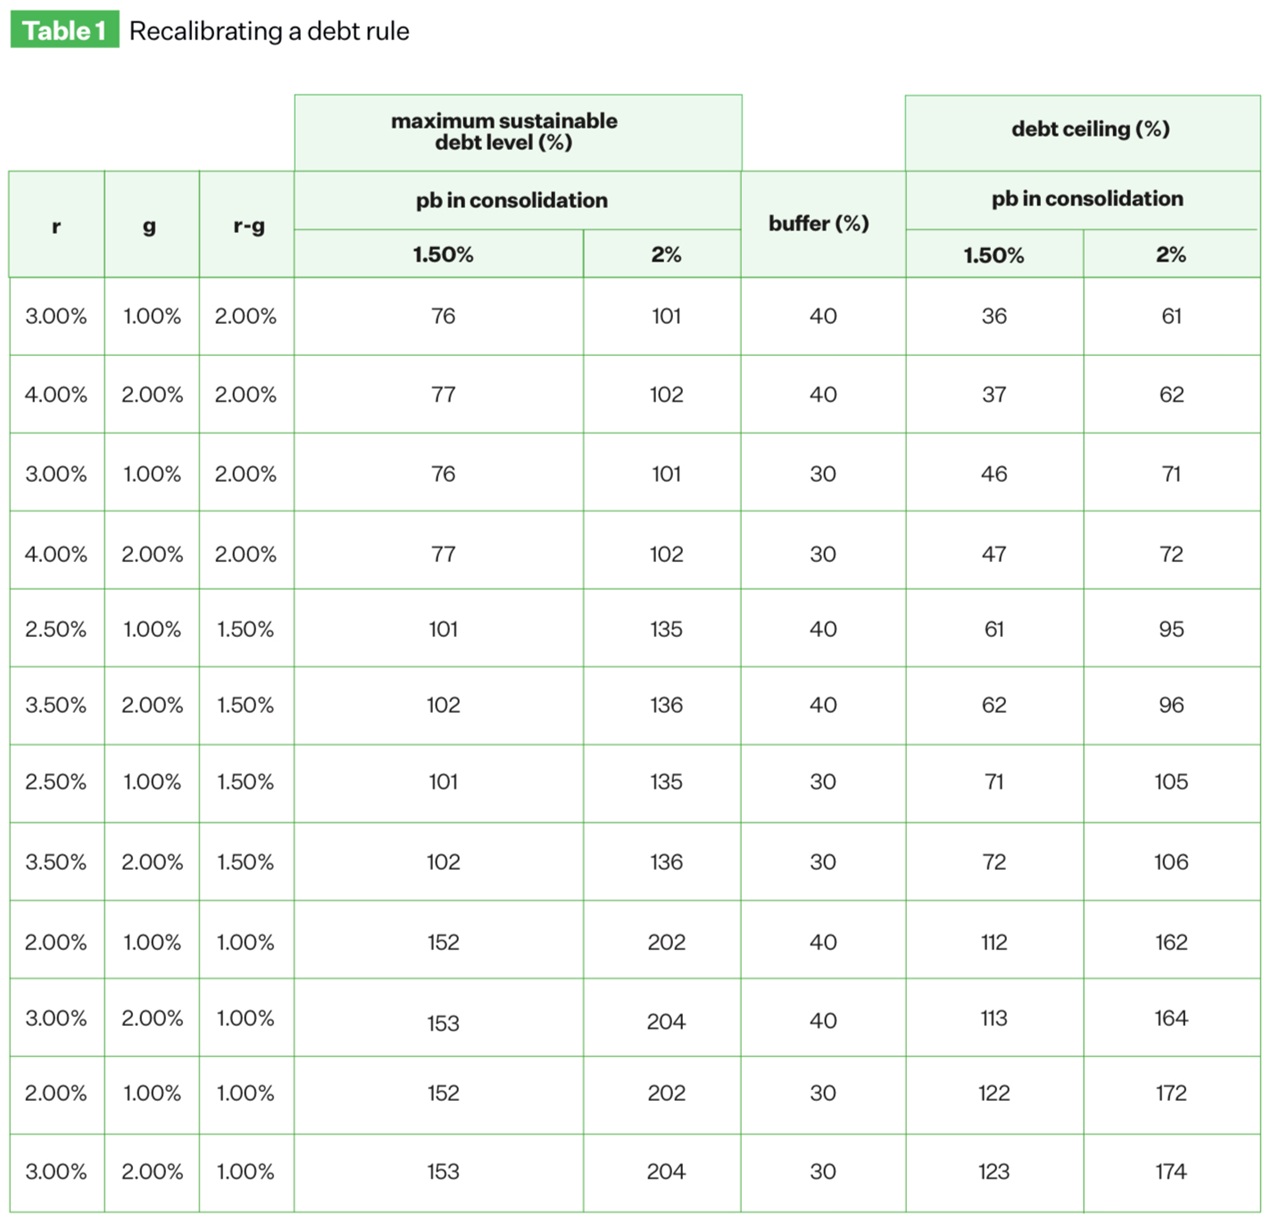
The Green Party says if the buffer were lowered to 30% and the interest–growth differential was set at 1% instead of 3%, the country could theoretically borrow up to 174% of GDP.
It also argues investments which make the economy or infrastructure more resilient to shocks could also help to reduce the buffer needed to respond to them.
The discussion document outlines a range of possible debt ceilings—from 36% to 175% of GDP—depending on the assumptions and risk tolerance applied. Based on long-run averages, the sustainable ceiling could be as high as 122% of GDP.
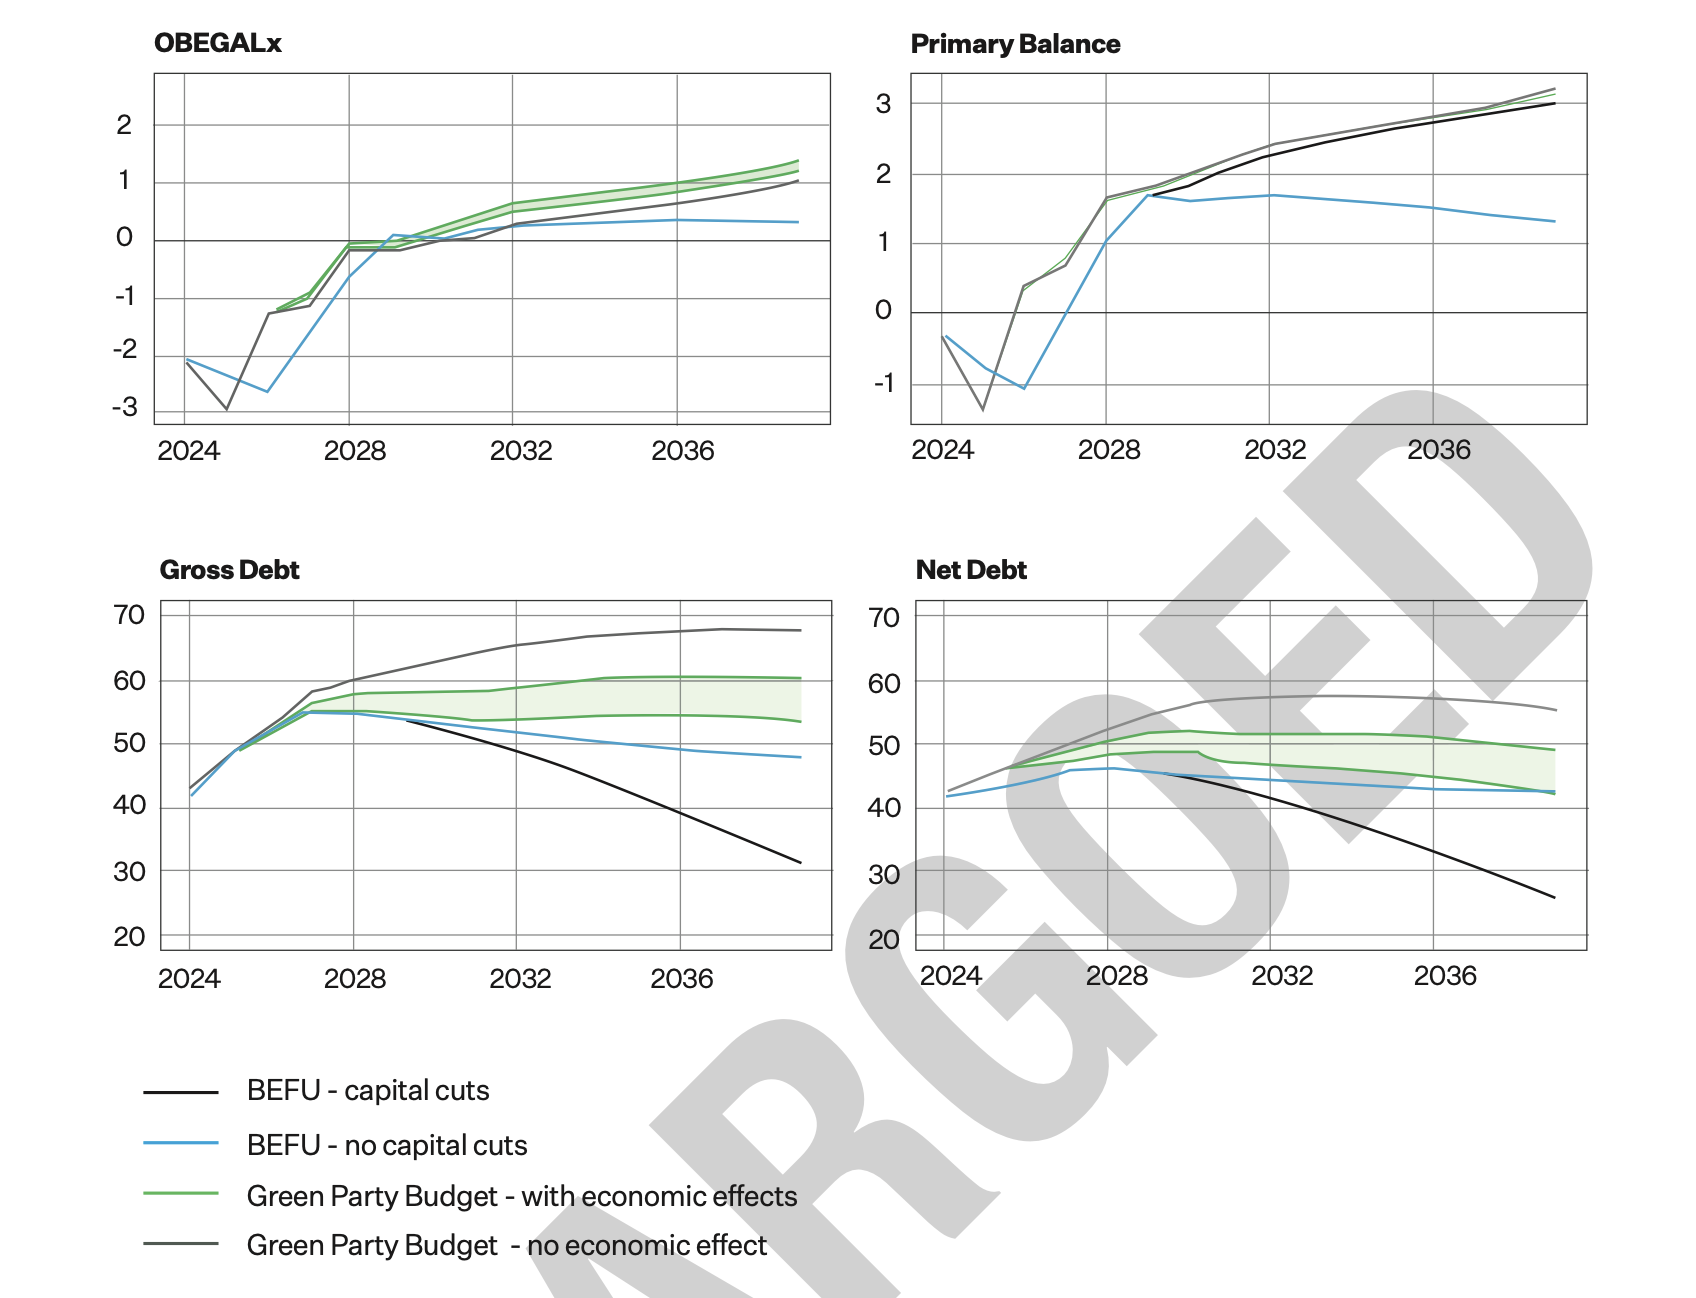
However, the Green Budget released last month only suggests lifting net core Crown debt to 53.8% and well below theoretical limits estimated in the fiscal discussion document.
Systematic pessimism
Beyond the debt ceiling, the Green Party also believes Treasury’s fiscal models don’t properly account for the economic benefits of spending and focuses primarily on the costs.
Models used by Treasury to inform government decisions rarely factor in long-term productivity gains and other “notoriously difficult to quantify” positive externalities — but the short-term fiscal costs are measured with absolute precision.
“These might be more accurately called accounting models, rather than economic models… Public spending is represented in these models as money thrown out the window, having no macroeconomic effect,” the document says.
Public finance laws should be reformed to encourage Treasury to do more analysis of the costs of underinvestment and the possible benefits of spending.
“If meeting fiscal targets results in the productive sectors of our economy shrinking, our planet burning and half a million New Zealanders using foodbanks each week, we need to rethink those targets,” Swarbrick and Marama Davidson said in a statement.
The party acknowledges the fiscal responsibility rules served a legitimate purpose after the 1980s when the government came “dangerously close to defaulting on its debts” but worries the emergency response has become a permanent policy.
The Public Finance Act has no provision for fiscally responsible debt levels, or requiring capacity enhancing investments. A requirement to consider future generations is interpreted mostly as a call to limit the debt burden, not build assets or capabilities.
“This is a one-sided intergenerational accounting that emphasises financial liabilities over the productive capacity, climate resilience, and infrastructure that will have a much more significant impact on future generations’ economic prospects.”
Defending neoliberalism
In an interview this weekend, Ruth Richardson told TVNZ that responsible fiscal management was mostly about not racking up debt or running persistent deficits.
“Controlling spending often comes down to one sheer capacity to absorb hatred, because the public believes if you spend more money, you get more goods, when the reverse is true,” she said.
She argued the country had been on track for another debt crisis, similar to the one in 1984, when she passed her infamous 1991 budget, which is often blamed for a lasting increase in poverty.
“The real poverty was New Zealand's if we had done nothing. If we had done nothing, then New Zealand would have most certainly faced the crisis that the Labour government did in the mid 80s,” Richardson said.
“And, in a crisis, the people who are hurt most are the poorest people, the people on the bottom of the rung.”
Swarbrick and the Green Party disagree. They see an opportunity to broaden the definition of “investment” to include health and education spending, which can lift people out of poverty and save money in the long run.
“These investments generate returns over decades through higher workforce participation, increased innovation capacity, and reduced social service needs,” the document says.
“Conventional fiscal frameworks struggle to capture these long-term benefits, leading to systematic underinvestment in human capabilities”.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.