
Although there are some legitimate comparisons between the high inflation of the past couple of years and that of the 1970s, there's a key difference in that labour costs were a key inflation driver then whereas profits have been this time, a Bank for International Settlements (BIS) working paper argues.
"In both cases, the original commodity shock quickly transmitted to good and service prices, generating broad based inflationary pressures. In both cases also, fiscal policy stepped in, to cushion the impact of the shock, possibly worsening the inflation problem. Last but not least, the experience of the seventies has been flagged as a reminder of the cost of un-rooting inflation, short of early and decisive policy action," the paper says.
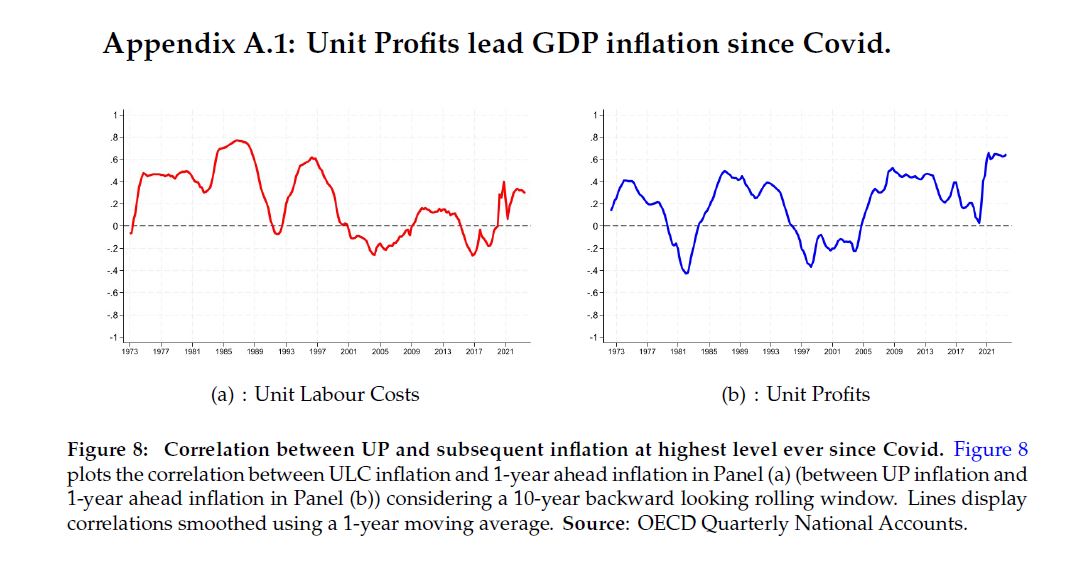
"We argue that this [1970s] comparison is ill-advised because the drivers of the recent inflation surge are fundamentally different from those in action back in the seventies. Back then, unit labour costs (ULC) were the main driver of GDP inflation. But more recently, unit profits (UP) have taken this role. The empirical evidence even points to UP having turned into a leading indicator of GDP inflation. We find evidence of this structural change for the United States, but the data also suggests a similar pattern in other countries like Canada or Germany. Moreover, this evidence is consistent with corporate profits (i) now accounting for a larger share of gross domestic income and (ii) having increased significantly post-Covid."
The paper, Monetary Policy with Profit-Driven Inflation, is authored by BIS senior economist Enisse Kharroubi, and Frank Smets who was the BIS Alexandre Lamfalussy Senior Research Fellow for 2023. Smets is former Director General of Economics at the European Central Bank and a professor of economics at the Department of Economics of Ghent University. The Basel, Switzerland based BIS is the central banks' bank.
Kharroubi and Smets say their paper investigates the issue of "profit-driven" inflation in the context of a New Keynesian model which they "enrich with reservation profits on the supply side."
"With this framework, we investigate the positive and normative implications of cost push shocks, taking the example of energy price shocks and focusing on monetary policy."
"Over the last decade, UP have essentially turned into a leading indicator of inflation, the correlation between current UP inflation and subsequent GDP inflation being positive and statistically significant up to six quarters ahead. Interestingly computing these lead/lad correlations over a shorter time window (in order to focus on the recent post-Covid inflation surge) provides similar if not stronger results, in terms of the leading properties of UP inflation relative to GDP inflation," say Kharroubi and Smets.
Figure eight, below, provides evidence of the correlation between current UP inflation and one-year ahead inflation rises, reaching the highest levels in the last 50 years of data, just after the outbreak of the Covid-19 pandemic, they say.
"Comparing the seventies to the recent period, the conclusion in a nutshell, is therefore that UP have replaced ULC as a leading indicator of inflation."
"We first show that energy price shocks lead to inefficiently large supply contractions and thereby inefficiently large (profit-driven) inflation, as firms which retrench do not internalise the social costs of doing so. Second, we show that optimal monetary policy follows a pecking order. It first aims at shielding the supply side from the fallout of the shock, thereby undoing the negative retrenchment externality. It then splits the burden of the shock between supply and demand, when insulating the supply side is too costly. Finally, when the energy price shock is very large, monetary policy looses traction. Budget-neutral fiscal interventions, e.g. redistribution from high-to-low-income households and/or from high to low-profit firms, can then restore monetary policy effectiveness," Kharroubi and Smets say.
Speaking in the Of Interest Podcast in December, Reserve Bank of New Zealand (RBNZ) Governor Adrian Orr said profit-led inflation had been happening in New Zealand as it had overseas. (Also see: UBS chief economist Paul Donovan unwraps profit-led inflation in our Of Interest podcast).
BIS says its working papers are on subjects of topical interest and are technical in character. The views expressed in them are those of their authors and not necessarily the views of BIS.
The RBNZ holds shares in BIS. As of June 30 last year, the RBNZ owned 3,211 BIS shares representing 0.6% of BIS shares on issue. The holding was valued at $293 million in the RBNZ's annual report.
*This article was first published in our email for paying subscribers early on Tuesday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.