
Here are the key things you need to know before you leave work today.
MORTGAGE RATE CHANGES
No changes here today, so far at least.
TERM DEPOSIT RATE CHANGES
Heartland Bank and the Police Credit Union have both trimmed rates today.
UP BUT STILL VERY NEGATIVE
"Reflecting New Zealand’s continued steady progress out of lockdown, the preliminary ANZ Business Outlook data for June saw further increases across all forward-looking activity indicators. Levels remain very low, however. Both business confidence and own activity saw large lifts, of 9 and 10 points respectively. A net 22% of firms expect to reduce investment (up 10); a net 51% expect lower profits (up 5), and a net 18% expect lower capacity utilisation (up 8). A net 37% of firms expect to cut jobs." More here. BNZ thinks this data shows a "stalled recovery".
IMPROVING, BUT STILL A LONG JOURNEY
In May the Light Traffic Index of ANZ's Truckometer series recovered more than half of its April fall, but it was still 37% lower than last May for the month as a whole. The Heavy Traffic bounced more, and is 7.8% lower than May 2019.
STUART MCKINNON CONFIRMED IN ANZ NZ ROLE
ANZ NZ has appointed Stuart McKinnon as managing director of institutional banking. McKinnon has been acting in the role since March following the departure of Paul Goodwin to an ANZ role in the US. McKinnon has worked for ANZ for 23 years, most recently as head of institutional relationships and specialised finance.
MASKED VARIATION
Wholesale trade sales rose +1.9% year-on-year in the March quarter, the same modest rise recorded in the December quarter. But that masked some very large changes in the components. For example, the grocery component was up +5.2% while the automotive component fell -6.1% on the same basis. Wholesale inventories are not rising; in fact they reduced in March compared with teh same level a year ago. This data is among the final elements being released befor the Q1-2020 GDP result is announced next week on Thursday. Massey's AI tool, GDPLive, suggests that that will show an annual change of a touch under +2.0%. Subsequently of course it has fallen hard and the GDPLive forecasts we are heading for a Q2-2020 result at the rate of -2.0% pa, or -15% quarter-on-quarter.
A KEY ACTIVITY METRIC
National electricity use seems to have recovered to normal levels.
NEARLY BACK TO NORMAL IN SOME KEY AREAS
Paymark is reporting that spending in the economy continued to rise during the last week of May. A core set of merchants that are indicative of underlying spending patterns saw electronic payments increase by +2.4% last week. However this still leaves spending amongst the group down by -1% compared with the same week last year. Not surprisingly, spending is still running well below year-ago levels among accommodation, cafes/bars and a wide range of non-retail merchants, such as travel agents, doctors, cinemas and education providers.
LOCAL UPDATE
There were zero new Covid-19 cases again today in New Zealand. Unless (until?) new cases pop up, we will be dropping this daily paragraph update.
AUSTRALIA UPDATE
In Australia, there have been 7267 cases (+2 since yesterday), 102 deaths (unchanged) and a recovery rate of just under 92% (unchanged). 19 people are in hospital there (-6 since yesterday) with 3 in ICU (-2). There are now 459 active cases in Australia.
GLOBAL UPDATE
The latest compilation of Covid-19 data is here. The global tally is now 7,113,400 and up +107,000 from this time yesterday. This is still rising at a faster pace than recently. American cases rose by +20,000 since yesterday to 1,960,6500. US deaths now exceed 111,000. Global deaths now exceed 404,000.
EQUITY MARKET UPDATES
The S&P500 rose +1.2% in trade earlier today, a sharp contrast to the falls of about -0.5% in European markets overnight. At the open in Shanghai, they have booked a modest +0.3% gain, Hong Kong is looking at a larger +1.0% rise, while Tokyo did its dash yesterday with a big +1.3% rise, but today is giving back about -0.6% of that so far. The ASX200 has opened +2.3% higher while the NZX50 Capital Index is in reverse today, down -1.7% in late trade.
SWAP RATES UPDATE
Swap rates may have changed little today. We don't have wholesale swap rates movement details yet but we will update this later in the day if they show a significant movement. The 90-day bank bill rate is still unchanged at 0.26%. The Aussie Govt 10yr has retreated sharply today by -11 bps to 1.06% but really only just giving up all of yesterday's equally sharp rise. The China Govt 10yr is down -2 bps to 2.85%. And the NZ Govt 10yr yield has slipped slightly to be just under the 1% benchmark at 0.99%. The UST 10yr is down -5 bps since this time yesterday at 0.85%
NZ DOLLAR FIRM
The Kiwi dollar has held on to its overnight gains to be still at 65.5. Against the Aussie we are staying firm at 93.6 AUc. Against the euro we are also holding firm at 58.1 euro cents. That means the TWI-5 is still up at 70.1 with no sign of a retreat from its recent gains.
BITCOIN HOLDS
The price of Bitcoin is little-changed from this time yesterday at US$9,689 which is only marginally softer. The bitcoin price is charted in the currency set below.
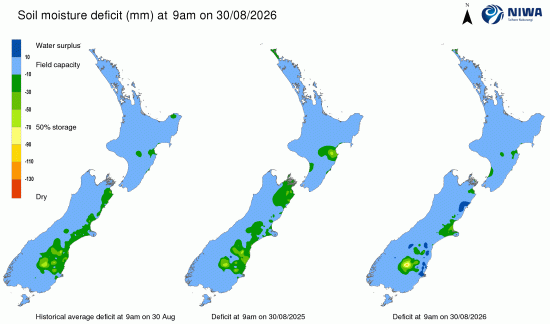
This soil moisture chart is animated here.
The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.