
This article was first published in our email for paid subscribers this morning. See here for more details and to subscribe.
By Gareth Vaughan
With customers increasingly encouraged to haggle with banks over mortgage interest rates in a competitive and low growth market, Westpac CEO Peter Clare is encouraging both Westpac customers and other banks' customers to open a dialogue with his bank.
Speaking to interest.co.nz yesterday after Westpac announced a initiative in partnership with MYOB offering businesses a free website for a year, Clare said Westpac's local bank managers had "degrees of discretion" to apply.
"So if a customer comes in and they're a very long standing customer, and they're changing a property, the local bank manager is empowered to make decisions within guidelines around the rate that gets offered to that customer," said Clare. "So we would encourage all of our customers to have a dialogue with us about the depth of their relationship, the products they're buying and what they aim to buy in the future."
"But more importantly from my perspective, we'd encourage other bank customers to come and talk to Westpac and see what Westpac can offer in terms of a total package of relationship against who they may be currently banking with," Clare added.
The Westpac Group has been targeting increasing the number of its customers taking four or more products from the bank. In last month's half-year results briefing group CEO Gail Kelly highlighted that 49% of Westpac NZ customers had four or more products versus just 29.9% at Westpac in Australia. Meanwhile, the latest Reserve Bank data shows industry wide housing loans up 1.4% to NZ$174.590 billion in the year to April. That 1.4% growth compares with double digit growth between 2003 and 2008.
Along with all the other banks Westpac has cut advertised fixed-term mortgage rates in recent weeks as swap, or wholesale, rates the banks themselves borrow at fall with weakening expectations for both global and domestic economic growth. See all bank advertised mortgage rates here.
Last month interest.co.nz highlighted that, in an environment of weak credit growth, banks were open to doing deals with customers behind the scenes to prevent them defecting to rivals. See Bernard Hickey's article here. A wave of stories with the same message have followed across the local media, including a New Zealand Herald story last week that said mortgage rates had "hit rock bottom" as banks offer thousands of dollars in cash and slash advertised interest rates in response to pressure from home-buyers for deals.
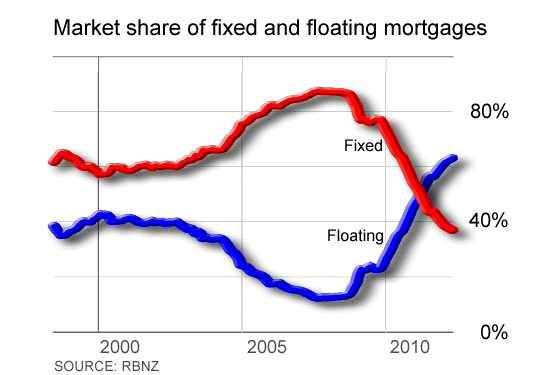
Financial markets are now betting the Reserve Bank will cut its Official Cash Rate by around 40 basis points over the next year to around 2%. However, none of the banks have yet cut their advertised floating, or variable, mortgage rates which are now up to 59 basis points higher than the lowest advertised one-year rate. The overall percentage of total mortgages by value on floating interest rates has this year reached its highest point since the Reserve Bank began keeping records on fixed versus floating in June 1998. The latest data shows 63%, or NZ$108.8 billion, of the total NZ$172.6 billion mortgages were floating at the end of April, although recent fixed rate cuts have probably started a trend back towards fixed rates.
Asked whether Westpac might cut its floating rate, Clare said pricing was reviewed on a continuous basis.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.