
 By Roger J Kerr
Hopefully, RBNZ Governor Alan Bollard was taking good notes when Fed Reserve Chairman Ben Bernanke was delivering his address to the annual central banker’s jamboree in Jackson Hole, Wyoming last weekend.
If he was listening carefully he would have received the message that Bernanke does not foresee a double-dip recession in the US economy, he projects modest economic growth for the second half of 2010 and stronger growth in 2011.
As Governor Bollard puts together his 16 September Monetary Policy Statement, he could be well advised to follow Bernanke’s view, than to listen to the local bank economists who have taken fright at weaker domestic data over the last few weeks and now want to the RBNZ to a sudden U-turn with monetary policy settings.
The local gurus are looking backwards at one part of the NZ economy (retail and property) and wrongly concluding that the recovery is stalling and GDP growth will be revised sharply downwards for 2011.
The RBNZ’s mandate and remit absolutely requires them to base monetary policy settings today on their projection of GDP growth and inflation in 12 to 18 months time.
If forecast GDP growth is north of +3.00% and inflation is north of 2.00% for 2011 they must have monetary settings at “neutral” now.
An OCR interest rate left at 3.00% is a long way from “neutral”, it is in emergency stimulatory territory still.
The new neutral is a 4.50% to 5.00% OCR.
The whole saga around the setting of the OCR is total poppycock in any case, as any OCR change is not making one iota of difference to true market deposit and lending interest rates in the economy.
The banks’ combined average cost of funds have been up at 4.50% to 5.00% for months now. The OCR is irrelevant in this situation, it is just that bank economist and bank traders need something to move to justify their own positions!
If Alan Bollard has any understanding of what really drives the NZ economy (exports), he will conclude, as I have, that the growth outlook is positive and he should not waiver from his well sign-posted removal of the 2009 monetary stimulus.
The RBNZ kow-towing to bank economist and moneymarkets pressure at this point will be counter-productive for growth and inflation.
Remember the RBNZ bowing to that pressure in 2007/2008 when they kept monetary policy too tight for too long and caused the recession? They would not want to make that same monetary policy mistake again by taking a populist, but too short-term view of the economy going forward.
If the NZ economy is stalling right now, how come nearly all the listed companies’ reported profits last week were above forecast and expectations. The economy does not just revolve around residential property and retail stores, our big export industries are doing very well now and will be expanding output over the next 12 months as they cash-in on record high export commodity prices.
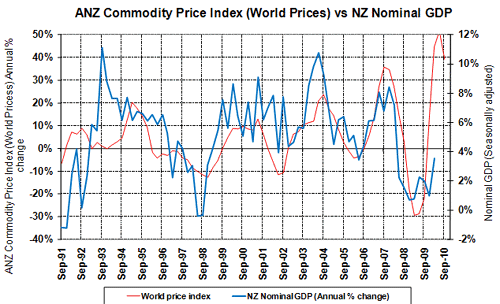
Alan Bollard needs to take another hard look at the chart below before finalising his monetary policy statement this week. The blue nominal GDP line is not stalling; it is following the export prices straight up.
--------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.