

By Roger J Kerr
It would pay not to read too much into the Kiwi jump up to 0.7800 between Christmas and New Year.
In thin, illiquid holiday markets there was a squeeze on in NZD/AUD cross-rate trading as short Kiwi, long AUD position holders closed down their profitable positions before 31 December month-end and aggressively bought the Kiwi. The gains were short-lived and the Kiwi has since returned to the 0.7500/0.7600 area.
The outlook for the NZD/USD rate over coming weeks and months is for further weakness to 0.7200 and perhaps lower.
The main market driver for the lower Kiwi being the EUR/USD rate which is now below $1.2900 and headed for $1.2500.
The Kiwi has some catching up to do on the EUR/USD rate and on top of that the EUR is still heading downwards. Stronger US economic data has come through in recent months as expected and the situation in Europe continues to deteriorate.
However, for the NZD/USD to trade lower it will not just require a lower EUR (which looks assured), but also a lower AUD against the USD.
The AUD reached $1.0150 between Christmas and New Year, however has yet again recoiled from rates above $1.0000 to currently trade at 0.9940. Commodity prices and Aussie economic data will determine future AUD/USD movements and my gut feeling is that both these determinants will be weaker than what the markets expect over coming weeks.
While the mining/resources states of WA and Queensland were booming, floods in Queensland and perhaps marginally lower Chinese demand may take the edge off upcoming Australian economic data.
Certainly the mortgage belts in Sydney and Melbourne are far from buoyant. Muted retail and housing data is what I expect out of Australia in the first part of 2011, thus interest rate increased being pegged back and the AUD losing ground against a stronger USD.
The Japanese Yen exchange rate to the USD is also highly correlated to the AUD/USD rate and at some stage soon the Yen must jump to 90.00 from the current 83.00.
The Chinese tightened monetary policy further with an interest rate increase on Christmas Day - timing that really gives two fingers to the financial/investment markets and the West.
Volatile and illiquid markets provided some perverse outcomes over the Xmas/New Year period. The negative NZ GDP result should have sent the Kiwi dollar lower, it spiked up to 0.7800 instead. The Chinese monetary tightening should have been negative for hard commodity prices, they spiralled upwards but have since retreated on the stronger USD exchange rate.
Asian sovereign wealth funds have been active buyers of NZD denominated Government Bonds over recent months.
The NZDMO is now issuing $300 million per week and tapping into Asian investors who are less likely to simultaneously hedge the NZD/USD exchange rate risk on their NZD investments. Thus they are net buyers of Kiwi in the FX markets. Many of these funds are diversifying their bond portfolios ways from holding European bonds for very good reasons. NZ is a beneficiary of this investment asset rebalancing out of Europe; however their NZD buying makes it harder for the Kiwi exchange rate to fall and help our export-led economic recovery.
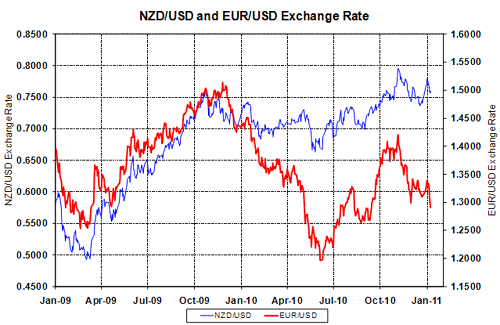
The chart below plots the NZD/USD rate against the EUR/USD and demonstrates the widening of the correlation gap over recent months. Very difficult to see the EUR moving up, therefore the NZD has to move down to 0.7000 at least to restore the correlation equilibrium.
--------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.