

Bankers are very good with money; they certainly know how to make it.
However, they want to be seen as 'responsible'. So they counsel others to 'be good with money'.
Recently, their lobby group put out a press release saying the New Year is a good time to assess your financial situation and to work to a plan. This is sound advice.
Their advice used statements like:
- set short and long term goals
- plan a budget
- grow your savings, and
- manage debt.
But the 'manage debt' exhortation sounded odd coming from them. Specifically, they say "make it your goal to be debt-free" and " be debt-free fast" and "avoid ‘dumb debt’" and "only ever borrow what you need" and "pay it off as quickly as you can".
All excellent advice, but you can't help wondering whether they want this advice to fall on deaf ears.
After all, they made $7 bln in profit last year by encouraging clients to take out more (and more) debt, most of which was not paid off and certainly not paid off quickly. Clients who are debt-free are of no use to any banker.
In reality, they don't want you to avoid 'dumb debt', they want you to take out more of it. Think credit cards and the growth of interest-incurring balances. Bankers set a honey-trap of "0% balance transfer interest" in the sole hope of charging you 20%+ when the balance transfer enticement ends in 6 or 12 months.
The overall fact is that housing debt grew more than +6% last year while other consumer debt grew +5%. These growth rates involved consumers adding +$13.1 bln to their obligations to banks.
New Zealand households now owe them $221 bln. (Businesses, farms, and our governments and their agencies are in hock to them for another $150 bln or so.)
However, to see whether this consumer debt is excessive, we need to look at it in terms of the size of our economy.
Nominally, GDP grew +2.7% in the same period.
So in 2015 bank clients have been adding debt at more than twice the rate our economy has been growing.
Yes, it does call for the type of restraint the NZ Bankers Association is calling for. But I doubt they really mean it.
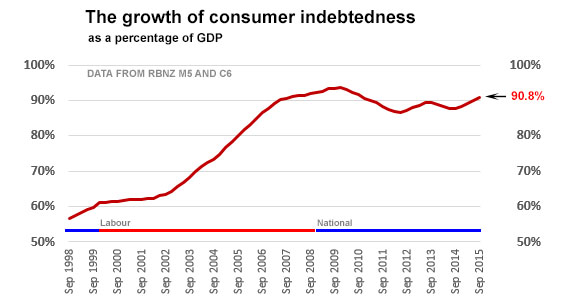
Relating the growth of consumer debt to the growth of our economy over a long period is how we should really look at this problem.
And that shows some surprising trends. Surprising to me anyway.
Firstly, for the past seven years we actually haven't been moving the dial much.
The GFC restrained us; we deleveraged just a little bit.
But maybe over the past year we are starting to feel good again and worry less about debt, which is why debt growth picked up in 2015. Perhaps we long to party like 2003-2007 again.
That earlier period was when the addiction started.
And as you can see, once you put on debt-weight, it is very hard indeed to take it off. The dieting we did from 2008 onwards has done little to roll back the impact of the earlier splurge.
We are now carrying around a lot of ingrained debt weight.
Perhaps readers can remind me what it was in 2002 that generated such an appetite for the addictive 'sugar' of debt.
If we need a sugar tax, perhaps we also need a debt tax. We certainly need some spur to change our behaviour.
Oh, and for the record, bankers do pay tax on their profits. Collectively they paid $2 bln or 28% which is the corporate rate in New Zealand. At least they have stopped their dodgy avoidance schemes. (Now we need to focus on insurance companies who use profit-shifting techniques to run much of their real profits through low-tax jurisdictions. But that is another story.)
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.