
While most of the recent interest rate increases have been for home loans, there have been minor changes to term deposit rate offers to savers in the background.
While none of these individually have been particularly newsworthy, the shifting landscape is worth reviewing.
As inflation rises, but returns on savings lag those rises, it probably becomes more important to seek out the best rates you can get.
And with the Depositor Compensation Scheme (DCS) in place, the risks for balances at any covered institution of $100,000 or less is low. You do have the risk of delay if a DCS institution goes under, but your capital to the covered level will be returned. And of course, you can spread your investments around many covered institutions to broaden protection and spread the risk.
The table below sets out the current rates on offer. But here are some different ways to look at the range of offers.
The tightest ranges are from the main banks.
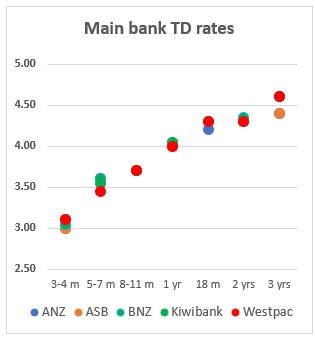
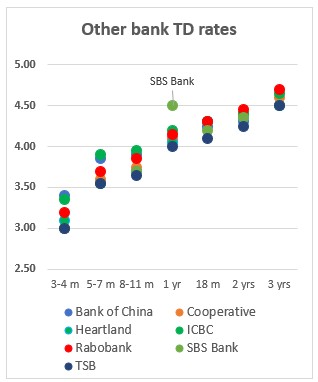
The challenger banks offer a steeper rate curve, and there are some outsized offers on the table that are worth savers' attention.
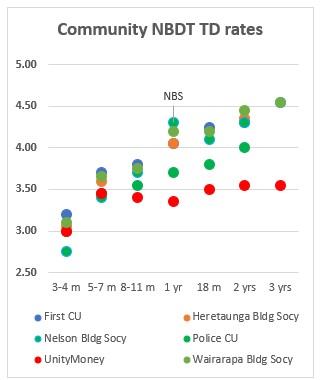
Among the community savings institutions, there are also some worthwhile anomalies to consider.
And among the finance company set, higher rates are available than all the other DCS covered institutions.
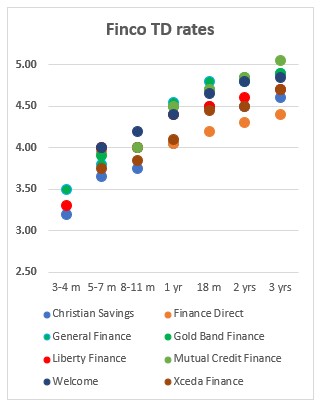
The attractiveness of any rate needs to be assessed considering inflation, especially your view of inflation over the term of your deposit, and your tax rate. Use the term deposit calculator here, or the one below the table, to calculate your expected net after-tax returns.
We should also point out that after-tax returns can be enhanced for some savers with higher tax rates by the choice of PIE structures. Not all institutions offer these, but most of the main banks do.
Always ask a bank for a better rate. Bank staff may have discretion to offer more than the advertised rate. And check your bank's app offers as they too are often enhanced to retain you.
The latest headline term deposit rate offers are in this table after the recent changes over the past four weeks. The yellow colour code is for those under 4%, and these have been reducing from the long end. The blue-coded rates are those under 3%. We might start to see a few 5% rates appearing soon if the rates pressure is sustained, and they are in pink.
This table only lists institutions covered by the Depositor Compensation Scheme.
| for a $25,000 deposit October 9, 2026 | Rating | 3/4 mths | 5/6/7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs |
| Main banks | ||||||||
| ANZ | AA- | 3.00 | 3.55 | 3.65 | 4.00 | 4.20 | 4.30 | 4.40 |
 | AA- | 3.00 | 3.60 | 3.70 | 4.00 | 4.30 | 4.30 | 4.40 |
 | AA- | 3.00 | 3.60 | 3.65 | 4.05 | 4.30 | 4.35 | 4.60 |
 | A | 3.10 | 3.55 | 3.70 | 4.05 | 4.30 | 4.60 | |
 | AA- | 3.10 | 3.45 | 3.70 | 4.00 | 4.20 | 4.30 | 4.60 |
| Kiwi Bonds. 'risk-free' | AA+ | 3.00 | 3.25 | 3.50 | ||||
| Rating | 3/4 mths | 5 / 6 / 7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs | |
| Other banks | ||||||||
| Bank of Baroda | BBB- | 3.20 | 3.60 | 3.60 | 3.90 | 4.00 | 4.20 | 4.50 |
| Bank of China | A | 3.40 | 3.85 | 3.90 | 4.10 | 4.25 | 4.30 | 4.50 |
| Bank of India | BBB- | 3.05 | 3.45 | 3.45 | 3.70 | 3.90 | 4.25 | 4.25 |
| China Constr. Bank | A | 3.10 | 3.50 | 3.60 | 3.85 | 4.00 | 4.15 | 4.35 |
| Co-operative Bank | BBB+ | 3.00 | 3.60 | 3.75 | 4.10 | 4.30 | 4.40 | 4.60 |
| Heartland Bank | BBB | 3.10 | 3.55 | 3.70 | 4.05 | 4.30 | 4.35 | 4.50 |
| ICBC | A | 3.35 | 3.90 | 3.95 | 4.20 | 4.30 | 4.40 | 4.65 |
 | A | 3.20 | 3.70 | 3.85 | 4.15 | 4.30 | 4.45 | 4.70 |
 | BBB | 3.00 | 3.55 | 3.70 | 4.50 | 4.20 | 4.35 | 4.50 |
 | BBB+ | 3.00 | 3.55 | 3.65 | 4.00 | 4.10 | 4.25 | 4.50 |
| Non-Bank Deposit Takers | Rating | 3/4 mths | 5 / 6 / 7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs |
| Community institutions with DCS protection | ||||||||
| First Credit Union | BB | 3.20 | 3.70 | 3.80 | 4.05 | 4.25 | 4.30 | |
| Heretaunga Bldg Society | 3.05 | 3.60 | 4.05 | 4.35 | ||||
| Nelson Building Society | BB+ | 2.75 | 3.40 | 3.70 | 4.30 | 4.10 | 4.30 | 4.55 |
| Police Credit Union | BB+ | 3.00 | 3.45 | 3.55 | 3.70 | 3.80 | 4.00 | |
| UnityMoney | BB | 3.00 | 3.45 | 3.40 | 3.35 | 3.50 | 3.55 | 3.55 |
| Wairarapa Bldg Society | BB+ | 3.10 | 3.65 | 3.75 | 4.20 | 4.20 | 4.45 | 4.55 |
| Finance companies with DCS protection | ||||||||
| Christian Savings | BB+ | 3.20 | 3.65 | 3.75 | 4.05 | 4.50 | 4.50 | 4.60 |
| Finance Direct | 3.95 | 4.05 | 4.20 | 4.30 | 4.40 | |||
| General Finance | BB | 3.50 | 3.80 | 4.00 | 4.55 | 4.80 | 4.80 | 4.90 |
| Gold Band Finance | BB- | 3.90 | 4.00 | 4.50 | 4.70 | 4.85 | 4.90 | |
| Liberty Financial | BBB | 3.30 | 4.00 | 4.00 | 4.40 | 4.50 | 4.60 | 4.70 |
| Mutual Credit Finance | B+ | 4.00 | 4.50 | 4.70 | 4.85 | 5.05 | ||
| Welcome | 4.00 | 4.20 | 4.40 | 4.65 | 4.80 | 4.85 | ||
| Xceda Finance | B+ | 3.75 | 3.85 | 4.10 | 4.45 | 4.50 | 4.70 | |
Term deposit rates
Select chart tabs
Daily swap rates
Select chart tabs
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.