
In its last October 30 update, MBIE reported that a barrel of Dubai crude was at US$117 or NZ$208. Today these prices are US$98 or NZ$177. This is a notable recent pullback.
But at the start of the year, this price was US$60/bbl or NZ$105/bbl. That means the raw inputs to our fuel costs have now risen +63% in USD and +69% in NZD. Nationally we are paying +6% 'extra' for imports that are priced in or based on USD than a year ago. A currency penalty over an above the raw cost change.
This is a driver in our tradeable inflation which ran at 4.3% in the year to September, well above the overall 3.7% CPI rate. Most observers see CPI being driven up further in Q4, largely due to that fuel shift.
So 'experienced inflation' (ie the cost of living) isn't going away. For savers, the feeling is real that inflation is a key harm, as it is for most sections of society. We all need inflation back in its target range. And that is the RBNZ's core job.
Of course the RBNZ can't influence the cost of oil, and no-one expects it to. But it can weigh against the spread out of that rising cost. And one way is to set interest rates in a band that don't require the exchange rate to fall. After all our TWI-5 is now at a 17 year low. Imports are costing relatively more now.
And with a 2.25% OCR rate, local rates are underpinned by this unusually low benchmark. Afterall the Australian benchmark is 4.85%, the American benchmark is 4.00% (effective 3.88%), the ECB rate is 2.65%, the UK is 4.0% and Canada 2.5%. A country as vulnerable as ours probably can't afford to have a policy rate lower than all of those majors, and if it does we pay higher costs as our currency gets devalued.
If the RBNZ won't act or continues to act slowly, savers will need to look at their options to do their own weighing against inflation. One of the few options is to seek out higher deposit interest rates.
Fortunately, the taxpayer has made that easier by adopting the Depositor Compensation Scheme (DCS) to underpin deposits at covered institutions from loss should one of them fail.
And there are a number of options to get 4%-plus gross returns in the market now.
All the main banks have a 1 year rate of 4.00% or 4.05%.
Among the challenger banks, ICBC is offering 4.20% and Rabobank 4.15% for a 1 year TD.
Among the community-owned nonbank deposit takers (NBDTs), you can now get 4.50% at NBS (Nelson Building Society) and 4.20% at WBS (Wairarapa Building Society).
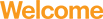
And among covered finance companies (NBDTs) you can get 4.40% at Welcome, and at Liberty Financial, 4.50% at Gold Band Finance, 4.55% at General Finance, 4.65% at Finance Direct, and 4.70% at Mutual Credit Finance, all for a 1 year term and all DCS covered to $100,000. In addition it is worth noting that Liberty Financial has an investment grade credit rating, a unique attribute among NBTDs and matching Heartland Bank and SBS Bank. All other NBDTs have credit ratings that are "sub-investment grade".
The attractiveness of any rate needs to be assessed considering inflation, especially your view of inflation over the term of your deposit, and your tax rate. Use the term deposit calculator here, or the one below the table, to calculate your expected net after-tax returns. We are in a harm minimisation period at present because there are zero DCS opportunities to access term deposits that have a tax-paid return above inflation.
We should also point out that after-tax returns can be enhanced for some savers with high tax rates by the choice of PIE structures. Not all institutions offer these, but most of the main banks do. The benefits depend on your tax rate.
And always ask a bank for a better rate. Bank staff may have discretion to offer more than the advertised rate. And check your bank's app offers as they too are often enhanced to retain you.
The latest headline term deposit rate offers are in this table after the recent changes over the past few weeks. The yellow colour code is for those under 4%, and these have been reducing from the long end. The blue-coded rates are those under 3%. We are starting to see a few more 5% rates appearing, maybe more soon if the rates pressure is sustained, and they are in pink.
This table only lists institutions covered by the Depositor Compensation Scheme.
| for a $25,000 deposit November 8, 2026 | Rating | 3/4 mths | 5/6/7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs |
| Main banks | ||||||||
| ANZ | AA- | 3.00 | 3.60 | 3.65 | 4.00 | 4.20 | 4.30 | 4.40 |
 | AA- | 3.00 | 3.60 | 3.70 | 4.00 | 4.30 | 4.30 | 4.40 |
 | AA- | 3.05 | 3.60 | 3.70 | 4.05 | 4.30 | 4.35 | 4.60 |
 | A | 3.10 | 3.60 | 3.70 | 4.05 | 4.30 | 4.60 | |
 | AA- | 3.10 | 3.45 | 3.70 | 4.00 | 4.30 | 4.30 | 4.60 |
| Kiwi Bonds. 'risk-free' | AA+ | 3.00 | 3.25 | 3.50 | ||||
| Rating | 3/4 mths | 5 / 6 / 7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs | |
| Other banks | ||||||||
| Bank of Baroda | BBB- | 3.20 | 3.60 | 3.60 | 3.90 | 4.00 | 4.20 | 4.50 |
| Bank of China | A | 3.40 | 3.85 | 3.90 | 4.10 | 4.25 | 4.30 | 4.50 |
| Bank of India | BBB- | 3.05 | 3.45 | 3.45 | 3.70 | 3.90 | 4.25 | 4.25 |
| China Constr. Bank | A | 3.10 | 3.50 | 3.60 | 3.85 | 4.00 | 4.15 | 4.35 |
| Co-operative Bank | BBB+ | 3.00 | 3.60 | 3.75 | 4.10 | 4.30 | 4.40 | 4.60 |
| Heartland Bank | BBB | 3.10 | 3.55 | 3.70 | 4.05 | 4.30 | 4.35 | 4.50 |
| ICBC | A | 3.35 | 3.90 | 3.95 | 4.20 | 4.30 | 4.40 | 4.65 |
 | A | 3.20 | 3.70 | 3.85 | 4.15 | 4.30 | 4.45 | 4.70 |
 | BBB | 3.10 | 3.60 | 3.70 | 4.05 | 4.30 | 4.35 | 4.60 |
 | BBB+ | 3.00 | 3.55 | 3.65 | 4.00 | 4.10 | 4.25 | 4.50 |
| Non-Bank Deposit Takers | Rating | 3/4 mths | 5 / 6 / 7 mths | 8 - 11 mths | 1 yr | 18mth | 2 yrs | 3 yrs |
| Community institutions with DCS protection | ||||||||
| First Credit Union | BB | 3.20 | 3.70 | 3.80 | 4.15 | 4.25 | 4.30 | |
| Heretaunga Bldg Society | 3.05 | 3.65 | 4.10 | 4.35 | ||||
| Nelson Building Society | BB+ | 2.75 | 3.60 | 3.70 | 4.50 | 4.10 | 4.30 | 4.55 |
| Police Credit Union | BB+ | 3.00 | 3.45 | 3.55 | 3.70 | 3.80 | 4.00 | |
| UnityMoney | BB | 3.00 | 3.55 | 3.70 | 3.35 | 3.50 | 3.55 | 3.55 |
| Wairarapa Bldg Society | BB+ | 3.10 | 3.65 | 3.75 | 4.20 | 4.20 | 4.45 | 4.55 |
| Finance companies with DCS protection | ||||||||
| Christian Savings | BB+ | 3.40 | 3.65 | 3.75 | 4.20 | 4.40 | 4.50 | 4.60 |
| Finance Direct | 3.95 | 4.65 | 4.85 | 4.90 | 4.95 | |||
| General Finance | BB | 3.50 | 3.80 | 4.00 | 4.55 | 4.80 | 4.80 | 4.90 |
| Gold Band Finance | BB- | 3.90 | 4.00 | 4.50 | 4.70 | 4.85 | 4.90 | |
| Liberty Financial | BBB | 3.30 | 4.00 | 4.00 | 4.40 | 4.50 | 4.60 | 4.70 |
| Mutual Credit Finance | B+ | 4.25 | 4.70 | 4.90 | 5.00 | 5.05 | ||
 | 4.00 | 4.20 | 4.40 | 4.65 | 4.80 | 4.85 | ||
| Xceda Finance | B+ | 3.75 | 3.85 | 4.10 | 4.45 | 4.50 | 4.70 | |
Term deposit rates
Select chart tabs
Daily swap rates
Select chart tabs
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.