
House prices at the bottom of the market are down by more than $100,000 from last year’s peak in Auckland but have barely moved in Canterbury. This means first home buyers have been hit harder by rising interest rates in some regions and are less affected in others, according to interest.co.nz’s latest Home Loan Affordability Report.
It shows that the Real Estate Institute of New Zealand’s national lower quartile selling price peaked at $670,000 in November last year and has since declined to $630,000 in June this year.
The lower quartile is the price point at which 25% of properties sold each month are below and 75% are above, representing the most affordable segment of the housing market.
Normally a $40,000 decline in the lower quartile price would be good news for first home buyers because it would mean they need less money for a deposit and a smaller mortgage, which would reduce their mortgage payments, all other things being equal.
Unfortunately while house prices have been falling, mortgage interest rates have been rising, and between November last year and June this year the average of the two year fixed rates charged by the major banks increased from 4.08% to 5.43%.
So how would first home buyers have fared in that mix?
Firstly, the amount they would need for a 20% deposit on a lower quartile-priced home would have declined from $134,000 to $126,000, saving them $8000 (halve those figures for a 10% deposit).
Secondly, the amount they would need to borrow if they had a 20% deposit would reduce from $536,000 to $504,000, reducing the size of their mortgage by $32,000.
If they only had a 10% deposit, the size of their mortgage would have declined from $603,000 to $567,000, down by $36,000.
So far so good – the figures above suggest first home buyers are benefitting from the current market slump.
It’s when you factor in the effect of rising interest rates that things start to get tricky.
If a first home buyer had a deposit of 20% and purchased a home at November’s lower quartile price of $670,000, the mortgage payments on that would have been around $596 a week.
If they had waited until June when the lower quartile price had dropped to $630,000, the mortgage payments would be around $655 a week, up $59 a week even though the amount they would have been borrowing would have declined by $32,000.
If they only had a 10% deposit under the same scenario, the mortgage payments would have risen from about $770 a week to $838, up by $68 a week (allowing for the loadings banks apply to low equity loans).
So it’s swings and roundabouts for first home buyers at the moment.
However the figures in the examples above are based on national house prices, and while changes in mortgage interest rates are the same throughout the country, there have been big regional differences in what has happened to house prices at the bottom of the market.
There have been major price declines in eight regions – Northland, Auckland, Bay of Plenty, Hawke’s Bay, Taranaki, Wellington, Nelson/Marlborough and Otago, where lower quartile prices are down significantly from the peaks of late last year/early this year.
In the other four regions – Waikato, Manawatu/Whanganui, Canterbury and Southland, prices have only dropped slightly from their peaks.
For those regions, there has been more of a flattening of prices at the bottom of the market rather than a significant decline.
The one characteristic of price trends in all regions of the country is that prices are no longer rising.
The difference in price trends so far has had a significant impact on how much mortgage rate increases would have affected first home buyers in different regions.
In the country’s most populous region – Auckland, the lower quartile price peaked at $966,000 in November last year. By June this year it had declined to $860,000, a drop of $106,000 over seven months.
In the Wellington region the lower quartile price peaked at $785,000 in December last year. By June this year it had declined to $710,000, a drop of $75,000 in six months.
But in Canterbury, where prices have merely flattened, the lower quartile price peaked at $550,000 in February/March this year. By June it had only dropped back to $544,000.
What does that that mean for first home buyers?
The amount needed for a 20% deposit on a lower quartile-priced home in Auckland dropped from $193,200 when prices peaked in November last year to $172,000 in June this year, a saving of $21,200.
A 10% deposit declined from $96,600 to $86,000 over the same period, down $10,600.
That meant the amount needed to be borrowed to finance the purchase with a 20% deposit declined from $772,800 in November last year to $688,000 in June, a reduction of $84,800.
The amount that would need to be borrowed with a 10% deposit declined from $869,400 in November last year to $774,000 in June this year, down by $95,400.
But with mortgage interest rates rising from 4.08% to 5.43% over that time, how would that have affected mortgage payments?
Based on the figures above, they would have increased from about $859 a week in November last year to $894 in June this year, for buyers with a 20% deposit, an increase of $35 a week.
For buyers with a 10% deposit, the mortgage payments would have increased from around $1,111 a week to $1,143 a week, up by $32 a week.
So the trend for first home buyers in Auckland where prices have dropped substantially since they peaked late last year, is that they now need less money for a deposit and a smaller mortgage to buy a lower quartile-priced home, but will be facing slighter higher mortgage payments.
What about in Canterbury where prices have merely flattened?
Not surprisingly, the amount needed for a 20% deposit on a lower quartile-priced home in Canterbury has barely changed, dropping from $110,000 at the March peak to $108,800 in June, down by just $1200, while the amount needed for a 10% deposit is down by just $600 over the same period.
The size of the corresponding mortgages have dropped from $440,000 to $435,200 with a 20% deposit and from $495,000 to $489,600 with a 10% deposit.
Over the same three month period from March to June the average of the two year fixed mortgage rates increased from 4.41% to 5.43%, which pushed up the mortgage payments from $509 a week to $565 a week (+$56) with a 20% deposit, and from $656 to $723 (+$67) a week with a 10% deposit.
That means first home buyers in Canterbury are so far getting very little benefit in terms of the amount they need for a deposit and the amount they need to borrow, but are getting hit harder by rising interest rates.
But that doesn’t mean first home buyers are better off in Auckland than Canterbury.
Auckland remains a hideously expensive place for first home buyers and it’s likely that even with the most recent price falls in the region, first home buyers on average wages are probably still priced out of the market.
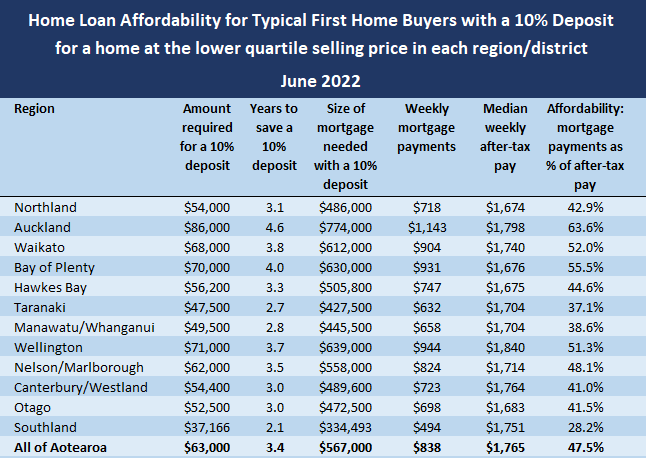
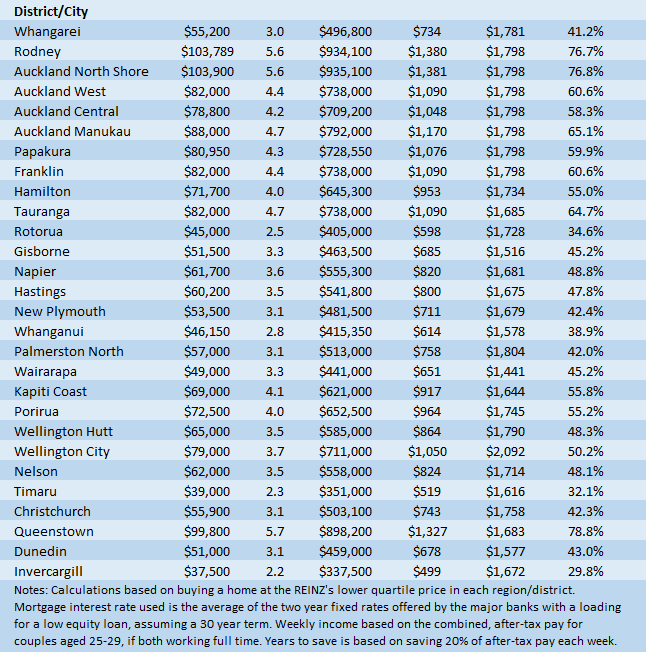
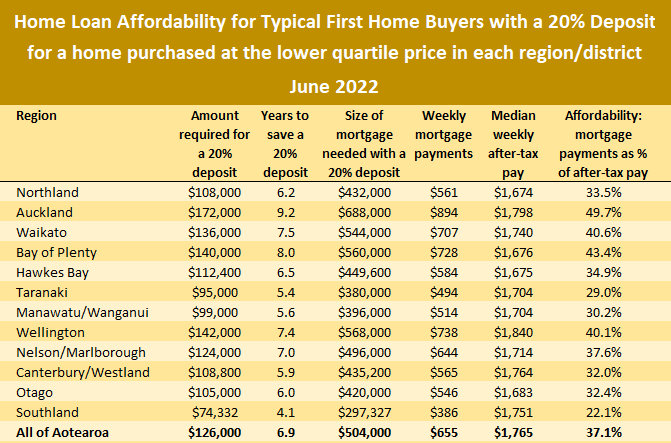
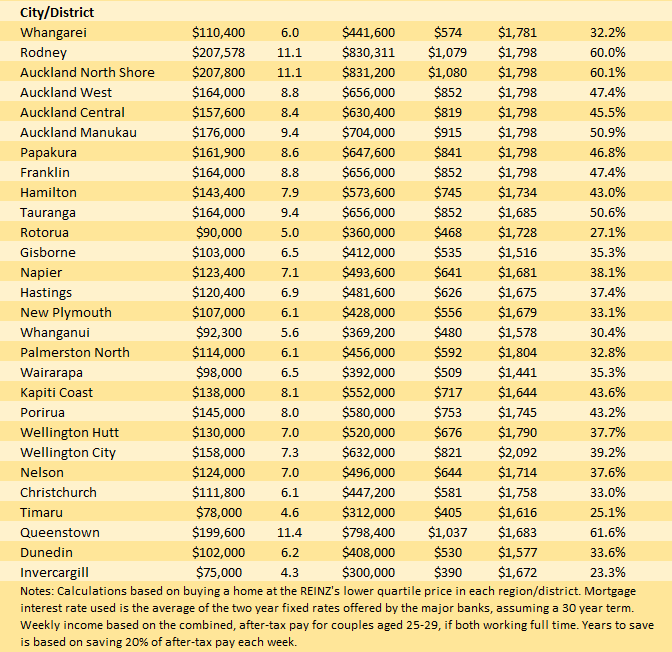
The tables below show the main affordability measures for typical first home buyers in all main urban districts, with either a 10% or 20% deposit:
The comment stream on this story is now closed.
*This article was first published in our email for paying subscribers. See here for more details and how to subscribe.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.