
Home ownership is the most unattainable it has ever been for aspiring first home buyers since interest.co.nz first began compiling the Home Loan Affordability Report in 2004, even though house prices at the bottom end of the market have dropped back considerably from the dizzying heights they reached a couple of years ago.
According to the Real Estate Institute of NZ, the national lower quartile selling price (that's the price point at which 25% of sales are below and 75% are above), was $599,000 in October this year.
That's down $71,000 from the peak of $670,000 in November 2021.
That has reduced the amount needed for a 20% deposit from $134,000 to $119,800, while a 10% deposit has declined from $67,000 to $59,900.
Over the same period, interest.co.nz estimates the national, combined, median, after-tax pay for couples aged 25-29 (assuming both work full time), has increased from $1818 a week to $1990 a week, up by $172 a week (9.5%).
So in the almost two years since the market peak the cost of homes at the bottom of the market has come down significantly, which has reduced the amount needed for a deposit, while household incomes for typical first home buyers have had a reasonable increase, which should have made home ownership more affordable.
But of course it hasn't - rising mortgage interest rates have made sure of that.
Between the market peak of November 2021 and October 2023, the average of the two year fixed mortgage rates offered by the major banks has increased from 4.08% to 7.01%, which has had a major impact on affordability.
A first home buyer who had a 20% deposit for a home priced at the national lower quartile price back in November 2021, would have needed a mortgage of $536,000. The mortgage payments on that would have worked out at about $596 a week at the time.
By October this year a buyer with a 20% deposit for a home at the current lower quartile price would need a mortgage of $479,200, which is $56,800 less than was required in November 2021.
But the rise in interest rates over that period means the payments on an 80% mortgage would have increased from $596 a week to $736 a week, up an extra $140 a week.
Those buyers with just a 10% deposit would be even worse off, with their mortgage payments on a lower quartile-priced home rising from $770 a week to $930 a week over the same period, up an extra $160 a week.
So the rise in interest rates means first home buyers would likely be paying more in mortgage payments now than they were at the market peak, even though houses are cheaper, allowing them to borrow less.
So where does that leave first home buyers?
There has been a long standing rule of thumb in financial circles that to be considered affordable, housing costs, whether they be mortgage payments or rent, should be no more than a third of gross income.
The trouble with that rule is it takes no account of movements in tax rates, which flow into disposable income and therefore affect mortgage affordability.
So interest.co.nz has always used 40% of after-tax pay as a threshold for determining affordability.
Mortgage payments are considered unaffordable if they chew up more than 40% of after-tax pay.
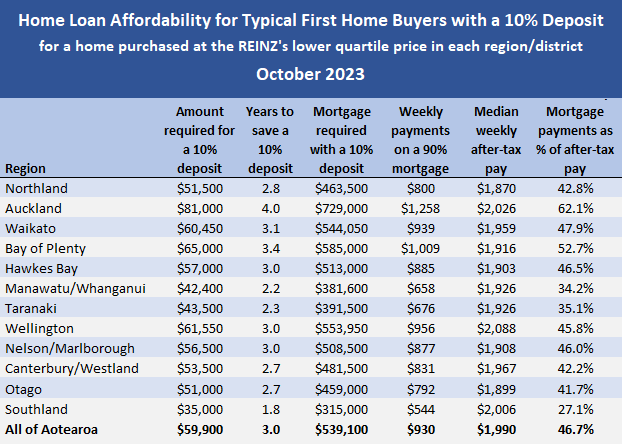
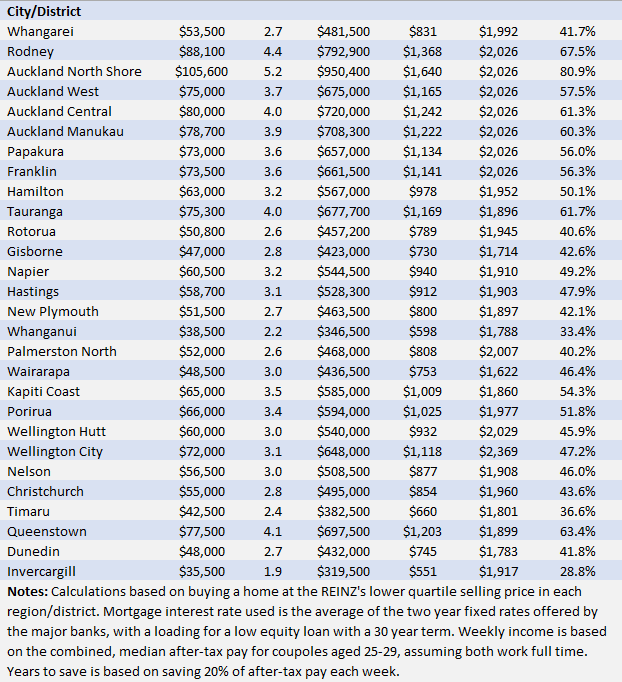
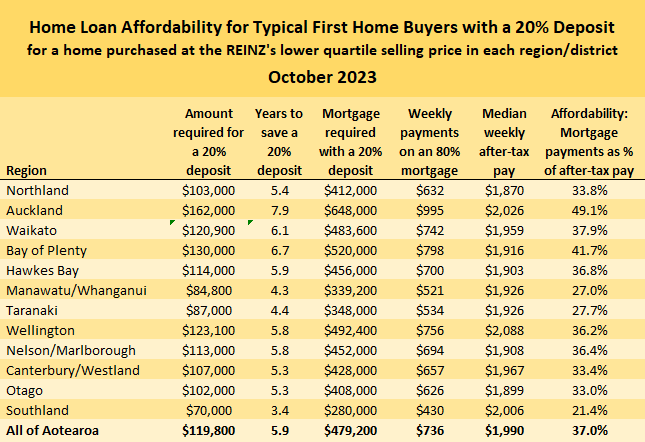
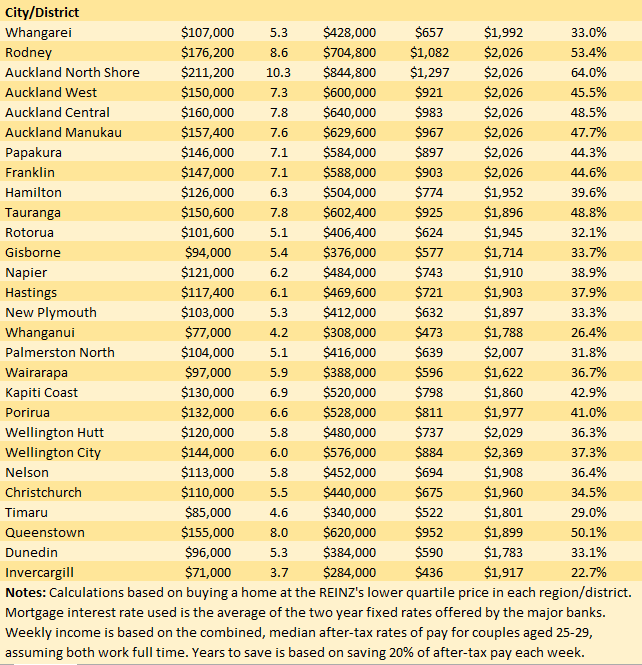
The tables below give the main affordability measures for buyers with either a 10% or 20% deposit in each of the main urban areas throughout the country.
What these show is that at the national level, if a typical first home buyer had a 20% deposit, the mortgage payments on a lower quartile-priced home should still be affordable, although they'd be towards the upper limits of affordability.
The main exception to that is Auckland, where mortgage payments would take up almost half of typical first home buyers' take home pay, and the Bay of Plenty, where they would eat up almost 42% of take home pay, a point at which household budgets would be starting to become tight.
So with the exception of Auckland and the Bay of Plenty, housing should still be affordable for typical first home buyers in most of the country, provided they can put together a 20% deposit.
But that also presents a problem because at the national level, aspiring home owners would need to save almost $120,000 for a 20% deposit on a home at the national lower quartile price, something interest.co.nz estimates would take almost six years if they saved 20% of their after-tax pay each week and put it into an account earning interest at the 90 day term deposit rate.
If that was too hard, they could try to buy a home with a lower deposit.
The trouble with that is that the mortgage would be considered a low equity loan, which would likely attract higher interest rates and/or fees.
At the national level, mortgage payments on a lower quartile-price home purchased with a 10% deposit would swallow almost 47% of typical first home buyers' take home pay, pushing it well into unaffordable territory, and Northland, Waikato, Hawke's Bay, Wellington, Nelson/Marlborough, Canterbury and Otago would join Auckland and Bay of Plenty in the unaffordable club.
Which leaves typical first home buyers between a rock and a hard place.
On the one side there's the rock of an increasingly unattainable deposit, and on the other there's the hard place of unaffordable mortgage payments with a low equity loan.
Which doesn't leave much wriggle room for first home buyers to find their happy place.
- You can have articles like this delivered directly to your inbox via our free Property Newsletter. We send it out 3-5 times a week with all of our property-related news, including auction results, interest rate movements and market commentary and analysis. To start receiving them, register here (it's free) and when approved you can select any of our free email newsletters.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.