

The Reserve Bank introducing restrictions on banks' high loan-to-value (LVR) residential mortgage lending is the right way to cool the Auckland housing "bubble" in the short-term, says the Co-operative Bank's CEO Bruce McLachlan. And doing so won't necessarily have a disproportionately negative impact on first home buyers.
In an interview with Radio NZ's Kathryn Ryan McLachlan said Auckland house prices rising 15% a year was unsustainable and left the broader economy exposed to shocks.
McLachlan, Westpac New Zealand's acting CEO for nine months during 2008 - 2009, said right now the only other alternative to restricting the volume of lending banks do to borrowers with equity of less than 20% in their home, or a deposit worth less than 20% of a house price, would be increasing the Official Cash Rate, which would have a much broader impact.
"In the short-term this (introducing temporary restrictions on high LVR lending) is the only tool I can see other than increasing interest rates, which has a material wider impact," McLachlan (pictured) said. "This is the right answer for me."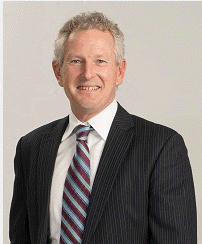
"There's no doubt the bank supply of credit does have an influence on house prices, there's no question."
He said ultimately the only way to tackle the problem of an overheating Auckland housing market would be through increasing supply, noting the government-Auckland Council housing accord aims to build 39,000 houses over three years.
Auckland's biggest real estate agent, Barfoot & Thompson, yesterday said its median June sales price rose 3.5%, or $20,000, to $590,000 and its available listings slumped to an all-time low.
McLachlan told Ryan if the Reserve Bank goes ahead and introduces its proposed "speed limits" on high LVR lending, the success or failure of the policy will depend on where the limits are set and what exemptions are applied.
He noted an example in a Reserve Bank consultation paper that suggested in any three month period banks would be limited to no more than 12% of their mortgage lending being above 80% and no more than 5% above 90%.
"That would have the desired effect," McLachlan said.
The Reserve Bank has estimated that about 30% of new residential mortgage lending is being done at LVRs above 80%.
'It won't necessarily disproportionately impact first home buyers'
Furthermore, McLachlan said concerns raised by Prime Minister John Key over first home buyers being squeezed out of the market if LVR restrictions are put in place could be overcome.
"If we use our example it's still allowing for 12% of any bank's flow in any three month period to be in low deposit mortgages," McLachlan told Ryan. "It's then very much in the hands of the banks, - how would they choose to use the limit they have? They could choose to use that only for first home buyers."
"I don't think we can say automatically that this is going to disproportionately impact first home buyers."
Meanwhile, McLachlan also noted the Reserve Bank has proposed an exemption for any new housing loan that replaces an existing housing loan to the same owner-occupier and that has a loan value and LVR no greater than those of the existing loan, which could be above 80%.
He told Ryan that the more details and exemptions included in the regulations, the more distortions would be created in the market.
"The worst thing that could happen is we go through a big round of new regulation and don't fix the problem," said McLachlan.
Submissions on the Reserve Bank's consultation paper on its proposed framework for restrictions on high LVR residential mortgage lending were due in by yesterday. Policy detail should be finalised by mid-July, with the Reserve Bank introducing new LVR data collection during the second-half of the year.
Ultimately, the Reserve Bank has said LVR restrictions might be imposed, on a temporary basis, with a notice period for banks as short as two weeks.
The central bank has said complying with any restrictions will be a condition of bank registration, or licencing. McLachlan said this meant banks would take them very seriously and put a buffer in place to ensure they don't breach any limit.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.