
Kiwibank's annual profit rose to a record high as income surged and the bank grew lending faster than system, or market-wide, growth.
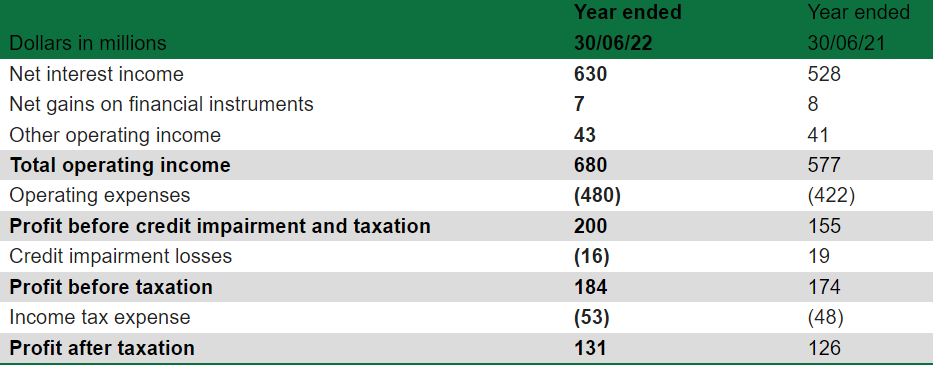
Kiwibank says June year net profit after tax rose $5 million, or 4%, to $131 million from $126 million in the year to June 2021. The bank's previous record annual profit was $127 million in 2015.
Profit rose as Kiwibank's total operating income jumped $103 million, or 18%, to $680 million. This was driven by a $102 million, or 19%, rise in net interest income to $630 million.
Net interest income reflects the difference between the revenue generated from a bank's interest-bearing assets such as loans, and the expenses associated with paying its interest-bearing liabilities such as deposits.
Kiwibank's operating expenses rose $58 million, or 14%, to $480 million. Annual credit impairment losses came in at $16 million versus a write-back of $19 million the previous year.
CEO Steve Jurkovich says Kiwibank grew home lending at the equivalent of 1.2 times system, or market wide growth, and grew business lending at three times system growth.
"Home lending growth of $1.8 billion [ to $23.152 billion] was driven by a strong first half of the year which slowed in the second half due to the consequences of changes to consumer lending laws (Credit Contracts and Consumer Finance Act), loan-to-value ratio (LVR) restrictions, a cooling housing market, and rising interest rates," Jurkovich says.
“Potential buyers are being a lot more circumspect – whether that’s first home buyers holding off, existing owners looking to upsize, or property investors taking a wait and see approach."
“History shows that different cycles occur, and the market will recover. At the same time, we continue to make great progress supporting our customers to achieve their home ownership goals," says Jurkovich.
Kiwibank's business banking grew $0.7 billion to almost $3.8 billion. Total gross lending rose $2.5 billion, or 10%, to $27.8 billion. Deposits from customers increased $1.8 billion, or 8%, to $24.216 billion.
'The models have just got no impairments to respond to'
Jurkovich told interest.co.nz that Kiwibank hasn't really seen an increase in borrower stress despite the sharp rise in mortgage rates over the past year, and highest inflation in 32-years pushing up the price of things such as food and petrol.
"The models have just got no impairments to respond to. We've seen credit card outstandings get paid down, we're seeing people being able to maintain their payments. I do think at the moment they are flexing on the areas that that they can. I know in our own experience I'm sure there are team members who are choosing not to drive into work, not to pay for parking, not to buy lunch in the city because those are some of the costs they can keep a handle on and it might give back $150 a week or something like that," Jurkovich says.
"So we are seeing people make different choices, but no, no stress at the moment. We did a desktop review of people that we have financed into homes in the last 18 months just to see if there was truth to this negative equity conversation. Out of all those thousands and thousands of loans we could find 70 that might possibly be in that situation."
Jurkovich says, however, that Kiwibank's serviceability test rate, the interest rate it uses to stress test mortgage applicants' ability to service their loans, will be reviewed next week. It's currently at 7.25%, and may be increased, potentially to 7.45%.
Kiwibank is owned by NZ Post, the NZ Superannuation Fund and Accident Compensation Corporation through Kiwi Group Holdings, which has recently sold sister businesses Kiwi Insurance and Kiwi Wealth. Kiwibank paid annual dividends of $17 million, up from $6 million in its June 2021 year, and in line with what it paid in the June 2020 year.
The bank's common equity tier one capital ratio, as a percentage of risk weighted exposures, was 10.5% at June 30 down from 10.9% a year earlier. The current Reserve Bank mandated minimum is 7%.
Loans at least 90 days past due rose $1 million to $17 million in the June year, with impaired loans also up $1 million, to $2 million. Kiwibank's credit impairment provisions increased $13 million to $67 million, but Jurkovich says in terms of asset quality, all that was discussed with auditors PwC was economic overlays and management overlays.
Income statement for the year ended 30 June 2022
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.