
By Roger J Kerr

A lot is being written lately about the need to change the model for managing inflation in an economy by means of monetary policy.
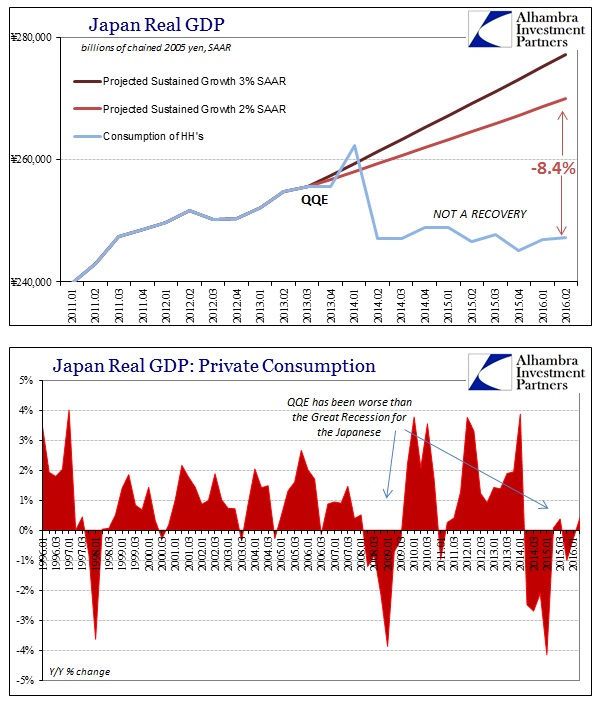
The argument is that with inflation and interest rates at zero in several economies, monetary policy management of cutting interest rates and printing money is not really working to lift economic activity levels to generate higher inflation through demand/supply mismatches. These problems are really confined to Europe and Japan who have been slow and reluctant to introduce major fiscal and micro-economic policy reforms.
It would be dangerous to extrapolate the unique situation in Europe and Japan as also automatically applying to the US, Australia and NZ.
These economies are much more competitive with deregulated industrial and labour markets compared to the dinosaurs of Europe and Japan.
It may be hard to see rising inflation above 0% in Europe and Japan, however the annual inflation rates in Australia and the US are already much higher and would go higher still if oil prices reversed upwards.
The RBNZ are currently struggling to get inflation higher in a free and open economy like NZ as foreign investors like our relative economic performance and keep pushing the NZ dollar higher and ignore the slow/timid interest rate reductions designed to force the currency lower.
However, the RBNZ’s lack of success to date in this regards does not mean we suddenly abandon inflation targeting with monetary policy for some other lofty objectives. If oil prices were to increase back to where they came from at US$100/barrel and that fed into second-round price increases in the NZ economy, the RBNZ would be more worried about the 3% upper limit than being below the 1% lower limit.
Both the Government and the RBNZ are currently rejecting calls to abandon the Policy Targets Agreement to keep inflation between 1% and 3% and they should continue to do so.
Technology advancements are causing the prices for many household items and services to fall.
What would be more useful on the inflation front is a comprehensive study of this impact and also whether the current basket of goods/services that Statistics NZ apply to measure the CPI is still appropriate.
Daily swap rates
Select chart tabs
Roger J Kerr contracts to PwC in the treasury advisory area. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.