By David Skilling*
‘It´s tough to make predictions, especially about the future’, variously attributed to Niels Bohr, Yogi Berra, & others
Last week’s note offered a summary view on the economic and political dynamics that will shape 2023, based on a paper that Mike O’Sullivan and I wrote. We discussed the ways in which structural economic and political dynamics would play out in the year ahead.
But outlooks for 2022 were quickly overtaken by events, most obviously Russia’s invasion of Ukraine in February. So to reflect the deep uncertainty that characterises the world, our paper on 2023 concluded with some ‘wildcards’. These wildcards are not predictions, but (in our view) plausible events. If we have learned anything over the past few years, it is that we should be prepared for the unexpected.
And in a period of economic and political regime change, we should be particularly careful about anchoring on recent experience. This note offers my thoughts on some of the wildcards that we identify for next year.
‘It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so’, unknown, but often attributed to Mark Twain.
Wild cards
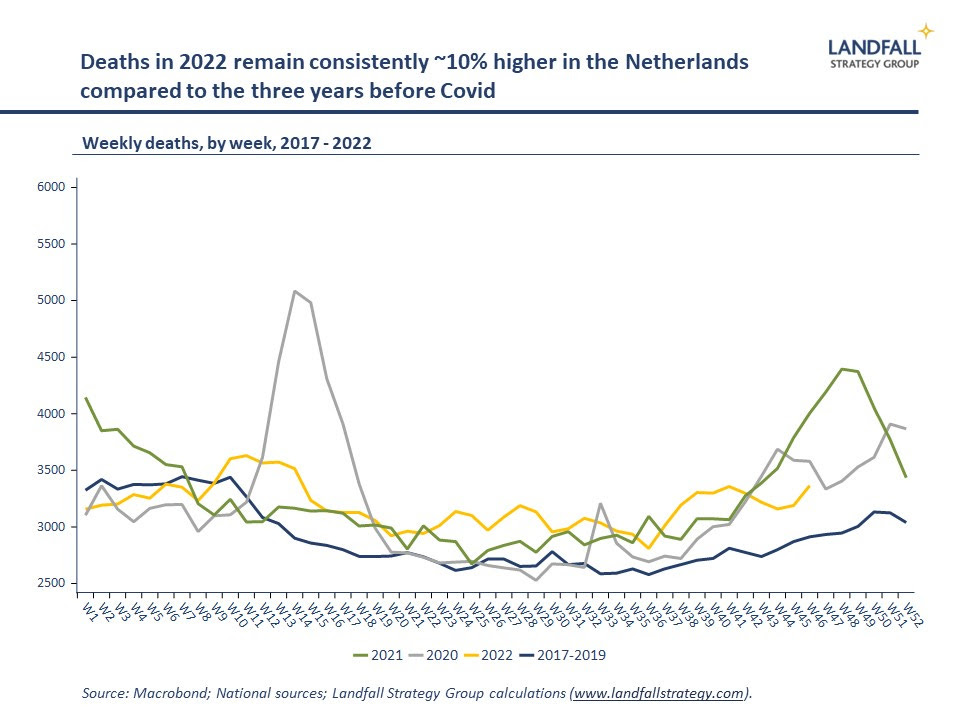
Sudden bull market on a stronger growth outlook due to a structural productivity renaissance. Behind the macro headwinds, there has been stepped-up business investment in innovation and new business models through the pandemic, technology advances (from AI and biotech to nuclear fusion and automation), and sustained increases in R&D spending. Some of these advances are happening more rapidly than expected: Chat GPT, a new AI chatbot, is just one striking example.
2023 and beyond could resemble the roaring 20s a century ago: an optimistic period characterised by a booming stock market, rapid industrialisation, and the widespread adoption of new technologies, such as the automobile and the radio. The 1970s shows that even in periods of disruptive economic and political change, technological progress can accelerate: the PC, the internet, CAT scans, and much else, were developed in the 1970s. [Disclosure: much of this paragraph was drafted by Chat GPT]
Technology stocks have been pummelled this year on higher rates and concerns about profitability. But we may be under-estimating the extent of productivity potential on the near-term horizon.
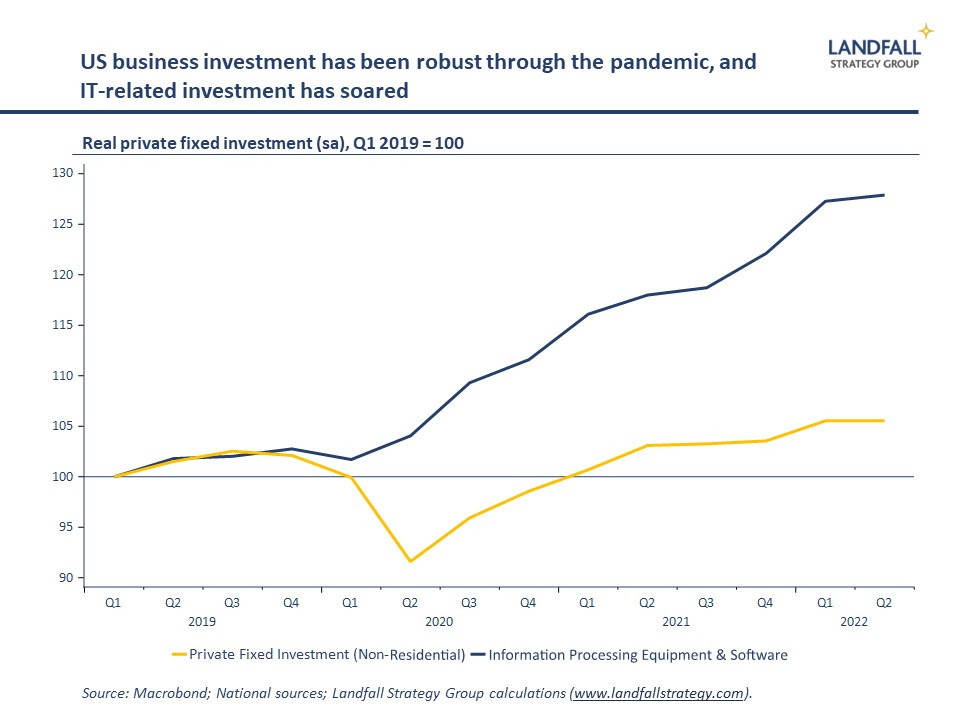
Covid’s back: The pandemic has become background noise in most advanced economies, with lockdowns and other restrictions removed despite ongoing cases. Covid no longer exerts a significant economic impact. China is clearly a different case, and it will struggle to extricate itself from zero Covid. But excess deaths - a useful proxy measure of Covid’s impact, given limited testing data - remain stubbornly high across many advanced economies: I use Dutch data in the chart to illustrate the point.
The big risk is that a more virulent and contagious Covid strain emerges, which is not effectively checked by vaccines. This would place substantial political pressure on advanced economies. Governments have limited political capital to reimpose lockdown measures. And weak policy measures could lead to very substantial economic and social losses – as fear takes hold in domestic economies to a greater extent and global supply chains seize up.
Tipping point on climate change: Extreme weather events are becoming increasingly frequent; through 2022, there was devastating flooding in Pakistan, European droughts, and much else. Attitudes and behaviour to climate change are moving gradually – even if the COP27 meetings did not make meaningful progress.
But further extreme weather events – perhaps causing significant loss of life in a G20 economy – could cause a tipping point in global public attitudes to climate change, leading to much more aggressive, fast-paced action to reduce emissions. The impact of the invasion of Ukraine on European energy prices shows that citizens are prepared to bear costs to change behaviours in the face of challenge.
Firms and economies that engage in emissions-intensive activities may have to move much, much faster to adapt than currently anticipated – with stranded assets and major new investment opportunities. Kim Stanley Robinson’s work of climate change fiction, Ministry for the Future, shows what this could look like.
The Eurasian Spring: Across Eurasia there is growing political unrest and instability. Russia’s economy initially held up better than expected in 2022, but its decline will likely accelerate markedly in 2023. Combined with ongoing evidence of military under-performance and institutional atrophy, regime change in Moscow is increasingly likely (although the end game is not necessarily liberal reforms).
This would accelerate the political instability around the periphery of Russia and across Russian regions. We may see countries in Russia’s near-abroad move decisively out of Russia’s orbit (note Kazakhstan) and for growing centrifugal pressures within Russia. Iran is another major source of political risk, as the regime continues to push back against protests. Major political shocks are possible across the region, which would spill into the global economy: this region is a central commodity exporting node in the global economy.
And China is perhaps the single largest source of domestic political risk. The combination of public anger around Covid lockdown measures, now being relaxed, combined with multiple economic challenges (perhaps reinforced by the likely public health toll from opening up), creates risks to political stability – despite the strong state apparatus. President Xi looked dominant in October at the CCP meetings, but there are fractures. And what happens in China doesn’t stay in China.
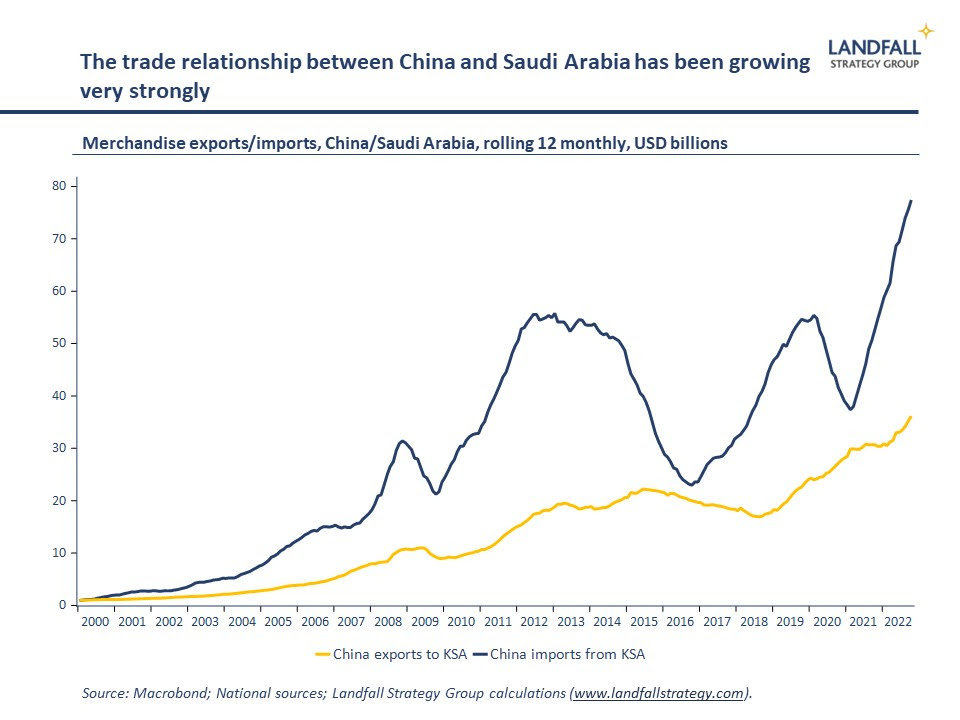
Reconfiguration of the Middle East: The Middle East was at the centre of economic and political regime change in the 1970s, most obviously the two oil shocks. And global regime change may manifest in the region again. Watch for the Gulf states to pivot rapidly towards Asia and carve out more independent positioning, starting with economic and financial relations. In hindsight, the World Cup and President Xi’s visit to Saudi Arabia may be turning points in the Gulf’s relationship with the West.
Combined with ongoing developments of Israel’s links with the Gulf states and the Arab world more broadly, a reconfiguration of Middle Eastern dynamics within the region and internationally is on the cards. Watch also for change in Iran’s behaviour in the region, perhaps with a measure of stabilisation.
Of course, this is just a partial listing. There are many other risks, from financial stability risks as rising rates place greater stress on the global financial system; to military conflict (note India/China border skirmishes this week); to cybersecurity issues (a virus of another kind); and so on.
Things not to worry about
Many of the unexpected events over the past few years have been deeply negative, from the pandemic to Russia’s invasion of Ukraine. It may be that we are overdue some positive surprises. Indeed, there are some risks in the headlines that we assess to be over-estimated.
Taiwan invasion: This is the biggest single geopolitical risk in Asia, with potentially devastating consequences. Some assess the timing of an invasion by China has been brought forward. But our sense is that this is unlikely in the near-term: the economic costs are a major deterrent, as are the observations of the Russian invasion of Ukraine.
Nuclear shock: We don’t expect Russia to use nuclear weapons, although North Korea and Iran will continue to develop nuclear weapons and delivery capabilities.
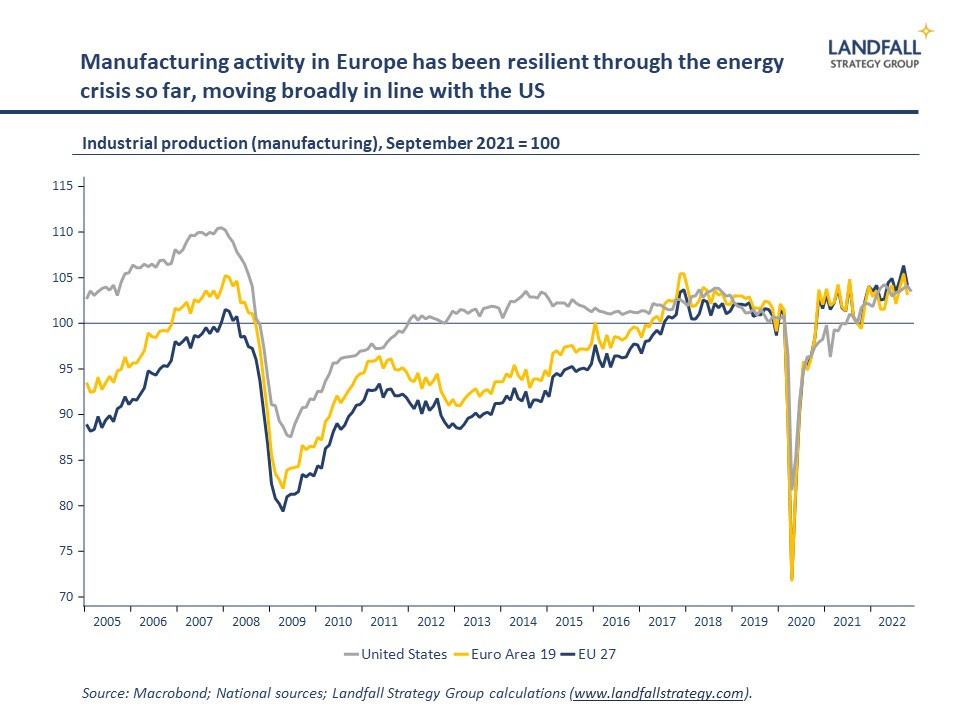
European crisis: Europe is exposed to many risks – from rising rates putting pressure on corporate and sovereign borrowers, to soaring energy prices causing deindustrialisation. But we assess the risks of a financial shock in Europe to be manageable, and European industrial activity is adapting well to the energy price shock so far.
Agility and flexibility in the face of these various risks will be crucial to performance, as will an ability to sift the signal from the noise. But first, a holiday…
*David Skilling ((@dskilling) is director at economic advisory firm Landfall Strategy Group. The original is here. You can subscribe to receive David Skilling’s notes by email here.
**Get in touch (by reply email or at contact@landfallstrategy.com) if you would like to access the full paper referred to in the article above.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.