
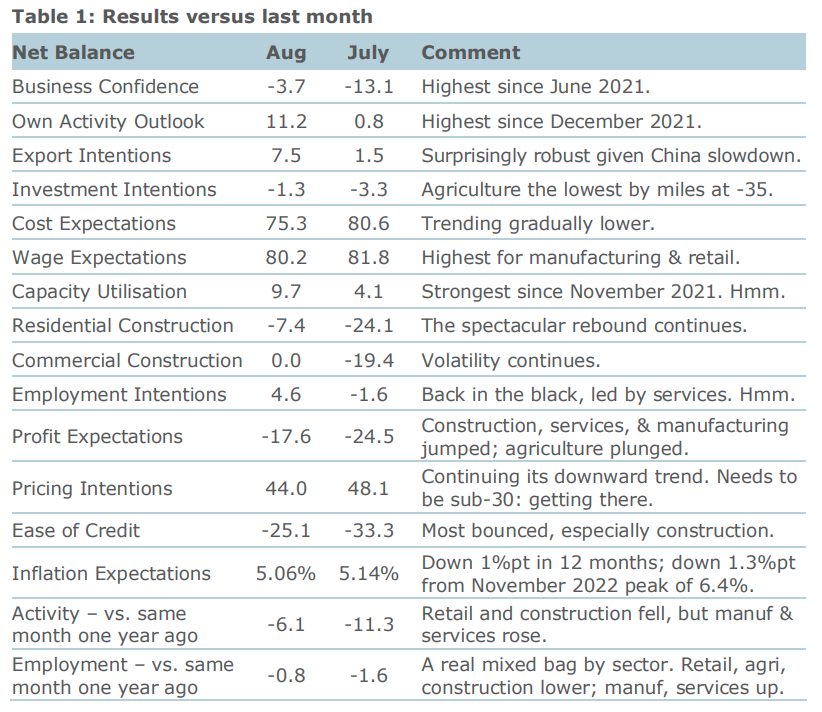
"Goldilocks is in the building," according to the results of the latest ANZ Business Outlook Survey, which shows rising levels of business confidence and activity, but falling inflation indicators.
"While activity indicators are still at subdued levels, they lifted across the board. But we can have our cake and eat it too, for now, at least: inflation indicators continued to ease," ANZ chief economist Sharon Zollner said.
Business confidence lifted another 9 points in August to -4, the highest read since mid-2021. Expected own activity also jumped 10 points, to +11.
"Things could be (and were) worse, according to what firms are telling us in our survey," Zollner said.
"Many firms appear to have been pleasantly surprised at how well demand has held up, considering; and the Reserve Bank has stopped raising the Official Cash Rate (while reserving the right to change their minds), which may be creating a sense that the worst is over."
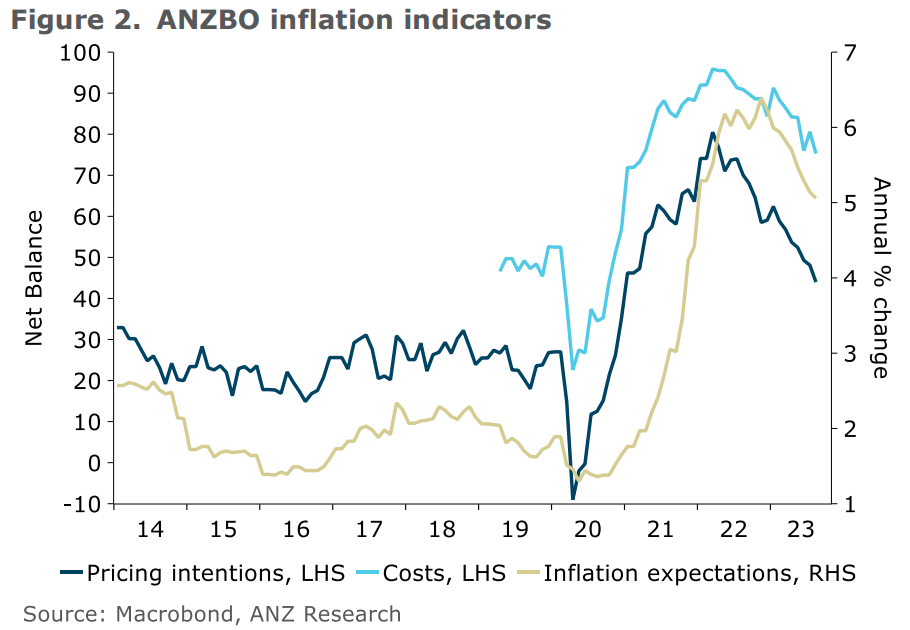
Zollner said despite a reported lift in capacity pressures, inflation expectations and pricing intentions continue to ease slowly but steadily.
“Higher activity but easing inflation pressures speak to a positive supply shock. This year’s surge in labour supply certainly fits that bill, but there will inevitably be demand impacts from net migration too, particularly in housing, and the net inflation impact remains a matter of conjecture.
“Pricing intentions are trending lower in a broad-based fashion. Firms’ views on where they see their own selling prices will be in three months’ time fell to 2.0% (from 2.4% in July).
“Firms’ expected costs in three months’ time relative to today eased from 4.3% to 3.6%, continuing its downward trend. A small tick higher for manufacturing and construction was outweighed by falls elsewhere.
Zollner said the data imply that on average, firms continue to expect margin compression, given costs are expected to lift more than prices over the next three months.
“Expected cost increases are now virtually identical to expected wage increases, whereas over 2022, other costs (physical inputs, transport costs, rent, compliance costs etc) were expected to rise even faster than expected wages, dragging up total expected cost increases."
Zollner said that as a key component of both firms’ costs and household incomes, wage growth is an important determinant of non-tradables (domestic) inflation. Reported past wage increases (versus a year earlier) ticked up to 5.6%. On the other hand, expectations for wage settlements over the next 12 months fell from 4.1% to 3.7%.
“Workers are much easier for firms to find but unemployment is still very low, and inflation signals are dropping away very tidily.
“The agriculture sector is certainly in a very different world, with prices and expected profitability plummeting, but on the other hand the construction sector appears to have taken real heart from the turnaround in the housing market.
“Does it add up to enough to get inflation all the way down to the target band sustainably? Here’s hoping."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.