
By Amanda Morrall
A danger of being on holidays, particularly in a country that is relatively cheap to travel in, is the temptation to spend more than you would otherwise and to let your financial guard down. .At least that was my experience on a trip a few weeks back to Bali.
As holidays are meant to be a vacation, including from yourself, it's hardly any wonder or huge personal finance crime that this should happen. The aggrieving factor for me, post holiday, is not the amount of money put into the hands of locals (that's particulary the case in a developing country) but the amount of money siphoned off by the banks and credit cards companies, disproportionate to the price of the goods and services purchased.
There's a name for this but unless you're one to read the fine print in the mail-out brochure you received when you got your car in the post, you're unlikely to be familiar with it.
In New Zealand, it's what's referred to by banks and credit card issuers as the currency conversion fee. In North America and other continents it's called an FTF: foreign transaction fee.
What tweaked my attention to this was an article I came across on one of the many personal finance blogs I visit. The story, posted on creditcardratings.com, cited the top 36 credit cards without foreign transaction fees. Curious to know whether card issuers here were doing the same, I had a look at the credit card fee section on interest.co.nz. No such luck I'm afraid.
As you'll see from this chart below, the various banks charge between 1.85 and 2.5% for the currency conversion margins. Typically, this fee is calculated by converting the amount of the purchase into New Zealand dollars and then applying the margin.
| Credit card fees | ANZ | ASB | Bank Direct | BNZ |
National Bank |
Kiwi bank |
TSB | Westpac |
| Currency conversion margins | 2.50% | 2.25% | 1.85% | 2.25% | 2.50% | 2.50% | 2.00% | 2.50% |
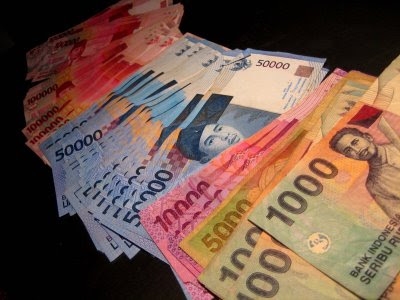
As I've written many times before, I'm not a big credit card user. On this particular trip, I took US$400 in bills and packed my VISA debit card, which I was assured would work, which it did. I did have a back-up credit card, a Canadian card, which I used once on a Western priced boutiquey Bamboo 'hotel" that I fell in love with. When I ran out of cash, I ended up making cash withdrawals (1 million rupiahs NZ$109 at a go) from my New Zealand bank account.
While I expect I'd be fuming over the currency conversion margins, and rightly so given that in more competitive markets there are none, the holiday glow was tarnished instead by the banking charges applied for tapping my savings. For every 1 million rupiah withdrawal, the servicing ATM took $8 and another $3 went to my bank presumably.
In hindsight I probably would have saved myself more than a few bucks by putting everything on the plastic. However, as not many vendors accept VISA or Mastercard I would likely have incurred even higher charges taking out interest bearing cash advances. Another option would have been to take out large sums of money at time, which is normally what I do when I"m forced to use an ATM that doesn't belong to my bank. Due to my discomfort with travelling with large amounts of cash, despite travelling with a very tall Aussie, I was reluctant to go that route. Also, not having been to Bali before and paying in monopoly like amounts, I naively expected 1 million rupiah to last longer than it did. Bali is cheap but not ridiculously so as I'd imagined.
Of course, more planning, more research, having a calculator on hand at all times, would likely have prepared me and allowed me to adopt a strategy that would have saved me some money. My regret isn't the amount of money spent, only that the half a million odd rupiahs (NZ$65) wasted on ATM fees would have been better spent buying stuff from the locals instead.
And the lingering question I have is why NZ credit card issuers aren't waiving currency conversion margins as is the case in the U.S. and elsewhere.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.