Halfway through the Year of Economic Growth, New Zealand’s ‘green shoots’ have yet to bloom and lower interest rates may not be enough to change that.
The Reserve Bank has cut its benchmark interest rate by 225 basis points over the past year, from 5.5% to 3.25%, but the main impact has been a lift in business confidence. Real activity remains weak across most sectors, with agriculture the exception thanks to strong commodity prices.
New Zealand appears to be undergoing what ANZ economists call an “underwhelming economic recovery”, and BNZ describes as “a mid-year wobble”. Recent surveys and labour data show little sign of momentum.
“There was a clear wobble in a whole range of indicators in May. But none more so than the Performance of Services & Manufacturing Indices. Their deeper decline into contractionary territory was not in ‘the recovery’ script,” BNZ wrote in a note.
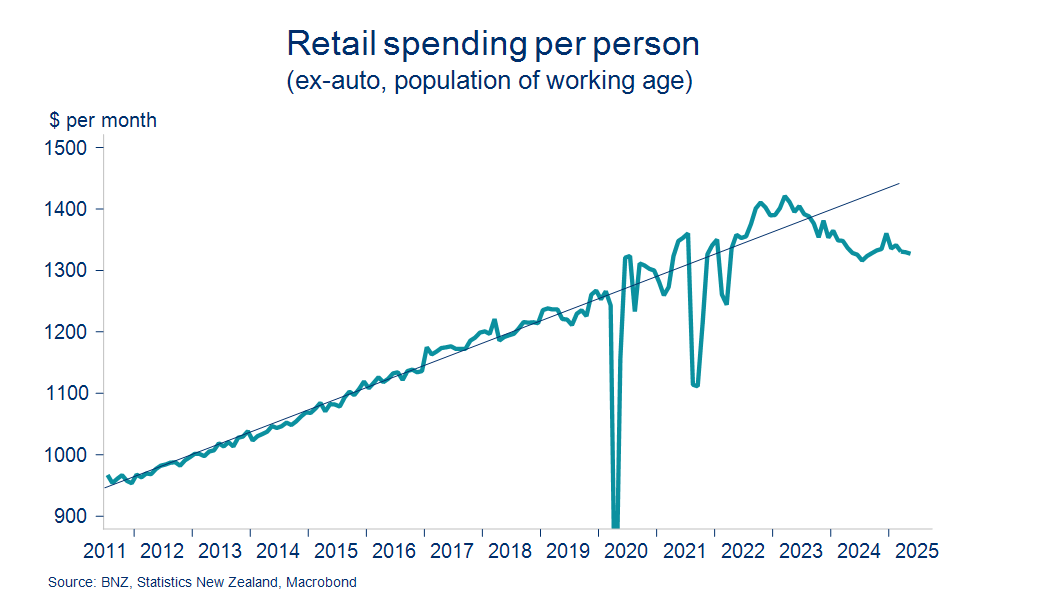
“The failure of retail spending to fire has a lot to do with the stuttering nature of the recovery … to even say spending is flat may be overstating the case.”
Card spending in May was no higher than in September 2022 and remained 6% below its 2023 peak on a per-person basis. Lower interest rates and improving confidence have yet to translate into stronger spending or consumer demand.
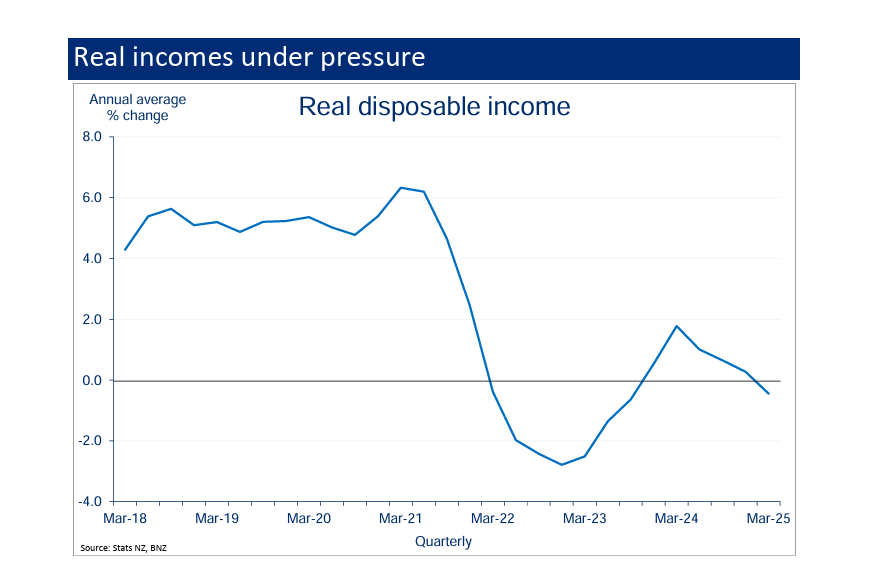
Stephen Toplis, head of market research at BNZ, says experimental Stats NZ data released on Thursday sheds light on why: overall, households are not better off with lower interest rates — in fact, they are worse off.
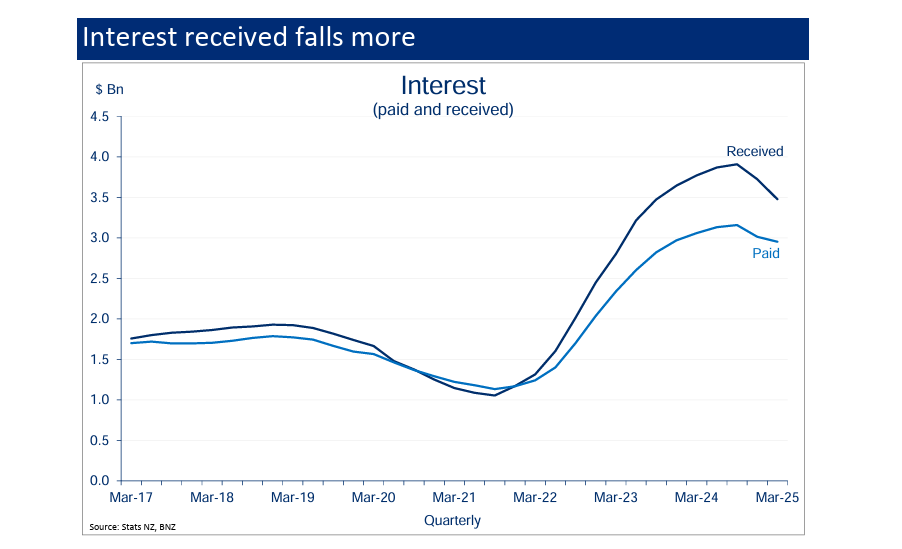
Falling mortgage rates are easing pressure on households with debt. Interest paid in the March quarter was down 3.5% on the same period a year earlier.
“But one shouldn’t forget there is a significant chunk of the population that doesn’t have any debt, many of whom rely on interest income for their day-to-day spending. Believe it or not, the income accruing to these folk has dropped by more than the reduction in the amount paid,” Toplis wrote in a note.
Lower rates aren’t always better
The net effect of falling mortgage and yield rates has been a drop in the total amount of money available for household spending, at least according to this data set.
Lower interest rates don’t automatically boost household spending, as they reduce income for those, particularly retirees, who rely on savings returns.
Toplis says households benefiting from lower interest rates are likely younger and more inclined to spend the extra cash, so the net effect on consumption may still be positive.
“[But] one should not necessarily assume falling interest rates will be sufficient to boost spending in the current environment,” he wrote.
Even if mortgage repayments drop, households may hesitate to spend the extra money while the labour market remains uncertain and asset prices stay flat.
Asset prices are one of the key channels through which monetary policy reaches the real economy. As values rise, households feel wealthier and are more willing to borrow and spend.
While property prices appear to have stabilised as rates have fallen, they show little sign of recovery. CoreLogic NZ said hedonic values rose just 0.2% in June, after twin 0.1% falls in April and May.
“With asset prices going nowhere fast it shouldn’t be a great surprise that household spending is doing likewise,” Toplis wrote.
Stats NZ data shows household net wealth and real disposable incomes are flat or falling, and most of the excess savings built up during the pandemic have now been spent.
“Putting all this together, it becomes increasingly apparent just why the retail sector has been struggling … Monetary easing and the strong income gains accruing to New Zealand’s primary sector will support retail spending but these data are a salient reminder that we shouldn’t expect a resurgence in activity any time soon.”
Voter frustration
New Zealanders appear to be losing patience with the governing Coalition, which promised a stronger economy and cost-of-living relief. Inflation is under control and mortgage rates are falling, but households don’t seem to feel the benefit yet.
A research note by Infometrics said consumer prices are still rising, and now from a higher base. Prices in the March 2025 quarter were 23% higher than five years earlier.
Supermarkets selling 500 grams of butter for $8 to $10 does little to ease public concern about inflation, even if official data shows only modest price growth overall.
Add to that a sense of job insecurity, and many households don’t feel the economy is improving at all. Business confidence is surging, but employment confidence has hovered near Covid-lockdown lows all year.
Job site Seek said its Advertised Salary Index showed annual wage growth of just 2.3% in the year to June. That’s a little below the RBNZ’s inflation forecast of 2.6% over the same period.
If the Reserve Bank pauses rate cuts next week, it may frustrate households who feel the recovery hasn’t started yet. Economists still predict a strong recovery in the second half of the year, but rate cuts alone may not be enough to make that wish come true.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.