
 By Roger J Kerr
While our short-term interest rates are determined by RBNZ monetary policy settings based on the inflation/growth outlook, our long-term interest rates (swaps rates beyond three years) are largely driven by global bond markets.
That is, swap interest rates track NZ bond yields, which follow US and Australian bond yield direction.
In many ways our longer term interest rates behave like exchange rates in that they are relative prices.
If global bond investors prefer one country’s government bonds over another they will buy the preferred bonds (driving the yield down and bond price upwards) and sell the less preferred bond (yield up, bond price down).
So, NZ bond and swap interest rates will move relative to the market movements over other bond markets.
Over the past six months, fixed interest fund managers and sovereign wealth funds have been divesting European government and corporate bonds as they continue to go down in value and have been seeking alternative government bonds to invest into.
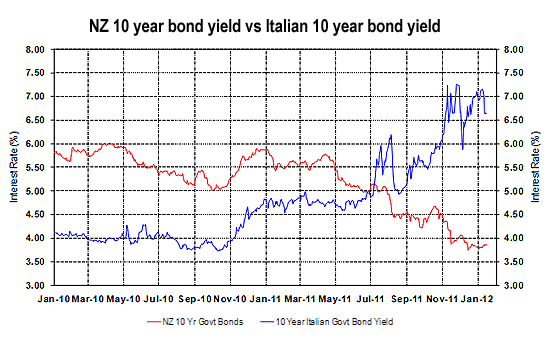
New Zealand and Australian bond markets have benefitted from this relativity change, perhaps artificially holding our long-term interest rates lower than where they would otherwise be given the increased Government bond issuance and inflation/growth outlooks (see chart below).
The question is will global investors continue to buy our bonds when they have finished with their selling of European bonds?
I suspect so, however the latest credit rating downgrade news out of Europe does not suggest this is going to happen anytime soon.
The equally important driver of long-term interest rate direction is local investor demand and borrower supply of debt/bonds onto the market. Local fixed interest fund managers (who were not short of portfolio benchmark duration) produced some pretty impressive returns last year as markets yields declined.
My expectation this year is that these fixed interest managers will now position their portfolio risk from the short-side of benchmark duration - that is, shorten their duration by being sellers of longer-dated securities, not buyers.
They will also be wary of the European financial problems increasing credit spreads across the board, another reason not to be a buyer of long-dated securities.
On the other side of the market, we can expect to see the NZ Government and corporate borrowers issuing as long as they can. All this adds up to higher market swap yields from here rather than a continuation of 2011 decreases.
Short-term interest rates over coming months will oscillate on the prospects of NZ achieving 3% GDP growth in 2012 or not.
My continued view is that the European recession/crisis does not drag the US and Asian economies down and thus our economy has great conditions for strong growth with high export commodity prices and low interest rates. Since the last week of December the moneymarkets have removed the pricing-in of cuts to the OCR in 2012. Current pricing is for no change at all in 2012.
However, as the year unfolds I expect a stronger than expected economic data to progressively change that benign outlook.
--------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.