Predictions of more restrictive lending are playing out with credit bureau Centrix fingering changes to the Credit Contracts and Consumer Finance Act (CCCFA), rising interest rates, tighter loan-to-value-ratio (LVR) restrictions and the business buzz-kill Omicron as the culprits.
The proportion of mortgage applications resulting in approval fell to 34% in February, down from 40% before the CCCFA changes kicked in from December 1, while consumer finance conversion fell from 35% to just 28% of applications, said Centrix.
"Our data shows lending has become more restrictive since changes to the Credit Contracts and Consumer Finance Act came into effect in December, with the number of approvals down again this month," said Keith McLaughlin, managing director at Centrix.
The CCCFA changes kicked in not long after the Reserve Bank began its Official Cash Rate (OCR) tightening cycle in October, a nail in the coffin for low interest rates which, coupled with tightening LVRs and Omicron, created the perfect storm.
"Despite rising interest rates, mortgage arrears remain low, thanks to the large number of fixed mortgages. It is inevitable, however, that rising rates will eventually place increased pressure on households who are also facing rising inflation," said McLaughlin.
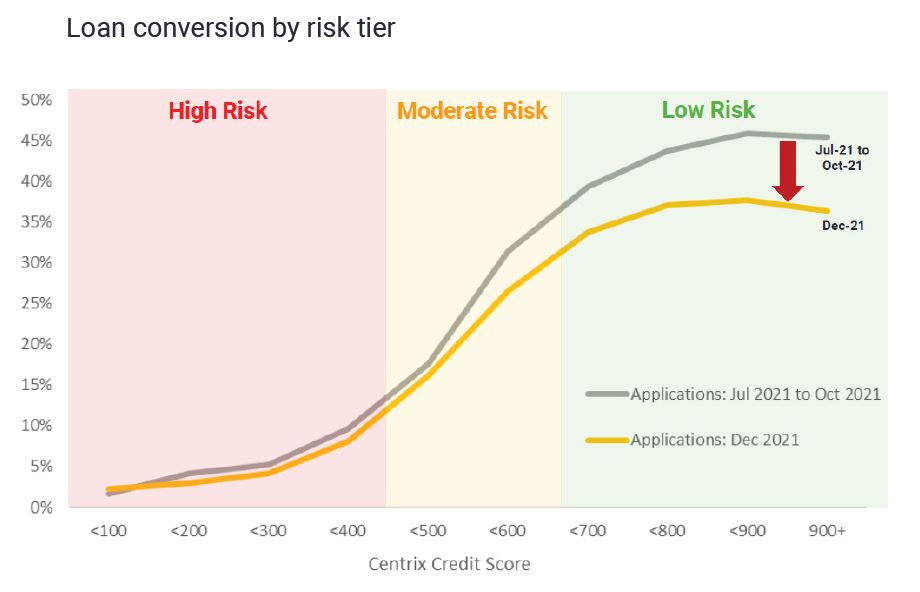
The CCCFA had disproportionately impacted loan approval rates for 'low risk' potential borrowers with a credit score of over 700, which was generally considered to be good, said Centrix.
The higher decline rate was not due to a change in the value of that credit score, but rather the CCCFA's "second leg" of the approval process, the affordability assessment, said McLaughlin.
This part of the process did not allow lenders to apply discretion over a borrower's ability to reduce their discretionary spending if interest rates went up. Instead, it was a snapshot of their spending habits at the time of application.
"Borrowers now have to satisfy the lender they have the ability to meet their financial obligations under different circumstances," he said.
The change was less pronounced in the moderate and high risk categories due to an already high decline rate and the changes making them no more or less appealing to lenders. The change within each risk category is shown in the table below:
Credit demand was flat in February, with demand down 3% y-y and buy now, pay later (BNPL) applications at their lowest since March 2020. While a post-Christmas lull was normal for BNPL, the deep dive this year pointed to the other factors at play, particularly declining consumer confidence amid Omicron.
Auto finance also fell from a peak in January, an annual high point for vehicle purchases anyway, but again a steeper fall than usual.
In line with expected trends, namely the come-down from the squeeze of Christmas bills, arrears increased across all regions in January, but remained low by historical standards.
Financial hardship was at a two year low, reported Centrix, and arrears on credit cards and vehicle loans during 2021 were at their lowest since consumer credit reporting has been in place. However, arrears on personal loans were particularly high.
Meanwhile, the retail sector's credit default rate shot up 24% y-y and Centrix put this down to price pressures, supply issues and less customers through the door while Omicron was rife in the community.
The hospitality and tourism sector continued to be impacted by restrictions and cancellations while construction had strong demand but lacked the labour and materials to meet it.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.