

Table below updated with Westpac's change.
ANZ is the first bank to move its floating home loan rates since the Reserve Bank raised its Office Cash Rate (OCR) last Wednesday.
But they haven't passed on the whole +75 basis points. They have limited the rise to +65 bps enabling them to keep the headline rate below 8%. For existing customers, their new rate will apply from Wednesday, December 14.
In addition they have raised all their fixed rates by +55 bps for all terms to 3 years, +35 bps for longer terms, effective Wednesday, November 30. (This para has been corrected.)
ANZ's bonus saver account, Serious Saver, has been raised by +75 bps effective Thursday, December 1. This is the only ANZ rate to rise by the full +75 bps of the recent OCR increase.
And ANZ raised their term deposit rates by between +40 bps and +70 bps across the board with every term getting a hike. That means their new six month rate will become 4.35% pa and their new one year rate will become 5.10%. For savers, these new levels are much better than any other main bank, and only bettered by the recent rises by Rabobank.
ANZ noted that with the change in OCR and the expectation that the OCR will now have to go higher next year, there have also been changes in wholesale rates which has an impact on fixed interest rates for home loans.
And separately, ANZ economists published a report Tuesday showing forecasts of floating mortgage rates at 8.6% by March 2023 (essentially in three months) and 9.6% by June 2023 with them holding that level for the following year.
A feature of the recent wholesale rate changes has been the sharp flattening of the rate curves, even inversions as global influences drive down the longer term rates. In that context, ANZ's +35 bps and +55 bps fixed rate rises for rates 3 years and longer look somewhat overdone, so there may well be opportunities for rivals to be quite competitive in longer term fixed rates.
Kiwibank has a useful graphic that explains the development of the RBNZ sequence in 2021 and 2022:
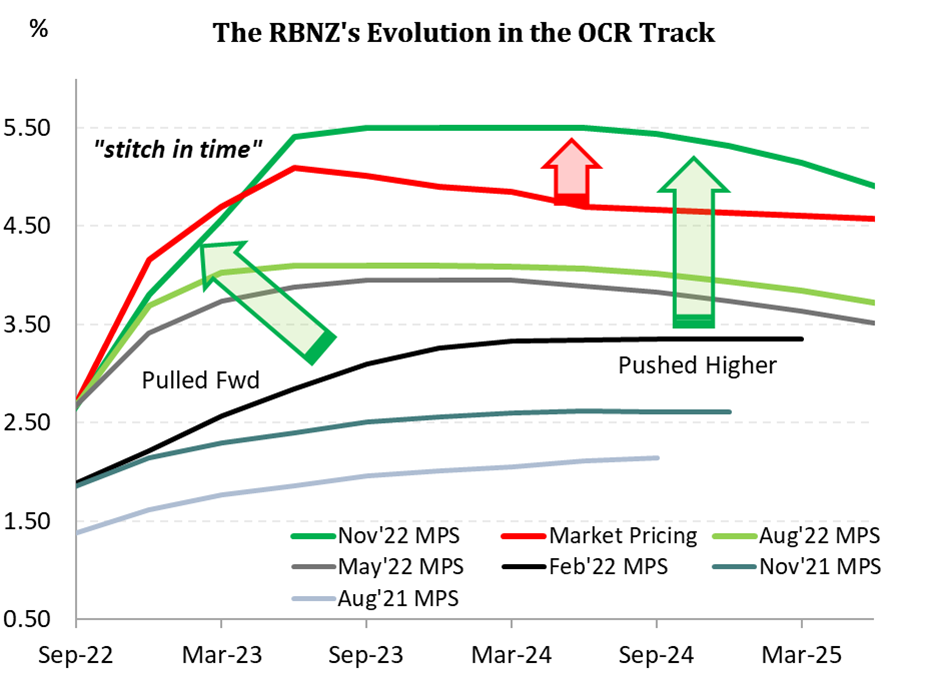
This explains what has happened to the main influences on short term rates. But doesn't help much for the longer term rates and the global influences.
ANZ's pass-through of the full +75 bps for their Serious Saver account is, in the context of how banks usually handle these products, an unexpected benefit for savers.
We will have more soon on the term deposit rate changes, and the fixed home loan rate changes.
Now that ANZ has moved, we expect most other banks will now do so quickly.
Here is the running tally of bank changes to floating rates which we will update as each announcement is received.
| Floating mortgage rates | Prior rate | change | New rate | Existing customers, |
| % | bps | % | effective date | |
| RBNZ OCR | 3.50 | +75 | 4.25 | 23 November 2022 |
| ANZ | 7.34 | +65 | 7.99 | 14 December 2022 |
| ASB | 7.35 | +64 | 7.99 | 14 December 2022 |
| BNZ | 7.29 | +45 | 7.74 | 23 December 2022 |
| Kiwibank | 7.00 | +75 | 7.75 | 19 December 2022 |
| Westpac | 7.35 | +64 | 7.99 | 15 December 2022 |
| Cooperative Bank | 7.15 | +60 | 7.75 | |
| Bank of China | 6.45 | |||
| China Construction Bank | 7.34 | |||
| Heartland Bank | 5.49 | +50 | 5.99 | |
| HSBC | 7.29 | +65 | 7.94 | 15 December 2022 |
| ICBC | 7.15 | |||
| SBS Bank | 7.29 | |||
| TSB | 7.25 |
We will separately report the fixed rate increases when some arrive.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.